Most small business owners spend a lot of time thinking about growing their revenue. Very few spend time thinking about protecting what they’ve already built. That’s a problem. Because if something goes wrong — a client sues, a vendor dispute turns ugly, a customer slips in your store — the question isn’t just whether your business survives. It’s whether you survive.
Personal asset protection isn’t about being paranoid. It’s about being smart. Here’s what every small business owner needs to know about keeping their house, savings, and personal finances out of reach when business goes sideways.
Why Your Personal Assets Are at Risk (Even If You Think They’re Not)
Here’s the uncomfortable truth: if you’re running a business as a sole proprietor, your personal bank accounts, your car, your home, and your retirement savings are all fair game in a lawsuit or debt collection action. There’s no legal wall between you and your business. You are the business.
Even if you’ve formed an LLC or corporation, you’re not automatically protected. Courts can and do “pierce the corporate veil” — meaning they hold the owner personally liable — when business owners commingle personal and business funds, fail to maintain proper records, or use the entity as a personal piggy bank.
The good news: proper planning can close most of these gaps without requiring you to spend tens of thousands on attorneys.
Step 1: Choose the Right Business Structure
The foundation of personal asset protection is entity structure. Here’s the short version:
- Sole proprietorship: Zero protection. Your personal assets are fully exposed. If you’re operating as one, fixing this should be your top priority.
- Single-member LLC: Strong protection in most states when maintained properly. The LLC separates your personal liability from business debts and lawsuits — but only if you treat it like a real separate entity.
- Multi-member LLC or S-Corp: Generally offers the same liability shield, with potential tax advantages depending on your income level.
- C-Corp: The strongest separation, but also the most complex and expensive to maintain. Usually overkill for most small businesses.
For most small business owners, a single-member LLC or S-Corp gets the job done. The key is not just forming it — it’s running it correctly.
Step 2: Keep Business and Personal Finances Completely Separate
This is where most small business owners make the mistake that costs them everything. You form an LLC, then proceed to run business expenses through your personal credit card, pay your mortgage from the business account, and mix cash deposits without a second thought.
Commingling funds is one of the most common reasons courts pierce the corporate veil. The moment a judge decides your LLC isn’t a real separate entity, your personal protection disappears — retroactively.
The fix is simple and non-negotiable:
- Dedicated business checking and savings accounts
- A business credit card used exclusively for business expenses
- A formal process for paying yourself — either a salary (if S-Corp) or owner draws documented properly (if LLC)
- Never paying personal bills directly from the business account
It sounds basic, but the number of small business owners who skip this step and later pay the price is staggering.
Step 3: Use Contracts — Every Single Time
One of the fastest ways to get dragged into an expensive legal dispute is to operate on handshakes and verbal agreements. A well-written contract does two things: it sets clear expectations upfront, and it limits your exposure if things go wrong.
At minimum, every small business owner should have:
- Client service agreements that define scope, payment terms, and what happens in disputes
- Independent contractor agreements for anyone doing work for you who isn’t a W-2 employee
- Terms and conditions on your website if you sell products or services online
- Liability waivers if your business involves any physical risk to customers
You don’t need to pay a lawyer $500/hour to draft all of these. Services like LegalZoom offer attorney-reviewed templates at a fraction of the cost, and many industry-specific contract templates are available through trade associations. The point is to have something in writing — not to have the perfect document.
Step 4: Get the Right Insurance
An LLC limits your personal liability in a lawsuit — but it doesn’t make your business judgment-proof. If your business loses in court, your business assets are still at risk. Insurance is what protects those.
The most important policies for most small businesses:
- General liability insurance: Covers bodily injury, property damage, and related lawsuits. This is the baseline every business needs.
- Professional liability (E&O) insurance: If you provide advice, designs, or services that clients rely on, this covers claims that your work caused financial harm.
- Business owner’s policy (BOP): Bundles general liability and commercial property insurance at a lower cost than buying separately — a good fit for most small businesses.
- Umbrella policy: Provides coverage beyond your standard policy limits, typically at a low cost per dollar of added protection.
The SBA has a useful primer on business insurance requirements by state and business type — worth reviewing if you’re not sure what coverage applies to your situation.
Step 5: Protect Your Personal Assets Proactively
Even with a solid entity structure and insurance in place, smart business owners take an additional layer of personal precaution. This isn’t about hiding assets — it’s about structuring your personal finances in ways that are legally protected.
- Retirement accounts (IRAs, 401(k)s) are protected from creditors under federal bankruptcy law — contributing to them isn’t just smart financially, it’s a legitimate protection strategy.
- Homestead exemptions in many states protect a portion of your home’s equity from business creditors. Know what your state offers.
- Tenancy by the entirety — a form of joint property ownership available to married couples in some states — shields property from the individual debts of either spouse.
- Asset protection trusts are more advanced tools, but for businesses with significant assets, they’re worth discussing with an attorney.
Step 6: Maintain Your Corporate Formalities
Forming a legal entity isn’t a one-and-done event. You have to actually act like a separate entity — consistently and over time. Courts look at behavior, not just paperwork.
What that looks like in practice:
- Hold and document annual meetings (even if it’s just you — write it down)
- Keep records of major business decisions
- File required state reports and pay fees on time
- Maintain a registered agent
- Never sign personal guarantees unless you absolutely must, and understand what you’re signing when you do
Many business owners think this is bureaucratic overhead. It’s actually the documentation that proves your business is real — and the documentation that protects you if you ever have to prove it in court.
What You Can Do This Week
Personal asset protection isn’t complicated, but it does require intentional action. Here’s a quick audit you can do on your own:
- Are you operating under a formal entity (LLC, S-Corp, etc.)? If not, that’s step one.
- Do you have a dedicated business bank account and credit card that you never mix with personal use?
- Do you have written contracts for your clients and vendors?
- Do you carry at minimum general liability insurance?
- Have you maxed out available retirement account contributions?
- Are you filing annual state reports and maintaining your entity in good standing?
If you answered no to any of these, you have a gap. The good news is that most of these gaps can be closed for a few hundred dollars and a few hours of your time — well before a problem ever arises.
The businesses that survive long-term aren’t just the ones that grow the fastest. They’re the ones that protect what they build. Don’t let a single bad day undo years of work because the right structures weren’t in place.
Want more strategies like this? Join thousands of business owners who get practical, no-fluff guidance every week. Join free here.
Ready to Know Where You Stand?
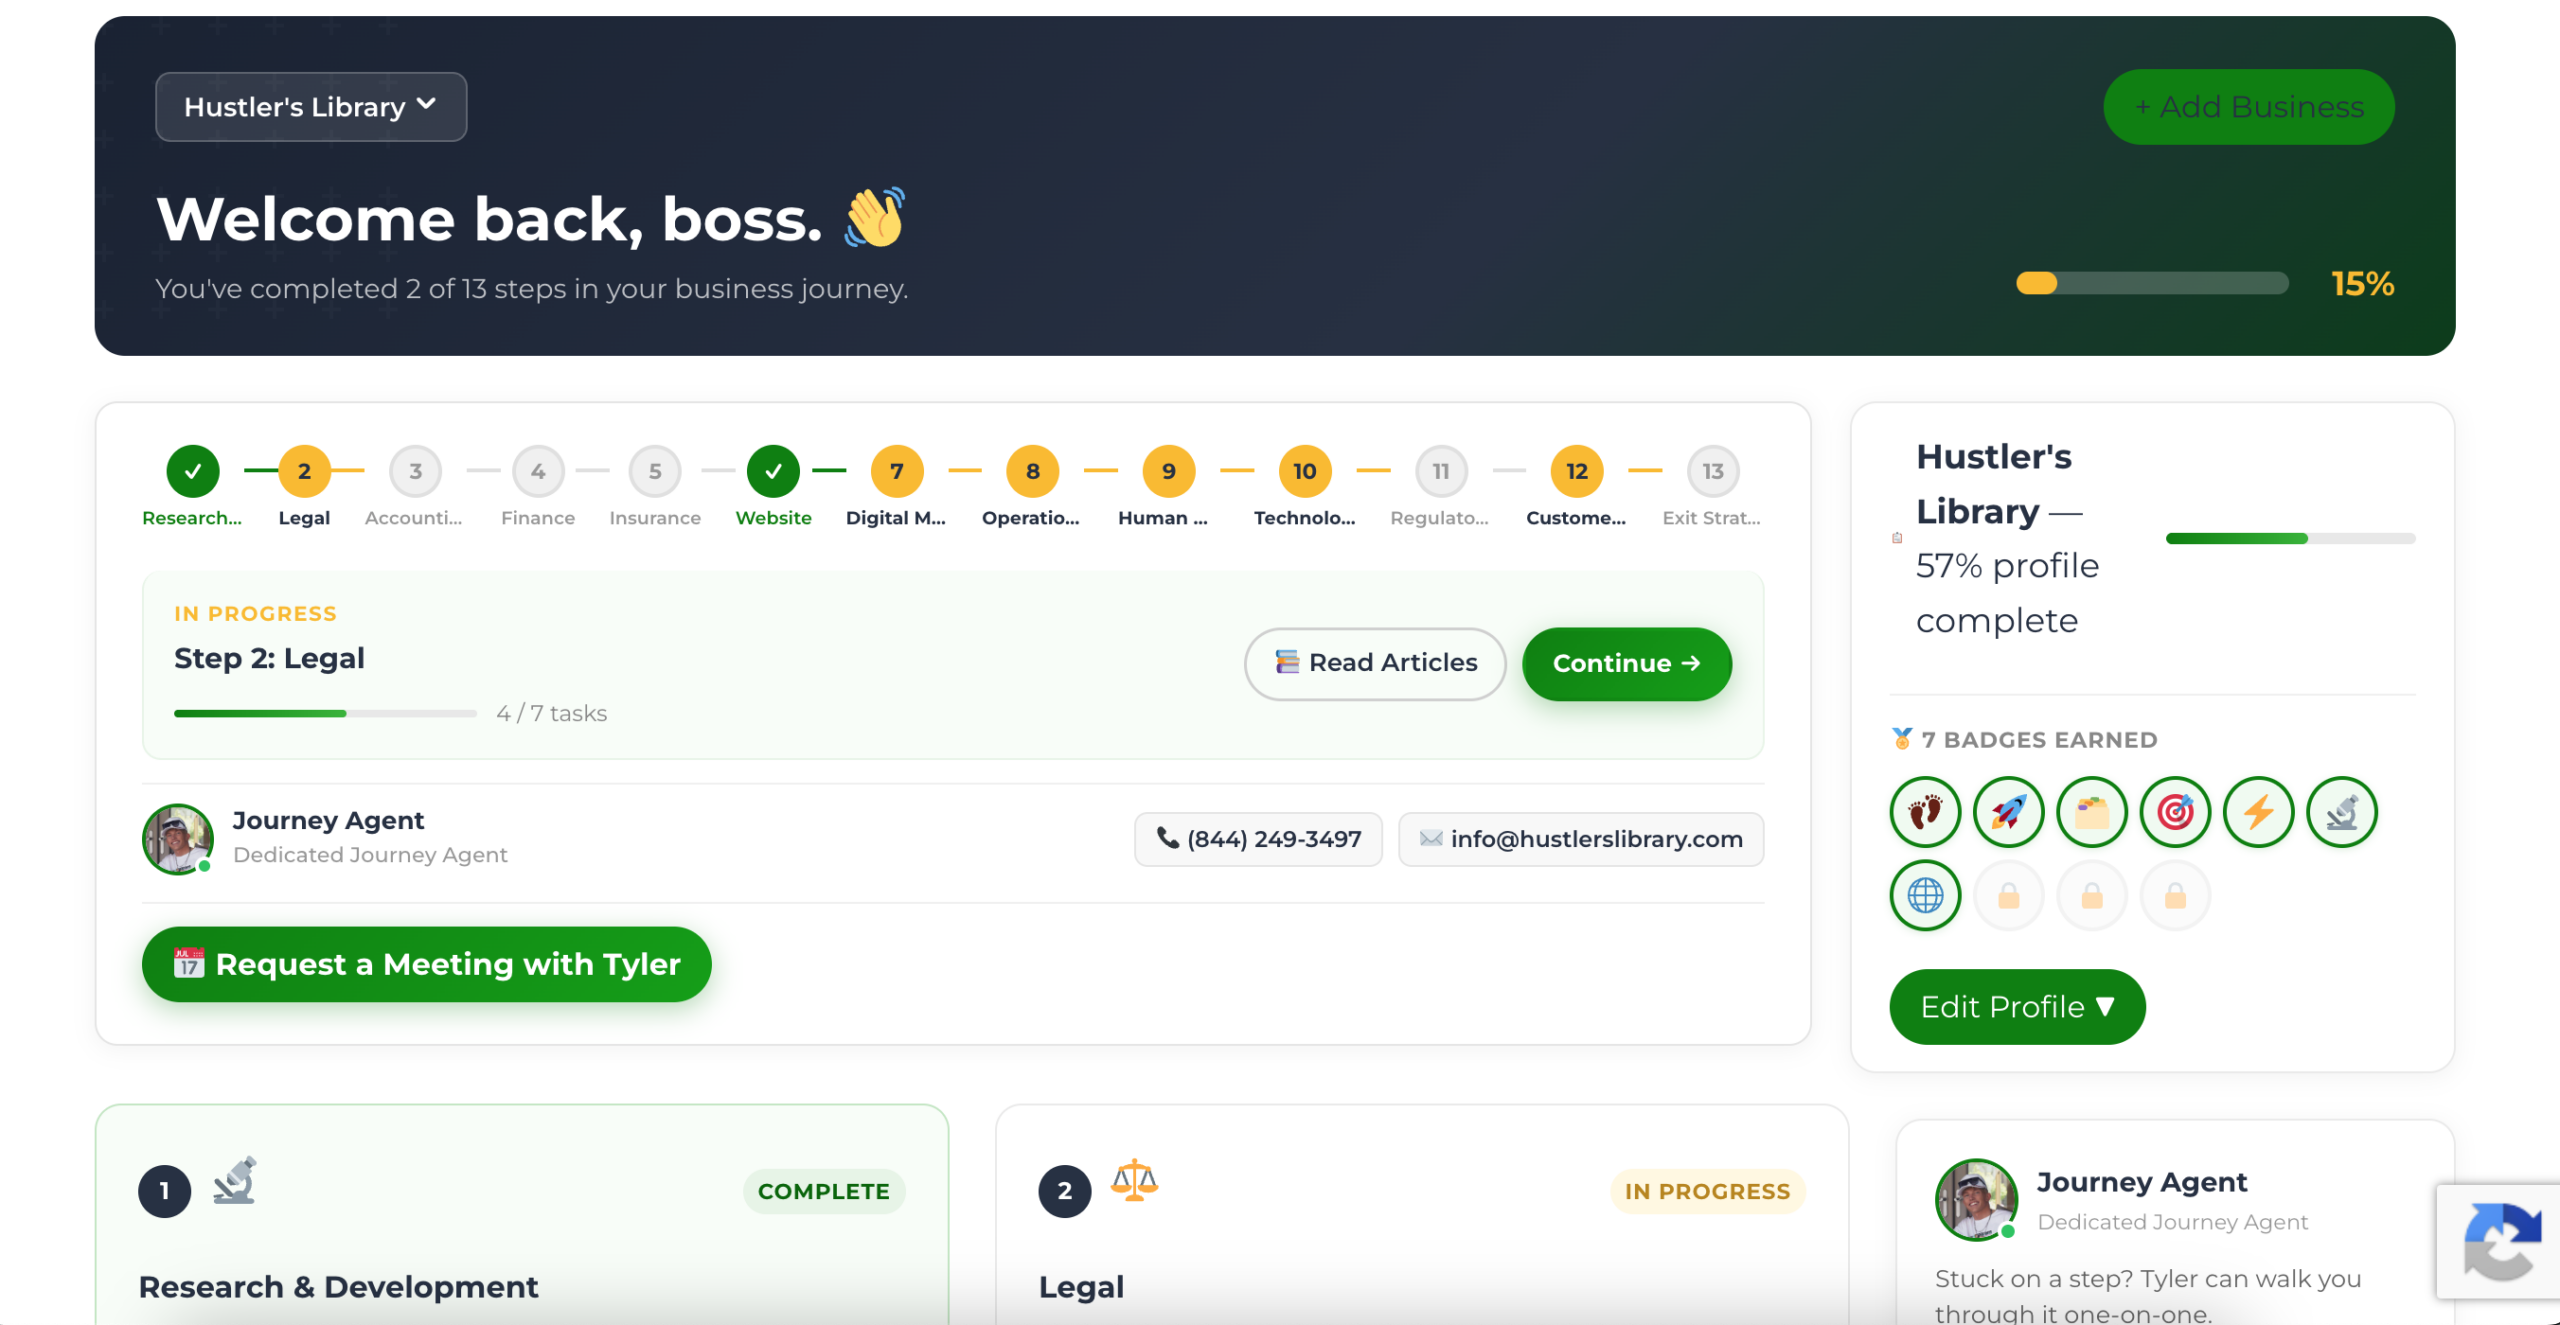
The Business Journey dashboard maps your exact position across all 13 stages. Track your progress, unlock resources for each step, and build with a framework used by thousands of founders at Hustler's Library.
No credit card required · Takes 3 minutes · Personalized to your stage