Every entrepreneur has had the moment. You are in the shower, or stuck in traffic, or halfway through a meal you did not order, and it hits you: an idea. Something that feels obvious once you see it. Something that feels, unmistakably, like an opportunity.
But here is the uncomfortable truth most business books will not tell you directly: most ideas that feel like opportunities are not. And some ideas that feel unremarkable turn out to be the ones that build real businesses.
The difference between a good idea and a great one is not creativity. It is not passion. It is not even timing, though timing matters. The real difference comes down to a handful of structural qualities that separate businesses worth building from projects worth abandoning early.
This is how to tell the difference before you spend a dollar.
A Good Idea Solves a Problem. A Great Idea Solves a Problem People Are Already Paying to Solve.
The first filter for any business idea is simple: does this solve a real problem? But that is the low bar. Thousands of ideas clear it and still fail.
The higher bar is this: are people already spending money, time, or energy trying to solve this problem in some imperfect way? If the answer is yes, you are looking at a proven market. If the answer is no, you may be creating a category from scratch, which is expensive, slow, and risky.
Look for the workaround. When people duct-tape together spreadsheets, hire assistants to do what software should do, or use a product in a way it was never designed for, that is a signal. They are already paying the cost of a bad solution. Your job is to offer them a better one.
Good idea: “I could build an app that helps people track their morning routines.” Great idea: “I could build a tool for personal trainers who are currently texting their clients manually every day because no scheduling software works the way they need it to.”
One has a problem. The other has a buyer who is already paying for an inferior version of the solution.
A Good Idea Has Customers. A Great Idea Has Customers Who Are Easy to Find.
Addressable market matters, but distribution matters more in the early stages. An idea can target a huge population and still be nearly impossible to build into a business if you cannot reach those people efficiently.
Ask yourself: where do my potential customers already gather? Are there communities, trade associations, LinkedIn groups, subreddits, conventions, or neighborhoods where these people congregate? Can I reach them without spending $50 to acquire a $30 customer?
The best early-stage businesses are built on tight, reachable niches. A legal compliance consultant who targets craft breweries. A bookkeeper who only works with real estate investors. A photographer who only shoots product images for e-commerce brands on Amazon.
These are not small ambitions. These are smart starting points. A concentrated market lets you build a reputation, sharpen your offer, and grow through word of mouth before you need a marketing budget. If you understand how to position your offer for a specific customer, your cost to acquire each new one drops dramatically. That is where sustainable businesses begin.
A Good Idea Has Revenue Potential. A Great Idea Has Margin Potential.
Revenue and profit are not the same thing. A business can generate impressive top-line revenue and still be a treadmill that never builds wealth. Great business ideas have margin baked in from the start.
Think about this structurally. Does your idea require you to sell your time hour by hour? If so, your revenue is capped by your hours. Does it require expensive materials, labor, or overhead before you earn anything? That compresses margins. Does it require a massive team to deliver at scale? That adds operational complexity and cost.
Great ideas often have some version of leverage: a digital product that sells while you sleep, a service that can be delivered by a trained team without you, a recurring fee that compounds over time, or expertise that justifies premium pricing. Understanding the difference between fixed costs versus variable costs in your model tells you a lot about whether scale works in your favor or against you.
When you evaluate your idea, sketch out the economics at 10 customers, 100 customers, and 1,000 customers. Does the margin hold or collapse? Does the delivery get easier or harder? Does your role stay manageable or become impossible?
A Good Idea Sounds Exciting. A Great Idea Survives the Reality Test.
One of the most important things you can do with a business idea is try to kill it. Not because pessimism is useful, but because stress-testing forces you to find the weak points before the market does.
Ask the hard questions early. What is the most obvious reason this fails? Who already does something like this, and why would someone choose me over them? What happens if a large competitor copies this in six months? What does the first 90 days of selling this actually look like?
The ideas that hold up under this kind of pressure tend to have durable advantages. Maybe the advantage is deep domain expertise that is hard to replicate. Maybe it is a proprietary process, a trusted relationship network, or access to a distribution channel a competitor cannot easily replicate. Maybe it is simply a founder who understands a niche so specifically that a large generalist competitor would never bother targeting it.
The goal is not to find an idea with no competition. That usually means there is no market. The goal is to find an idea where you have a real and sustainable reason to win, even in a competitive environment.
A Good Idea Gets You Excited. A Great Idea Still Makes Sense When You Are Not Excited.
Passion is real and it matters. But it is not a business model. The problem with excitement as your main filter is that excitement fades. It fades when you are dealing with your sixth difficult client of the month. It fades when a competitor launches a product that is 80 percent as good as yours at half the price. It fades when your revenue flatlines for three months.
What remains when passion recedes is the underlying economics of the business. Does the work still get done? Are customers still getting results? Are you still getting paid? If the answer depends on you being emotionally fired up at all times, the business is fragile.
Great business ideas are ones where the structure carries the business forward even in low-energy periods. The revenue model works, the systems are clear, and the value delivered is consistent regardless of how the founder is feeling on a given Tuesday morning.
That does not mean you should build a business you hate. It means you should find the overlap between something you can do well and something the market will pay for, and then build it in a way that does not require a constant injection of personal energy to keep it alive.
The Fastest Way to Know Which You Have: Try to Sell It Before You Build It
The single fastest validation tool available to any entrepreneur is a sales conversation. Not a survey. Not a focus group. An actual offer, described to a real potential customer, with a price attached.
If you cannot describe your offer in two sentences, it is not ready. If everyone says they love it but no one commits even conditionally, it is not ready. If you have to explain for three minutes before the other person understands the value, you have a positioning problem, a product problem, or both.
Great business ideas tend to land fast. The potential customer already knows they have the problem. When you describe the solution, they connect it immediately to their own situation. You spend less time convincing and more time scoping and closing.
According to the SBA’s guidance on market research, the most useful form of validation is direct customer discovery: talking to real buyers about their actual problems before you invest in building the solution. That research does not have to be formal. It just has to be honest.
Ten real conversations with potential customers will tell you more about whether your idea is good or great than a hundred hours of planning in isolation. The 5 growth levers every small business owner has all start from the same foundation: a clear understanding of who your customer is and what they genuinely need. That clarity only comes from asking.
The Bottom Line
Good ideas are everywhere. Most people who have ever thought seriously about business have had several of them. Great ideas are rarer, not because inspiration is rare, but because most people evaluate ideas with enthusiasm instead of rigor.
Run your idea through these filters before you invest your savings, your time, or your reputation in it. Is the problem real, proven, and already being paid for in some imperfect way? Are the customers reachable without burning through capital? Do the economics hold up at scale? Does the idea survive adversarial questioning? Does it work even when you are not personally excited about it? And can you actually sell it to a real person today?
If the answer to most of those questions is yes, you are not just sitting on a good idea. You might be sitting on something worth building.
Want more frameworks for building a smarter, more profitable business? Join thousands of entrepreneurs at Hustler’s Library for free access to guides, playbooks, and resources that help you build the right way.
Ready to Know Where You Stand?
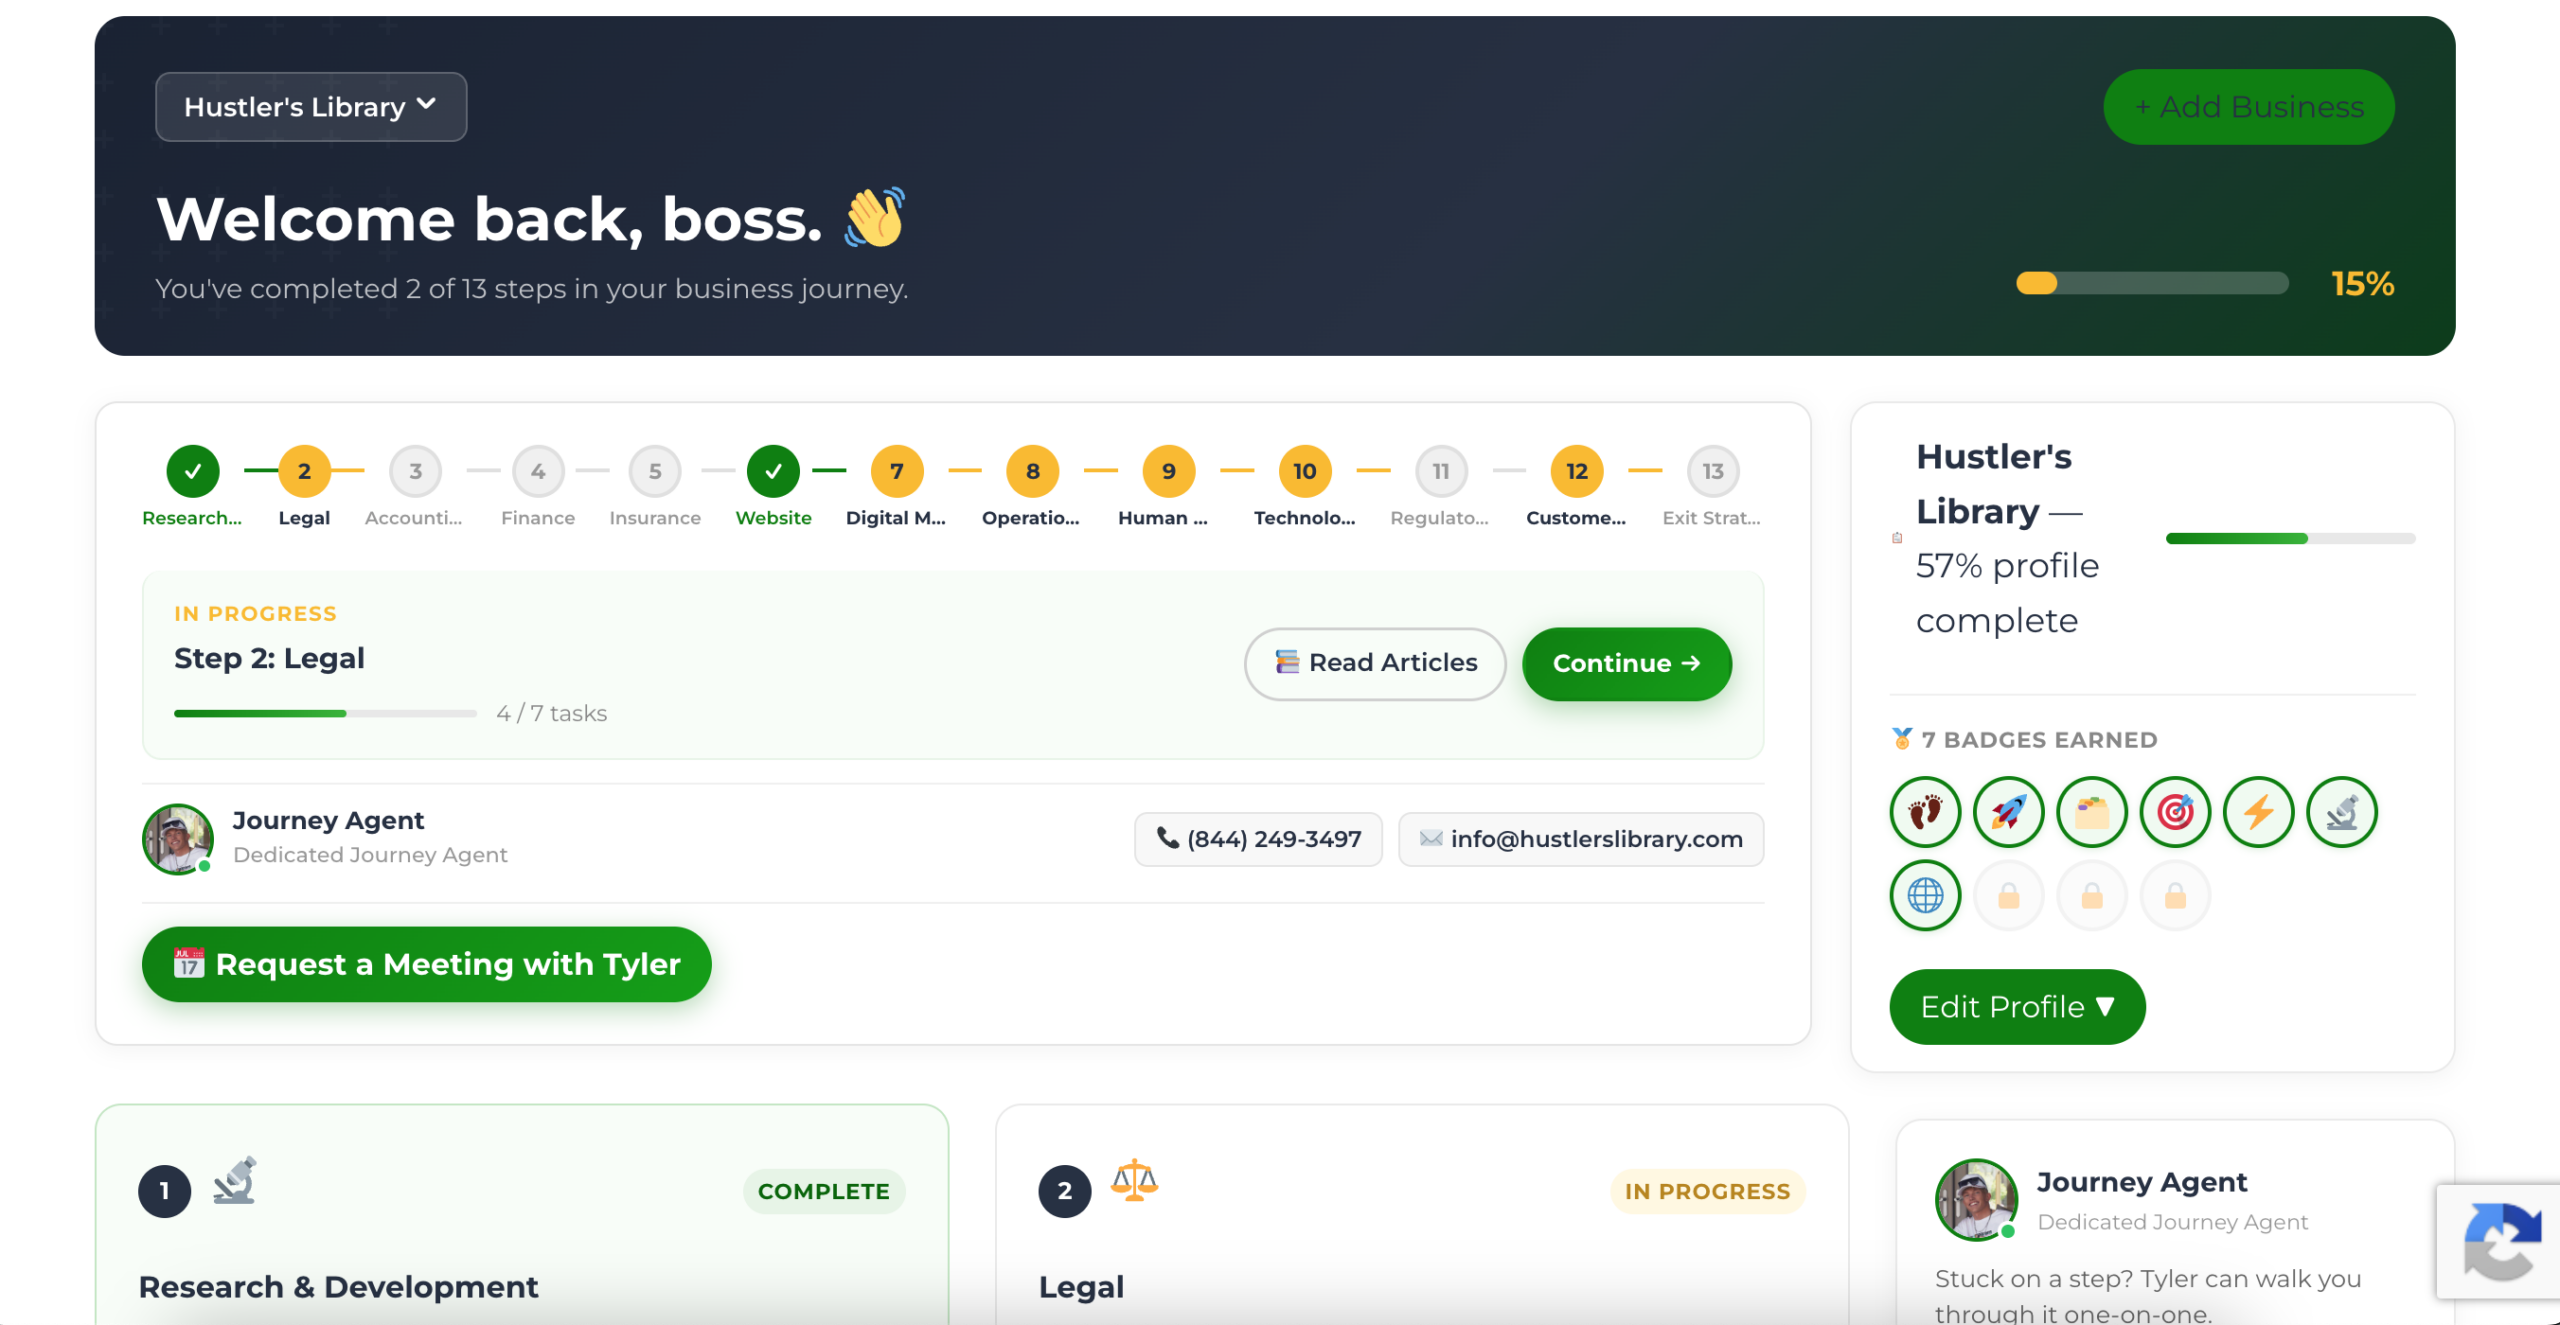
The Business Journey dashboard maps your exact position across all 13 stages. Track your progress, unlock resources for each step, and build with a framework used by thousands of founders at Hustler's Library.
No credit card required · Takes 3 minutes · Personalized to your stage