One day your phone rings. The voice on the other end says they’re interested in buying your business.
Maybe it’s a competitor. Maybe it’s a private equity group. Maybe it’s a larger company looking to expand. Whatever the case, your first instinct might be excitement or panic. The smart move is neither. The smart move is to slow down, get informed, and approach the conversation like a professional.
Acquisition offers happen more often than most small business owners expect, and many owners are completely unprepared when one lands in their lap. This guide will walk you through exactly what to do, step by step, so you can evaluate the offer clearly, protect yourself legally, and make the decision that’s right for you and your business.
Step 1: Don’t React. Respond.
The moment you receive an acquisition offer, resist the urge to immediately accept, reject, or over-share. Deals that start with excitement and no process rarely end well for the seller.
Instead, acknowledge the interest professionally and buy yourself time. A simple response like “Thank you for reaching out. We’re open to exploring conversations. Let us review the details and we’ll follow up shortly” gives you breathing room without closing any doors.
Use that time wisely. You’ll want to do your homework on who’s approaching you, why, and what their offer actually means in real terms.
Step 2: Understand the Type of Offer You’re Receiving
Not all acquisition offers are the same. Knowing the structure matters before you negotiate anything.
Asset Purchase vs. Stock Purchase
In an asset purchase, the buyer acquires specific assets of your business, such as equipment, customer lists, contracts, and intellectual property. The legal entity (your LLC or corporation) stays with you. This is the most common structure for small business deals.
In a stock purchase, the buyer purchases ownership of the company itself, including all liabilities. This structure is more common with larger businesses and carries more risk for the buyer, which is why buyers often prefer asset deals.
Understanding which structure is being proposed will affect your tax liability, how liabilities are handled, and what you actually walk away with after closing.
All-Cash vs. Earnout
All-cash offers are cleaner. You get paid at close and you’re done. Earnout structures tie part of your payment to future business performance after the sale. Earnouts can be generous on paper but risky in practice, because you may not control the outcomes that determine whether you get paid.
Step 3: Know What Your Business Is Worth Before You Talk Numbers
Walking into an acquisition conversation without knowing your own valuation is like negotiating a car purchase without knowing its book value. You’re at an immediate disadvantage.
Most small businesses are valued using one of three methods:
- Multiples of earnings (EBITDA): Common in most industries. If your business earns $200,000 per year and businesses in your sector sell at 3x earnings, your baseline valuation is $600,000.
- Revenue multiples: More common in high-growth or tech-adjacent businesses where profitability is secondary to growth.
- Asset-based valuation: Used when a business’s primary value is in its tangible assets rather than its cash flow.
If you haven’t already, read our guide on how to prepare for a business valuation before you engage in any serious conversations with a buyer. Knowing your number gives you confidence and prevents you from leaving money on the table.
Step 4: Get a Confidentiality Agreement Signed First
Before you share anything meaningful about your business, get a Non-Disclosure Agreement (NDA) signed. This is non-negotiable.
Any serious buyer will expect it. Anyone who pushes back on signing an NDA before receiving sensitive financials is a red flag.
The NDA should cover:
- Financial statements and projections
- Customer lists and contracts
- Proprietary processes or intellectual property
- Employee information
- The existence of the deal discussions themselves
Work with a business attorney to use a proper NDA rather than a generic template. This is one area where cutting corners can cost you significantly if the deal falls through and information leaks to a competitor.
Step 5: Assemble Your Deal Team
You should not handle an acquisition alone. The buyer almost certainly has a team of advisors. You need one too.
At minimum, your deal team should include:
- A business attorney who has experience with M&A transactions. General practice attorneys are often not equipped for this. Ask specifically about their deal experience.
- A CPA or financial advisor who understands the tax implications of a sale. The structure of the deal can dramatically change what you actually net after taxes.
- A business broker or M&A advisor (optional but valuable for deals over $1M) who can help you navigate the process, counterbalance the buyer’s experience, and potentially surface competing offers.
Yes, this team costs money. But the right advisors will almost always pay for themselves by protecting your interests, identifying deal risks, and helping you maximize the final number.
Step 6: Review the Letter of Intent Carefully
If a buyer is serious, they’ll submit a Letter of Intent (LOI). This is a non-binding document (mostly) that outlines the key terms of the proposed deal: purchase price, structure, timeline, due diligence period, and exclusivity.
The LOI matters more than most sellers realize. While it’s technically non-binding on price and structure, the exclusivity clause is often binding. This means once you sign, you’re legally barred from talking to other buyers for a set period, typically 30 to 90 days. That kills your leverage.
Key things to negotiate in the LOI:
- Exclusivity window: Keep it as short as possible, or push to remove it entirely until you’re further along in due diligence.
- Price and structure: Get clarity on how much is paid at close versus through earnouts or seller financing.
- Contingencies: Understand what conditions could allow the buyer to walk away or reduce the price.
- Transition expectations: Will the buyer expect you to stay on for 6 months? 2 years? Know this upfront.
For more on how letters of intent work in deal contexts, see our guide on protecting your business in high-stakes deals.
Step 7: Prepare for Due Diligence
Once an LOI is signed, the buyer will conduct due diligence, meaning they’ll dig deep into every corner of your business to verify what you’ve represented. This process can take weeks or months and is often where deals fall apart or prices get renegotiated.
Common due diligence requests include:
- 3 to 5 years of financial statements and tax returns
- Current and past customer contracts
- Employee agreements and compensation records
- Intellectual property documentation
- Legal filings, pending litigation, and regulatory compliance records
- Lease agreements and real property information
- Vendor and supplier contracts
The best thing you can do before due diligence begins is to clean up your records proactively. Disorganized or missing documentation signals risk to a buyer and invites price reductions. Businesses that are well-documented and organized command stronger valuations and faster closes.
This is also a good time to use tools like the SBA’s guide to selling a business to make sure you’ve covered all the legal and operational bases before handing over documents.
Step 8: Think Through the Non-Financial Factors
Price is not the only thing that matters in an acquisition. Smart sellers think carefully about:
- What happens to your employees? Will they be retained? For how long?
- What happens to your brand? Will the name survive or be absorbed?
- What role will you play post-close? Are you ready to report to someone else, potentially for the first time in years?
- What are your personal goals? Is this an exit for retirement? Capital for your next venture? Or are you being pushed out by circumstances?
These questions matter because a great price with terrible terms can leave you miserable. And a good deal with aligned values and a clean exit can set you up for the next chapter of your life.
For context on the bigger picture of building something worth acquiring, our post on managing post-acquisition integration is worth a read from the buyer’s perspective to understand what they’re thinking about when they approach you.
Step 9: Know That You Can Walk Away
One of the most important things to understand in any acquisition process is that you have the right to walk away at any point before a final agreement is signed.
Sellers who feel pressured to close often regret the deal later. Buyers know this and sometimes use artificial urgency to close before you’ve done your full diligence.
If something doesn’t feel right, it probably isn’t. Trust your gut, consult your advisors, and never let deal fatigue push you into accepting terms you’re not comfortable with.
The Bottom Line
Receiving an acquisition offer for your business is a big moment. It’s a validation of years of work. But it’s also a complex transaction with real consequences if handled poorly.
The owners who come out ahead are the ones who slow down, get educated, build a strong team, and negotiate from a position of clarity rather than emotion. Whether you ultimately sell or decide to keep building, going through this process will teach you more about the true value of what you’ve built than almost anything else.
If you want to keep learning how to run and grow your business smarter, join the Hustler’s Library community for free at hustlerslibrary.com/join-free/ and get access to guides, tools, and insights built for real business owners.
Ready to Know Where You Stand?
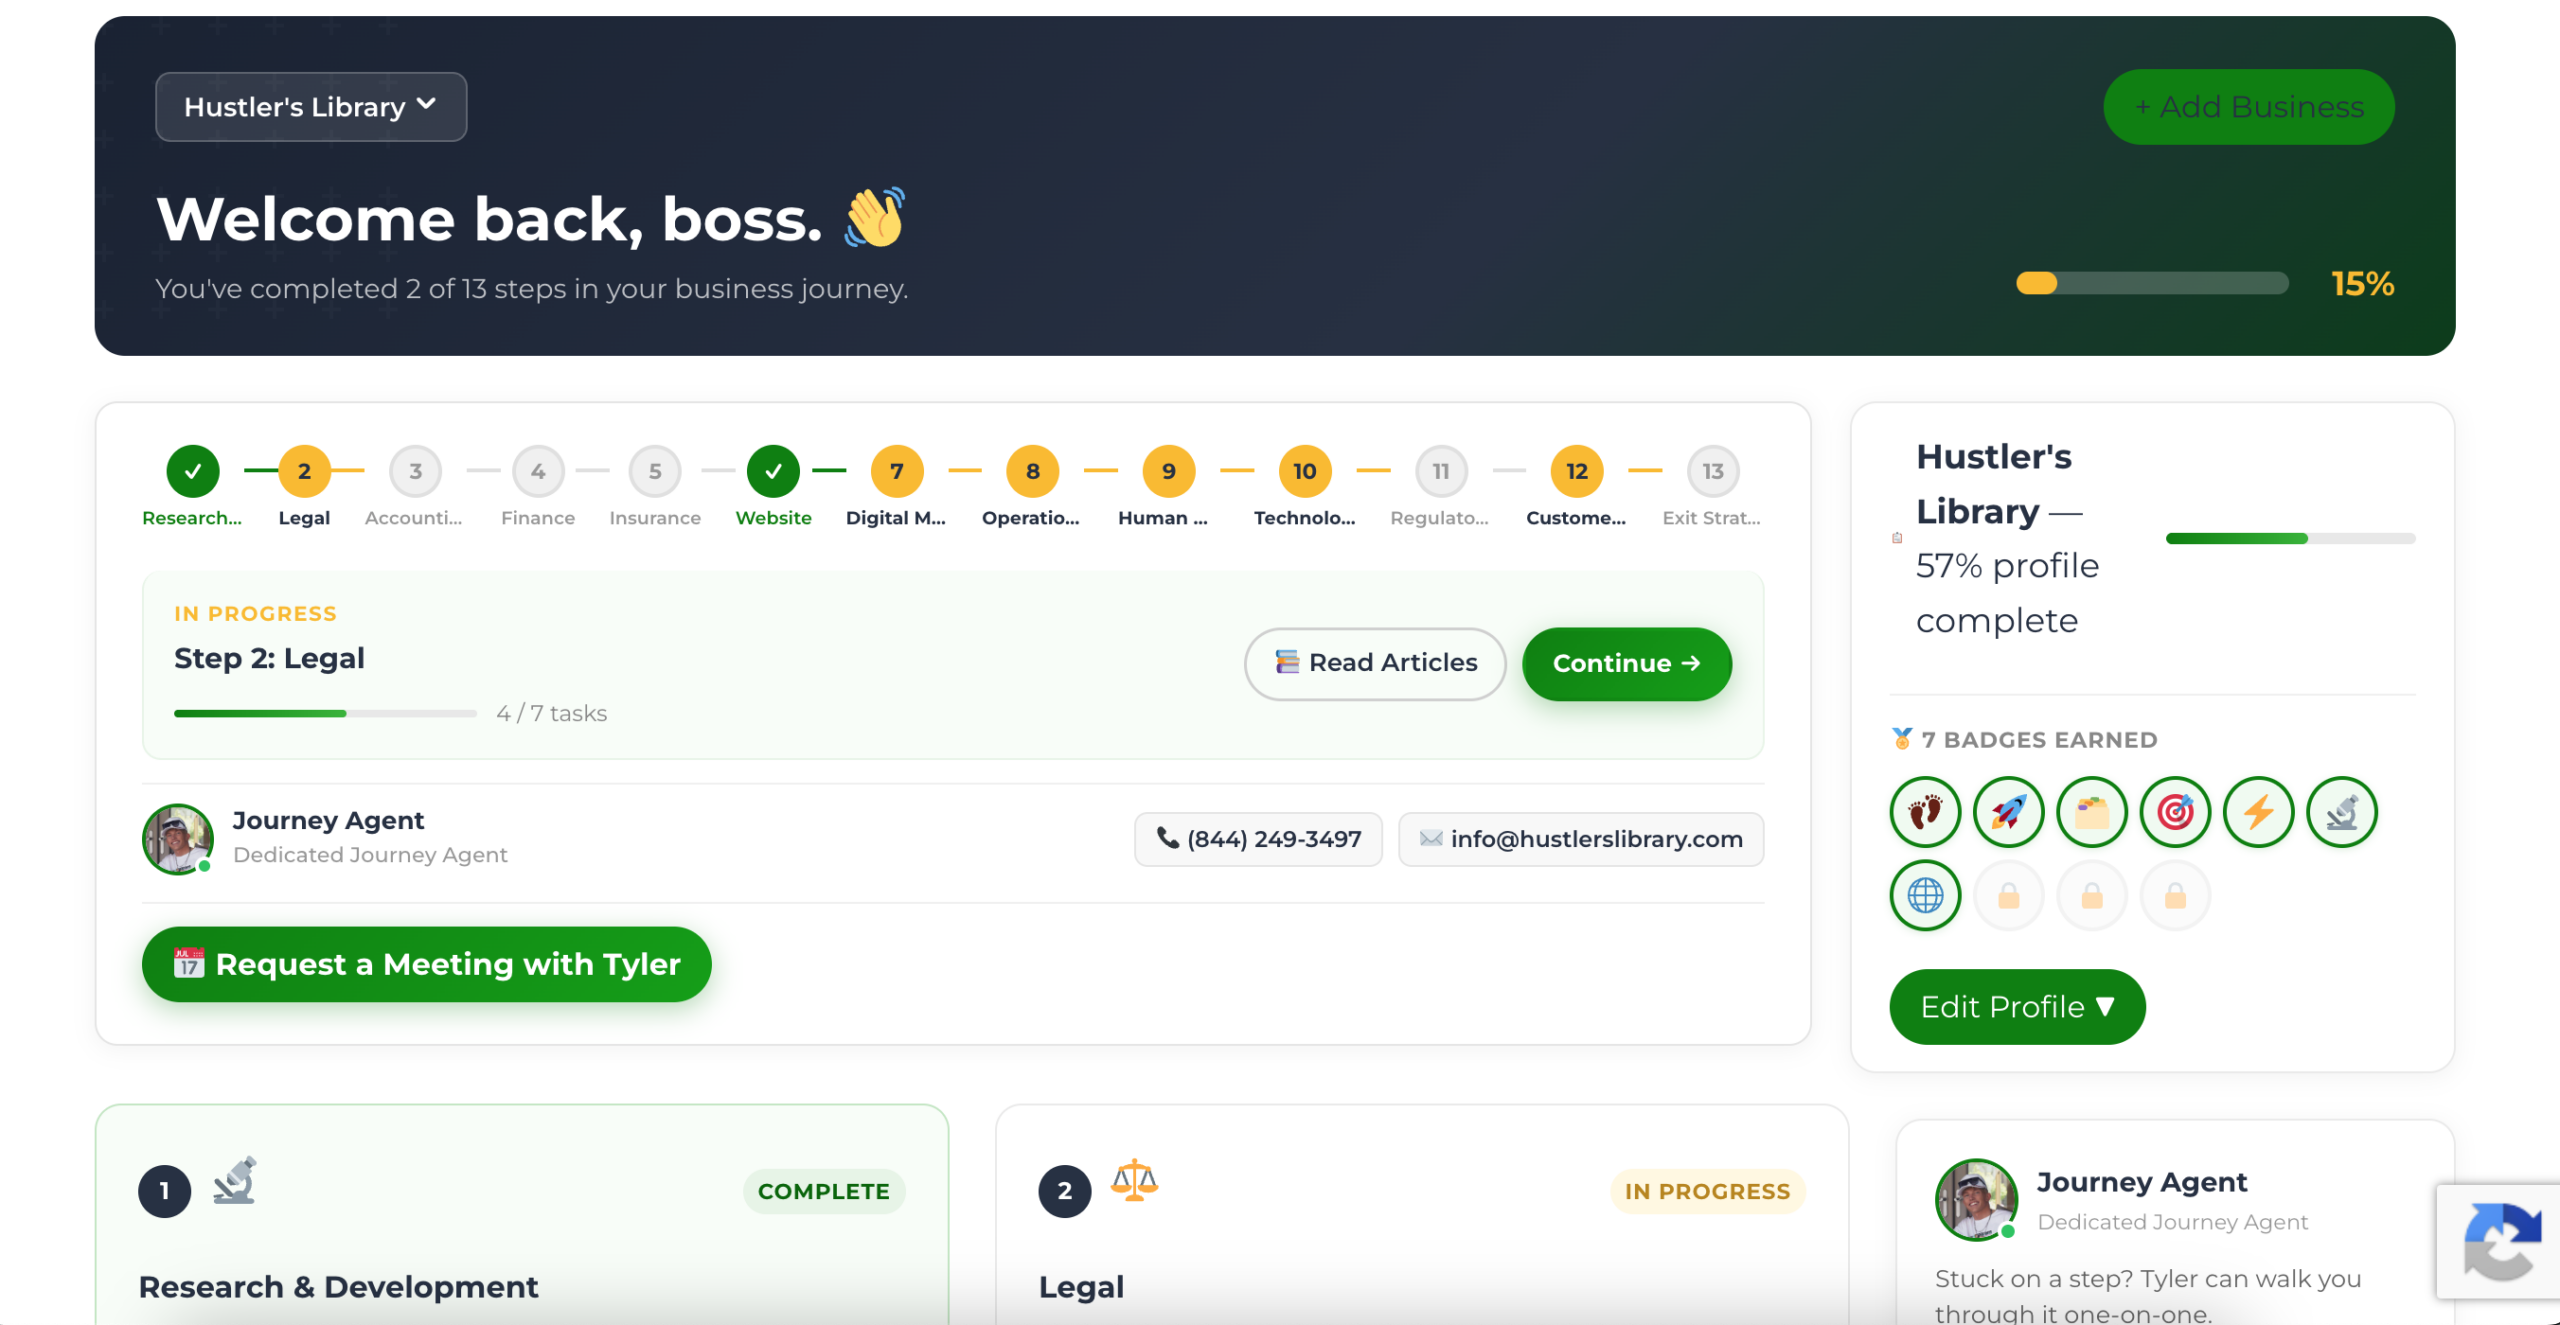
The Business Journey dashboard maps your exact position across all 13 stages. Track your progress, unlock resources for each step, and build with a framework used by thousands of founders at Hustler's Library.
No credit card required · Takes 3 minutes · Personalized to your stage