One of the most common questions new entrepreneurs ask about business credit is: how long does this actually take? The honest answer is longer than most people want to hear. Building a fundable business credit profile is a process measured in months and years, not days. But if you understand the timeline and work the steps consistently, you can get there faster than you think.
This guide breaks down the realistic month-by-month roadmap for building business credit from zero.
Month 1-2: Laying the Foundation
Nothing happens on the credit side until your business actually exists as a legal, separate entity. During the first two months, your focus is infrastructure:
- Form your LLC or corporation. A sole proprietorship does not give you a separate business credit profile. You need a legal entity.
- Get your EIN (Employer Identification Number). This is your business tax ID from the IRS. It is free and takes minutes online. Think of it as your business’s Social Security number.
- Open a dedicated business checking account. Your business needs its own bank account, separate from your personal finances. Commingling is the fastest way to undermine your business credit before it starts.
- Get your DUNS number. Dun and Bradstreet (D&B) assigns every business a unique nine-digit identifier. You need one before D&B can track your payment history and generate a Paydex score. Request it free at the D&B website.
- Set up a business phone number and address. These should match across all your registrations. Consistency in your business information matters when bureaus verify your file.
This stage feels slow because you are not doing anything credit-related yet. But skipping these steps causes problems later. A business without a DUNS number, proper legal structure, or separate bank account will hit walls the moment it tries to open trade accounts.
Month 3-5: First Trade Accounts and Payment Experiences
Now the actual credit building begins. Your goal in this window is to open 3 to 5 vendor accounts that report payment history to D&B, Experian Business, or Equifax Business.
These are called Net-30 accounts: you purchase something, receive an invoice, and pay it within 30 days. When vendors report those payments to the credit bureaus, you accumulate payment experiences. That is the raw data your business credit scores are built from.
Focus on vendors that explicitly advertise bureau reporting. Common starter vendors include office supply companies, packaging suppliers, and business service providers. Make real purchases, pay early (ideally 5 to 10 days before the due date), and let the reporting cycle do its work. For a curated list, check out our guide on what Net-30 is and how it builds business credit.
During months 3 to 5, you are building the foundation. Your Paydex score may not exist yet because D&B requires at least three reported payment experiences before generating one.
Month 6-9: Your Paydex Score Appears
If you have been consistent with early payments and have three or more payment experiences on file, your Paydex score should appear somewhere in this window. An 80 means you paid on time. A 90 or higher means you paid early. Aim for 80 at minimum; 90+ is where lenders start to take notice.
This is also the window to pursue your first secured business credit card. Unlike unsecured cards, secured cards require a deposit but do not typically require strong business credit history. They report to business credit bureaus and help diversify your credit profile beyond trade lines.
Keep paying everything early. Every positive payment experience builds toward the next milestone.
Month 10-18: Unsecured Cards and Small Credit Lines
With 6 to 12 months of solid payment history and a Paydex score above 75 or 80, you start becoming eligible for unsecured business credit cards and small revolving credit lines. These are issued based on your business credit profile, not (or at least not solely) your personal credit.
At this stage, your business credit file should show:
- 5 or more payment experiences across multiple vendors
- A Paydex score of 80+
- A clean payment history with no lates
- An Experian Intelliscore or Equifax Business Credit Risk score (if those bureaus have enough data)
Credit limits at this stage are typically modest: a 00 to ,000 unsecured card, or a small revolving line. That is fine. You are still building history. Use the credit, keep utilization below 30%, and pay it off early or on time every month.
Month 18-36: Meaningful Limits and Loan Eligibility
This is where the investment in the earlier stages starts paying off. With 18+ months of consistent, positive payment history across multiple trade lines and credit accounts, you become eligible for:
- Business credit cards with limits of 0,000 to 0,000+
- Business lines of credit from banks and credit unions
- SBA loan programs (which have credit score thresholds, but also consider time in business and revenue)
- Equipment financing and invoice factoring with better terms
The businesses that reach this stage in 18 months rather than 36 months are the ones that stacked more vendors early, paid everything early, and monitored their credit files for errors. The ones who end up at the 36-month mark are typically the ones who started late, had gaps in their reporting, or had a payment miss somewhere along the way. See our detailed breakdown on what a Paydex score is and how to improve it to understand the scoring mechanics behind this stage.
Factors That Speed Up the Process
Several things can compress this timeline:
- More vendors reporting: Instead of three vendors, open six or eight. More data points means a more robust file, faster.
- Paying early consistently: Early payments push your Paydex above 80 and signal financial health to lenders.
- Higher transaction volume: D&B uses a dollar-weighted average. Larger payments carry more weight. If you can legitimately purchase more from your vendors, the credit file grows faster.
- Monitoring and disputing errors early: Business credit files have errors more often than people expect. Check them quarterly and dispute anything inaccurate immediately.
Factors That Slow It Down
Avoid these common mistakes that push your timeline out:
- Missed payments: Even one missed payment can tank your Paydex and require months of recovery.
- Too few vendors: Three vendors is the floor, not the goal. Thin files look risky to lenders.
- Not monitoring your credit: Errors go unchallenged, accounts get mixed up with similar business names, and your score suffers without you knowing.
- Treating business credit like personal credit: They are separate systems. Your excellent personal FICO does not automatically translate to strong business credit.
The Honest Answer
A fundable business credit profile, meaning one that can support meaningful loan applications and high-limit credit products, takes 18 to 24 months to build properly. That is the real number when you do everything right. If you make mistakes or start late on some steps, plan for 24 to 36 months.
That might sound discouraging. It should not be. Most of your competitors are not building business credit at all. The entrepreneurs who start the process now and stay consistent are the ones who have access to capital when an opportunity or emergency arrives.
For a broader overview of the full credit-building process, the SBA’s guide to building business credit covers the foundational steps alongside loan eligibility requirements. And for a deeper look at the scoring itself, see our guide on how to build business credit from scratch.
Ready to Build Smarter?
Get access to our full library of business guides, tools, and resources.
Tools like Credit Karma can help you monitor your business credit profile as it builds.
Ready to Know Where You Stand?
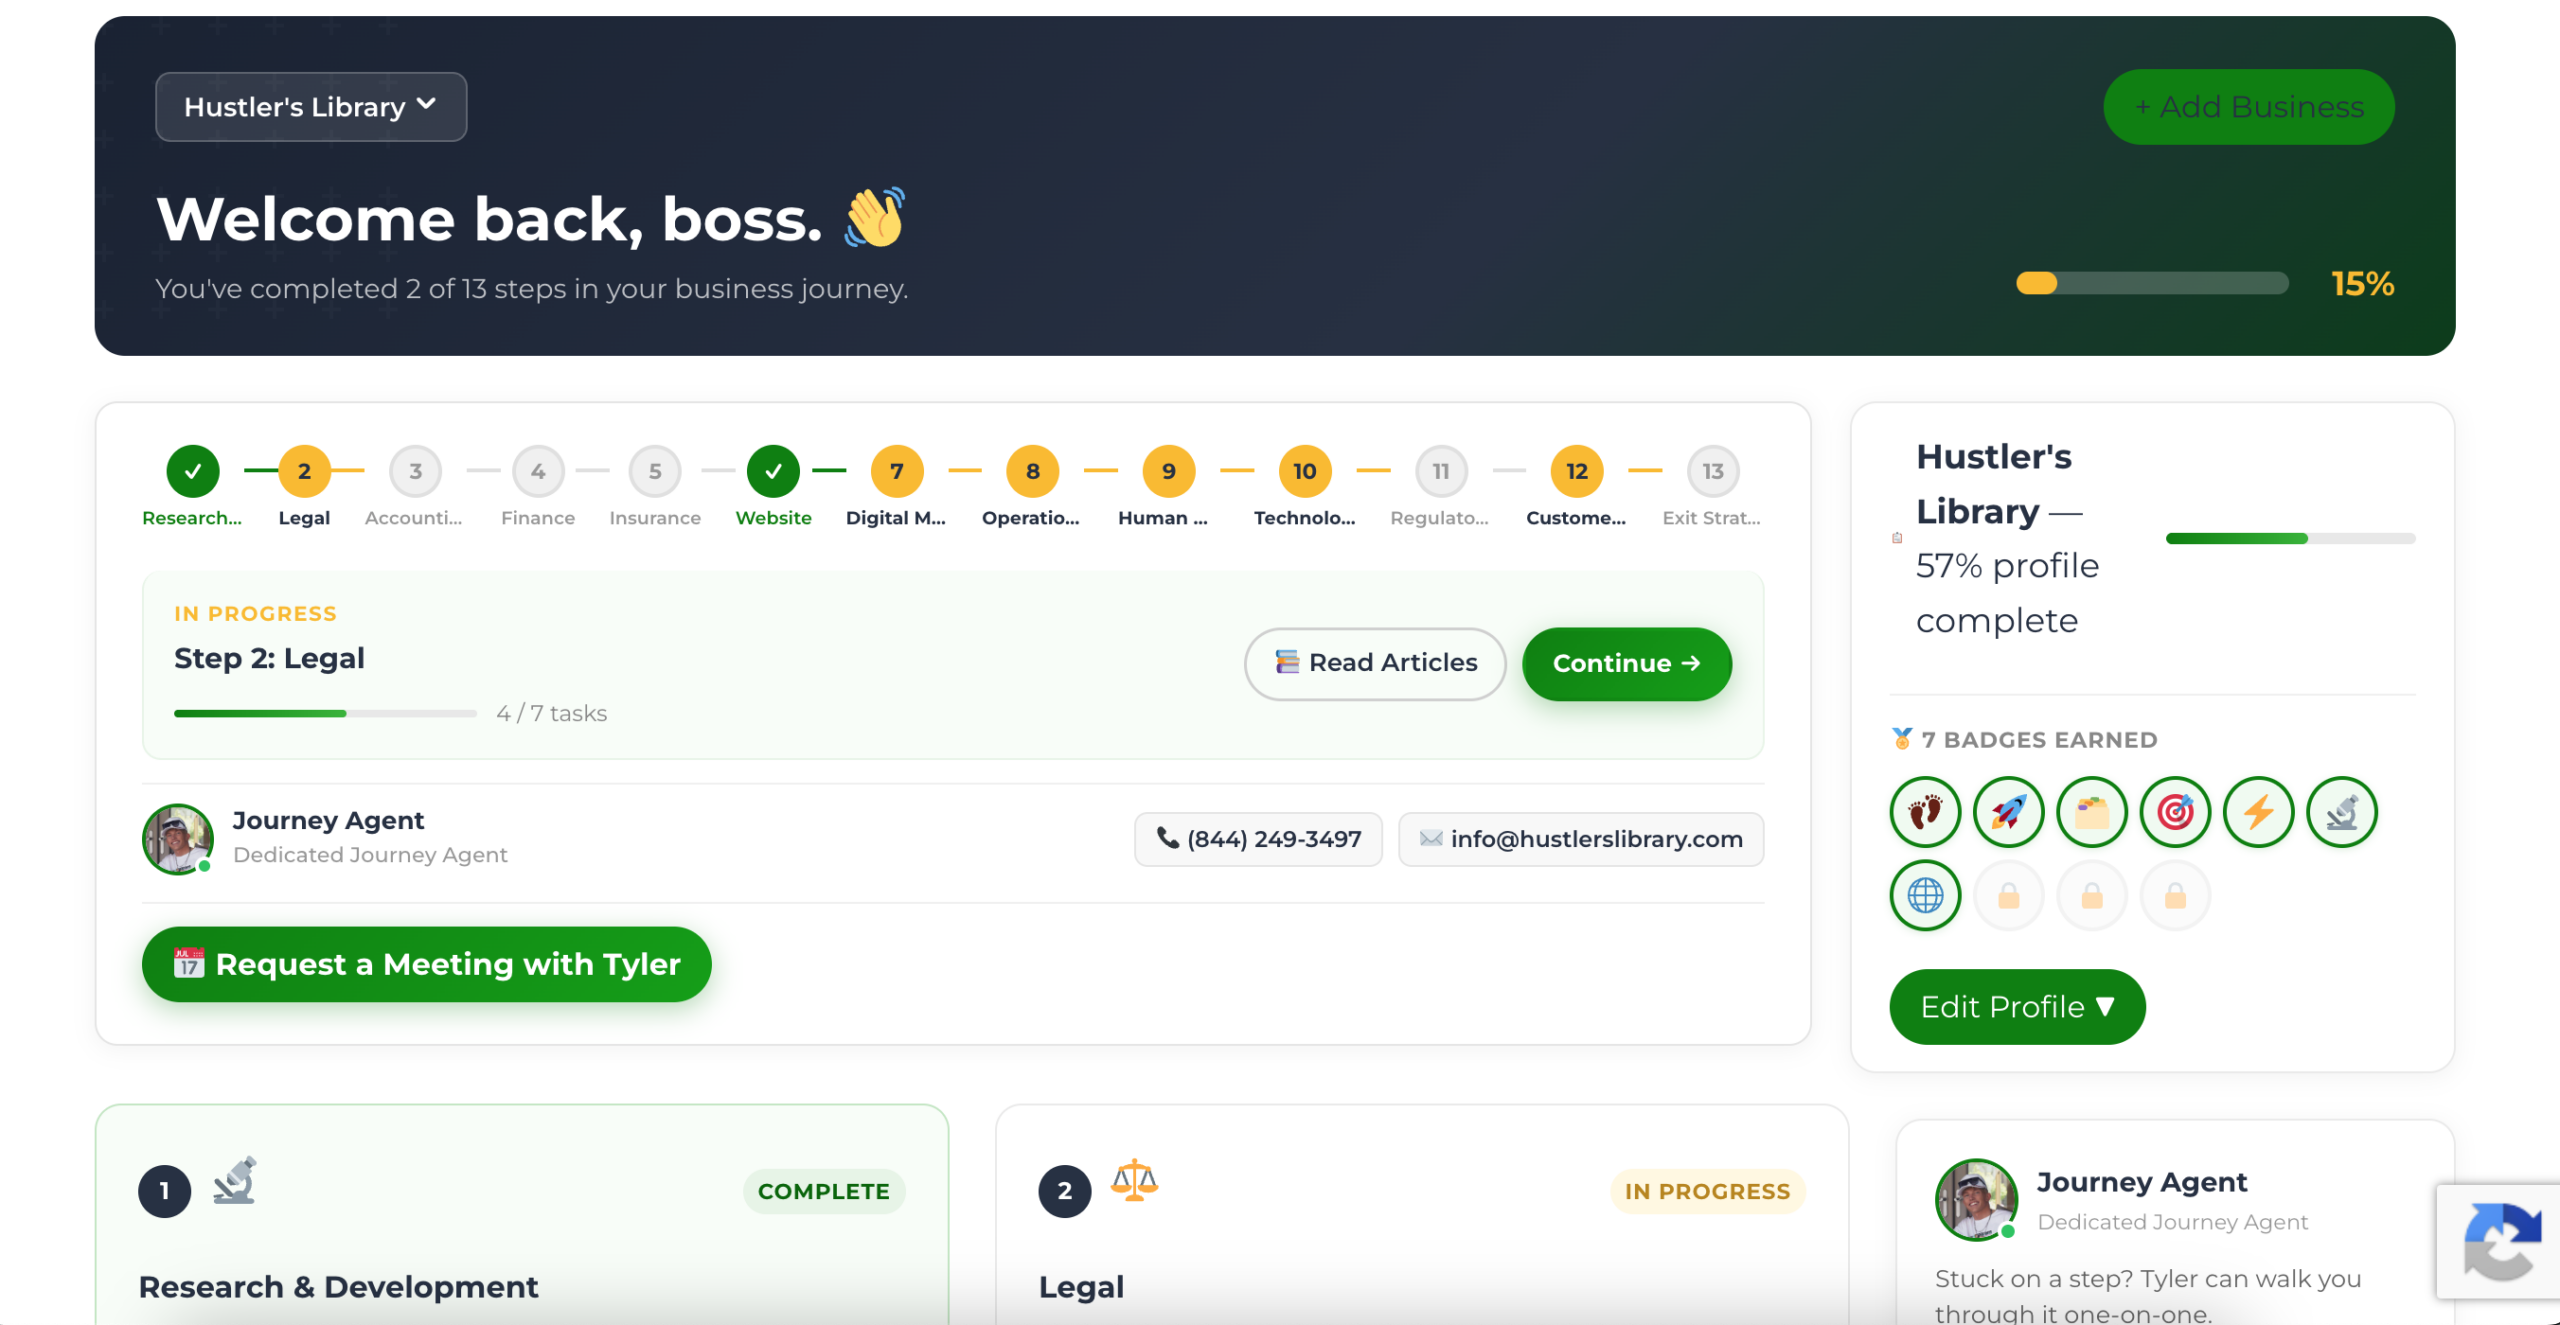
The Business Journey dashboard maps your exact position across all 13 stages. Track your progress, unlock resources for each step, and build with a framework used by thousands of founders at Hustler's Library.
No credit card required · Takes 3 minutes · Personalized to your stage