If you’ve ever been turned down for a small business loan despite running a healthy operation, the problem likely wasn’t your revenue — it was your credit file. On Tuesday, September 29, 2026, Experian announced the launch of Cashflow Attributes for commercial lenders, a new product that transforms business bank transaction data into more than 500 scoring attributes that lenders can now plug directly into their underwriting models.
In short: your actual cash flow can now speak for you, even when your commercial credit file doesn’t tell the whole story.
What This Actually Means
For years, small business lending has relied heavily on commercial credit scores, which can be thin, slow to build, or simply nonexistent for newer businesses. Startups, sole proprietors, and businesses under five years old often hit a wall not because their finances are bad, but because the data lenders use to judge them doesn’t fully capture what’s happening in their bank accounts.
Experian’s new Cashflow Attributes close that gap. The product converts raw business banking data (deposits, withdrawals, transaction frequency, recurring payments, cash flow seasonality) into a structured set of signals lenders can use alongside traditional credit data. The implication is significant: if your business has strong, consistent cash flow, you may now have a real shot at credit that was previously out of reach.
This matters especially for small businesses already facing AI-driven tightening in bank lending. Experian is effectively creating a counter-signal: banks can use AI to screen smarter, but now cash flow data can advocate for borrowers that older models would have missed.
The Numbers Behind It
Experian’s internal analysis on the commercial side shows Cashflow Attributes provide up to a 24% lift in predictive performance for businesses with thin credit files. That’s not a marginal improvement — it’s the difference between a lender saying no to a creditworthy business and saying yes.
On the consumer side, where Experian has been running a similar approach through Cashflow Attributes and their Cashflow Score for years, lenders have seen up to 30% more approvals without adjusting risk tolerance. Millions of consumers have already connected their bank accounts to Experian tools like Boost to benefit from this kind of data. Now the same logic extends to businesses.
The solution uses 500+ attributes derived from business bank transaction data, covering patterns that traditional credit scoring completely ignores: how often the business gets paid, how consistently it covers recurring expenses, whether revenue is growing or volatile month over month.
The Hustler’s Library Take
Here’s the angle most business coverage will miss: this announcement is bullish for scrappy operators, not just for lenders.
The businesses most harmed by traditional credit underwriting have always been the ones that are actually running well — steady revenue, consistent deposits, manageable overhead — but just haven’t been around long enough to build a thick commercial credit file. A two-year-old restaurant doing $40K a month in clean deposits used to face the same rejection as a business with genuine cash flow problems. That’s the gap Cashflow Attributes targets.
The catch: to benefit, you need to bank transparently. Your transaction data has to tell a coherent story. Businesses that mix personal and business expenses, run cash-heavy operations without clean records, or cycle through accounts will not benefit from this shift — and may actually look worse under cash flow scrutiny. Knowing your cash flow numbers cold isn’t just good practice anymore; it’s becoming your credit profile.
What You Should Do
1. Connect your business bank account to your Experian business profile. Experian’s commercial Cashflow Attributes are powered by business bank transaction data. If your lender uses Experian’s underwriting tools and your data isn’t connected, you’re leaving 500 new signals on the table. Ask your bank or lending platform whether they use Experian Cashflow data in their commercial underwriting, and find out how to authorize that data share.
2. Clean up your transaction history now, before you apply. Lenders using Cashflow Attributes will look at patterns across months of data: deposit consistency, payroll regularity, expense control. If you have mixed fixed and variable costs running through a messy account, that noise will dilute your signal. Separate accounts, consistent payment schedules, and on-time recurring expenses will all read positively. Start building that record today, not the week before you apply.
3. Know your net cash position, not just your revenue. Cashflow Attributes analyze inflows and outflows together — what comes in, what goes out, and what’s left. A business with $100K in revenue and $98K in outflows looks like a risk, even if the top-line is impressive. Tighten your net profit margin before seeking credit, and make sure your bank statement reflects a business that can service debt.
Source: Experian via BusinessWire | Authority reference: Experian Insights Blog
Want more like this every morning? Join Hustler’s Library free and get the news that actually moves your business, delivered to your inbox.
Ready to Know Where You Stand?
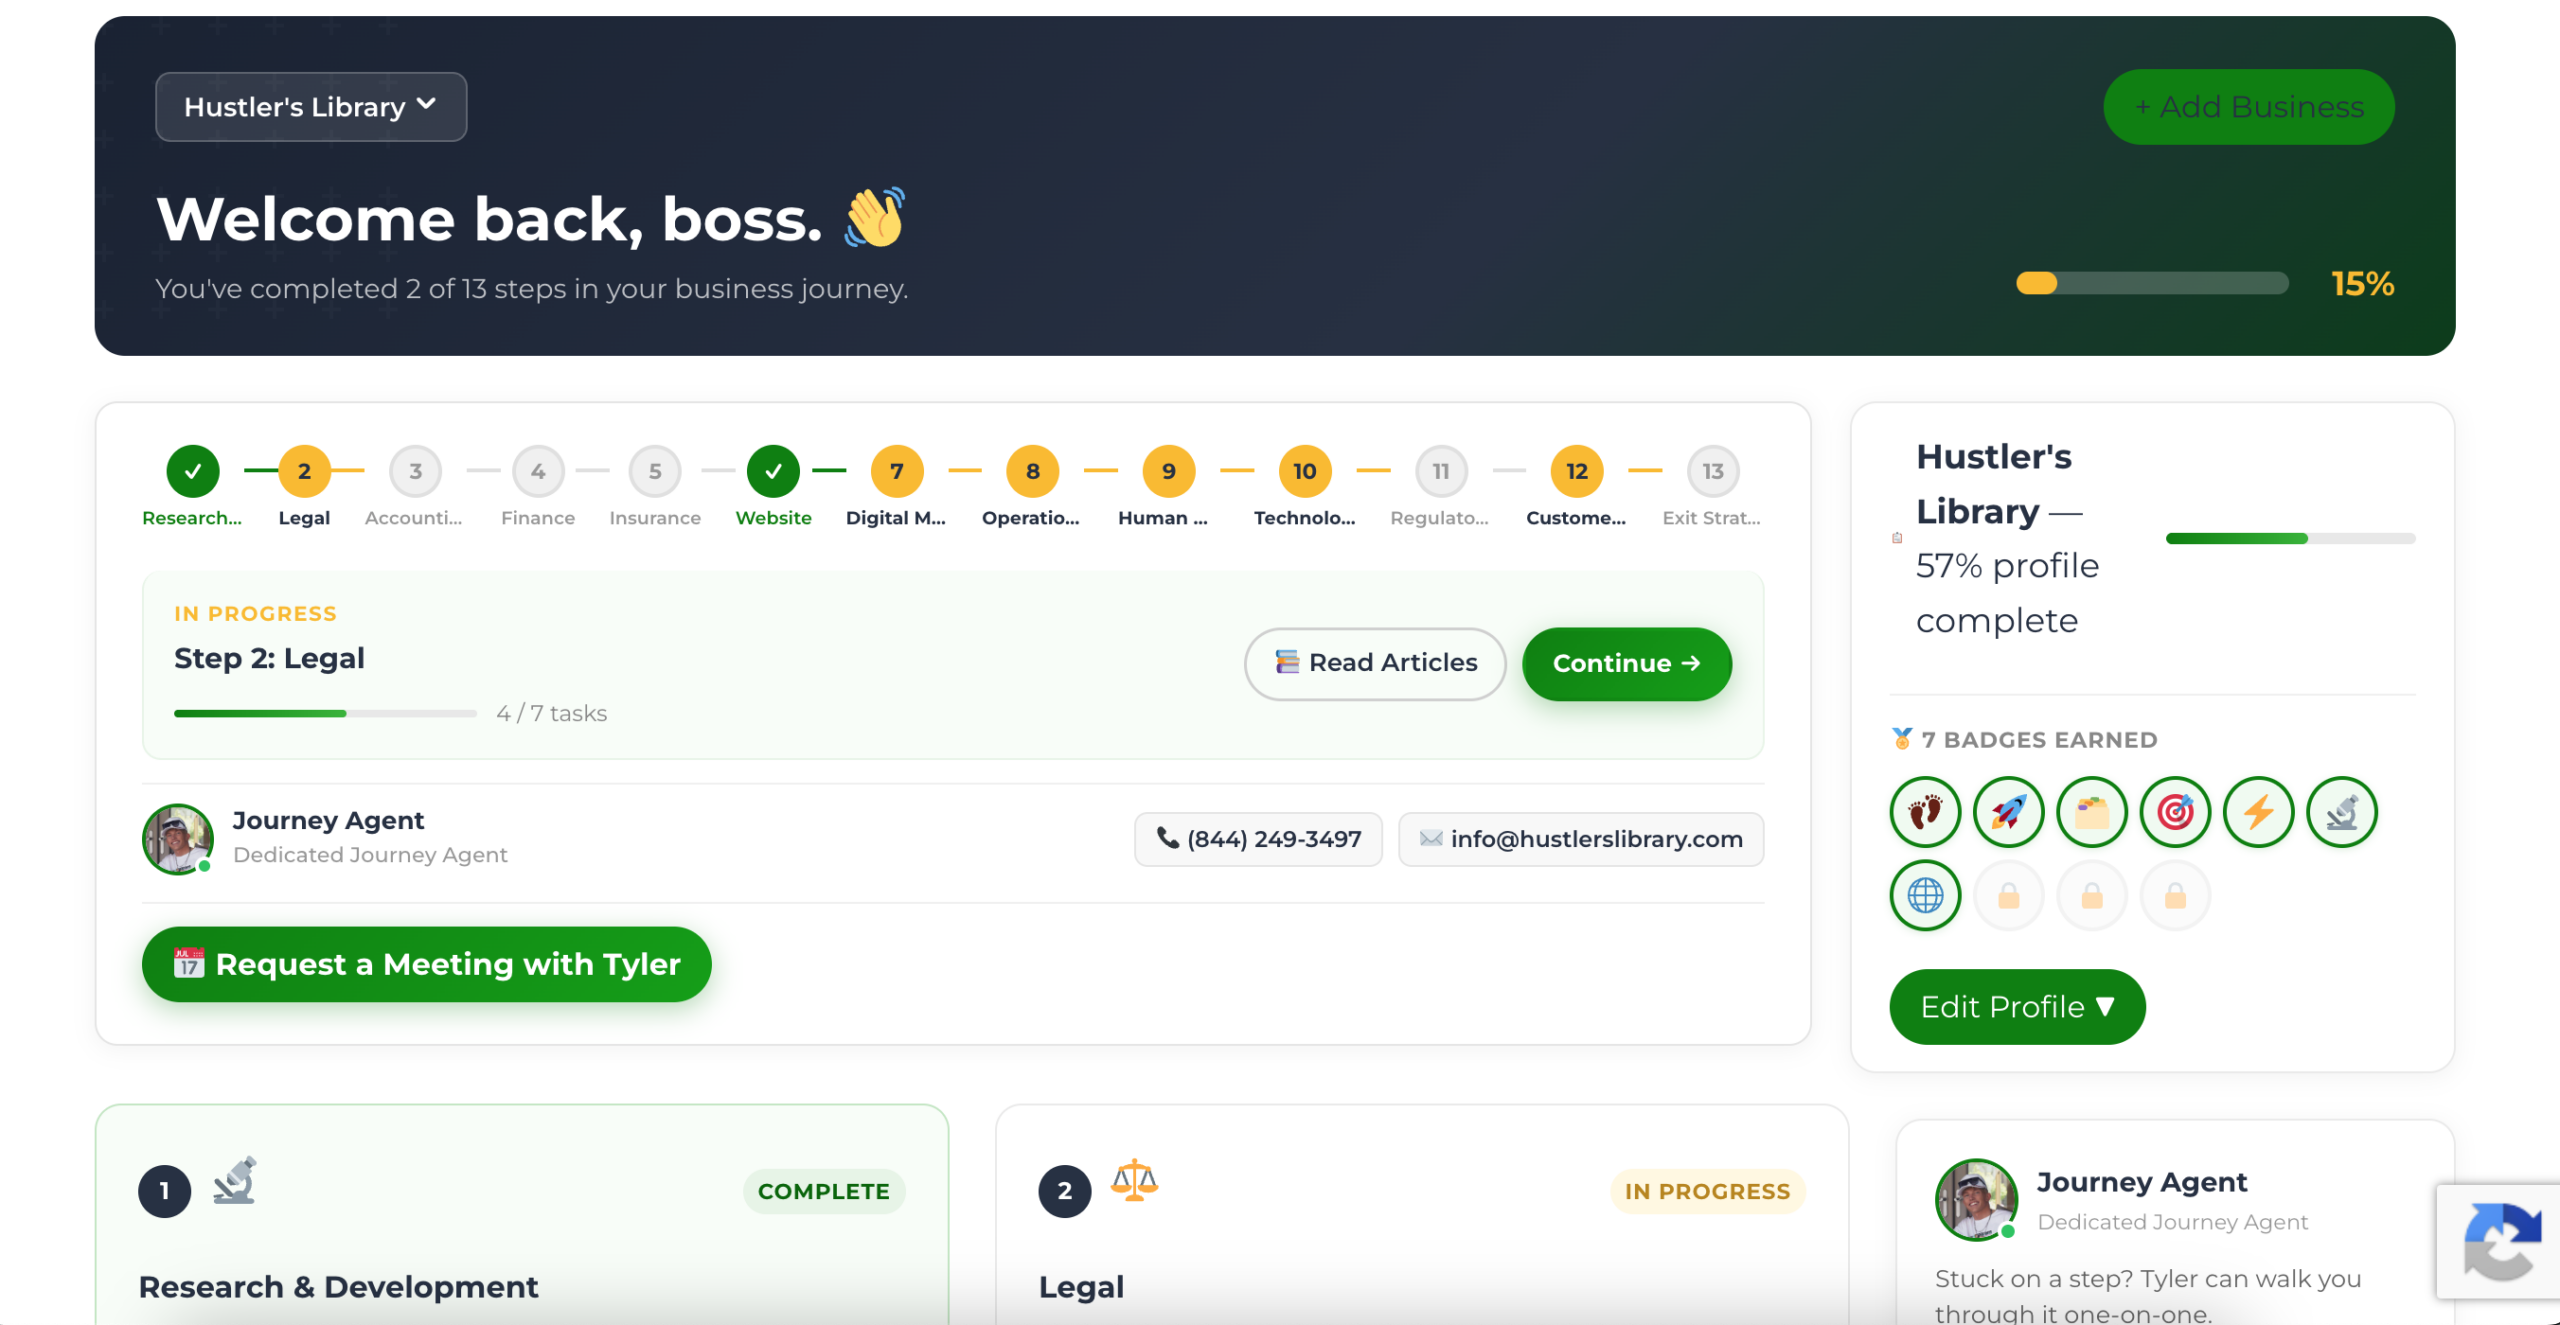
The Business Journey dashboard maps your exact position across all 13 stages. Track your progress, unlock resources for each step, and build with a framework used by thousands of founders at Hustler's Library.
No credit card required · Takes 3 minutes · Personalized to your stage