Most small business owners think of financing as something you get from a bank. You fill out an application, wait weeks for a decision, and hope the numbers work out. But there is another source of financing hiding in plain sight, one that does not require a credit check, a banker, or a pile of paperwork. It comes from your vendors.
Vendor financing, sometimes called supplier financing or trade financing, is when the businesses you buy from agree to let you pay later, pay in installments, or structure your purchases in a way that eases the pressure on your cash. It is one of the most practical and underused tools in the small business toolkit, and this guide will show you exactly how to use it.
What Vendor Financing Actually Is
At its core, vendor financing is a credit arrangement between you and your supplier. Instead of paying upfront or on standard net-30 terms, your vendor agrees to let you pay over time, often interest-free or at low rates, as a way to win or keep your business.
This can show up in several forms. A supplier might offer extended payment terms, letting you pay in 60 or 90 days instead of 30. A piece of equipment seller might let you pay in monthly installments. A wholesale distributor might give you a consignment arrangement where you pay only for what you sell. An industry software company might defer your first few payments while you get set up.
The vendor benefits too. They close more sales, build loyalty, and often earn slightly more over time by offering terms. You benefit by holding onto your cash longer and using it to run the rest of your business.
Why It Matters More Than Most Business Owners Realize
Timing is one of the biggest financial challenges in small business. You might need to purchase inventory two months before your busy season. You might need to upgrade equipment before a major contract begins. You might land a large client and suddenly need supplies you cannot afford to front.
Vendor financing bridges that gap without adding bank debt to your balance sheet. It lets you acquire what you need now and pay from the revenue that the purchase itself helps you generate. That is a fundamentally different dynamic than borrowing money and paying it back regardless of results.
It is also worth noting that vendor financing does not always show up on your credit report, which preserves your borrowing capacity for when you actually need traditional financing. You can learn more about alternative funding strategies for small businesses here.
The Most Common Types of Vendor Financing
Extended Payment Terms
This is the most basic form. Your vendor normally expects payment in 30 days, but you negotiate 60 or 90 days instead. That extra time gives you the chance to sell your inventory or complete your project before the bill comes due. Even a 30-day extension can meaningfully improve your monthly position.
Installment Arrangements
Rather than paying a lump sum, you break the purchase into regular payments over a set period. This is common with equipment, software, and large inventory orders. The vendor accepts slightly less upfront certainty in exchange for a longer relationship with you as a customer.
Consignment Arrangements
In a consignment deal, the vendor supplies you with goods but retains ownership until you sell them. You only pay for what moves. This eliminates inventory risk almost entirely and can be especially useful for retail businesses testing new product lines.
Deferred First Payment
Some vendors, especially in the technology and software space, will let you use their product for 30 to 90 days before the first payment is due. This is essentially a trial period with built-in financing, and it is often more negotiable than it appears on the surface.
Revenue-Based Arrangements
Less common but increasingly available, especially in B2B sectors, this ties your payments to your revenues. You pay more when business is strong and less when it is slow. This type of arrangement aligns the vendor’s incentive with your success and reduces pressure during down periods.
How to Actually Ask for Vendor Financing
Most small business owners never ask because they assume the answer is no. But vendors are often far more open to creative terms than you might expect, especially if you are a consistent customer or represent meaningful volume to them.
Start by building a relationship before you need the favor. Pay on time consistently for several months. Communicate reliably. Be the kind of customer that vendors want to keep. When you do ask for terms, you are calling in goodwill rather than cold-asking a stranger.
When you make the ask, frame it around mutual benefit. Instead of saying “I need more time to pay,” try something like: “We are scaling up to handle a larger client, and extended terms would help us commit to significantly higher order volumes with you. Can we talk about net-60?” That framing gives the vendor a concrete reason to say yes.
Be specific about what you are asking for. Vague requests invite vague responses. Name the terms you want, the volume you are committing to, and the timeline. This signals that you are a serious business partner, not just looking for a handout.
If the vendor pushes back, offer something in return. A longer commitment period, a larger order, a preferred vendor status, or faster payments on smaller orders can all sweeten the deal. Negotiation is a conversation, and approaching it strategically makes a real difference in how far you get.
What to Watch Out For
Vendor financing can backfire if you are not careful. Here are the traps worth watching out for.
Hidden costs in extended terms. Some vendors price extended payment terms into their pricing without being explicit about it. If a vendor raises unit prices when you ask for net-60, do the math. The implied interest rate can be steep, and it may be cheaper to pay upfront and use a low-rate line of credit for working capital instead.
Dependency on a single vendor. When one supplier controls your terms and your supply, you are vulnerable. If they tighten terms or raise prices, you have little leverage. Vendor financing should be one piece of a diversified supply strategy, not the foundation of your entire operation.
Overextending your payment obligations. It is easy to stack up vendor credit across multiple suppliers and suddenly face a wave of payments you cannot handle at once. Track your vendor obligations as carefully as you would track bank debt.
Informal arrangements without documentation. If a vendor verbally agrees to net-60 terms, get it in writing. A quick email summary of the agreed terms is sufficient. Handshake deals can dissolve when your account rep changes jobs or the vendor gets acquired.
How Vendor Financing Fits Into Your Broader Financial Strategy
Vendor financing works best when it is part of a deliberate approach to managing your working capital. Think of it as one lever among several, alongside your operating line of credit, your receivables practices, and your expense timing.
The basic principle is simple: delay outflows and accelerate inflows wherever possible. Vendor terms let you delay outflows. Tight invoicing practices, deposits, and automated billing help you accelerate inflows. Together, they create breathing room that reduces your dependence on borrowed capital.
The Small Business Administration has solid resources on managing business finances, including how vendor relationships factor into working capital planning. It is worth reviewing if this area of your business needs more structure.
For businesses that do high volume with a small number of suppliers, it may also be worth exploring supply chain diversification alongside vendor financing. Having multiple supplier options increases your negotiating position and reduces the risk that a single vendor relationship can hold your business hostage.
The Bottom Line
Vendor financing is not glamorous. It does not come with a press release or a funding announcement. But it is real capital, and it is available to almost any business that has solid vendor relationships and the confidence to ask for what it needs.
Start by auditing your current supplier relationships. Where are you paying upfront that you could be paying net-30? Where are you on net-30 that could be net-60? Where could a consignment or installment arrangement unlock a larger purchase you have been putting off?
The businesses that grow fastest are not always the ones with the most cash. They are the ones who are most creative about how they use the cash they have, and vendor financing is one of the simplest, most effective tools for doing exactly that.
Want more strategies for running a smarter, more financially resilient business? Join Hustler’s Library for free and get access to guides, tools, and resources built for people who take their business seriously.
Ready to Know Where You Stand?
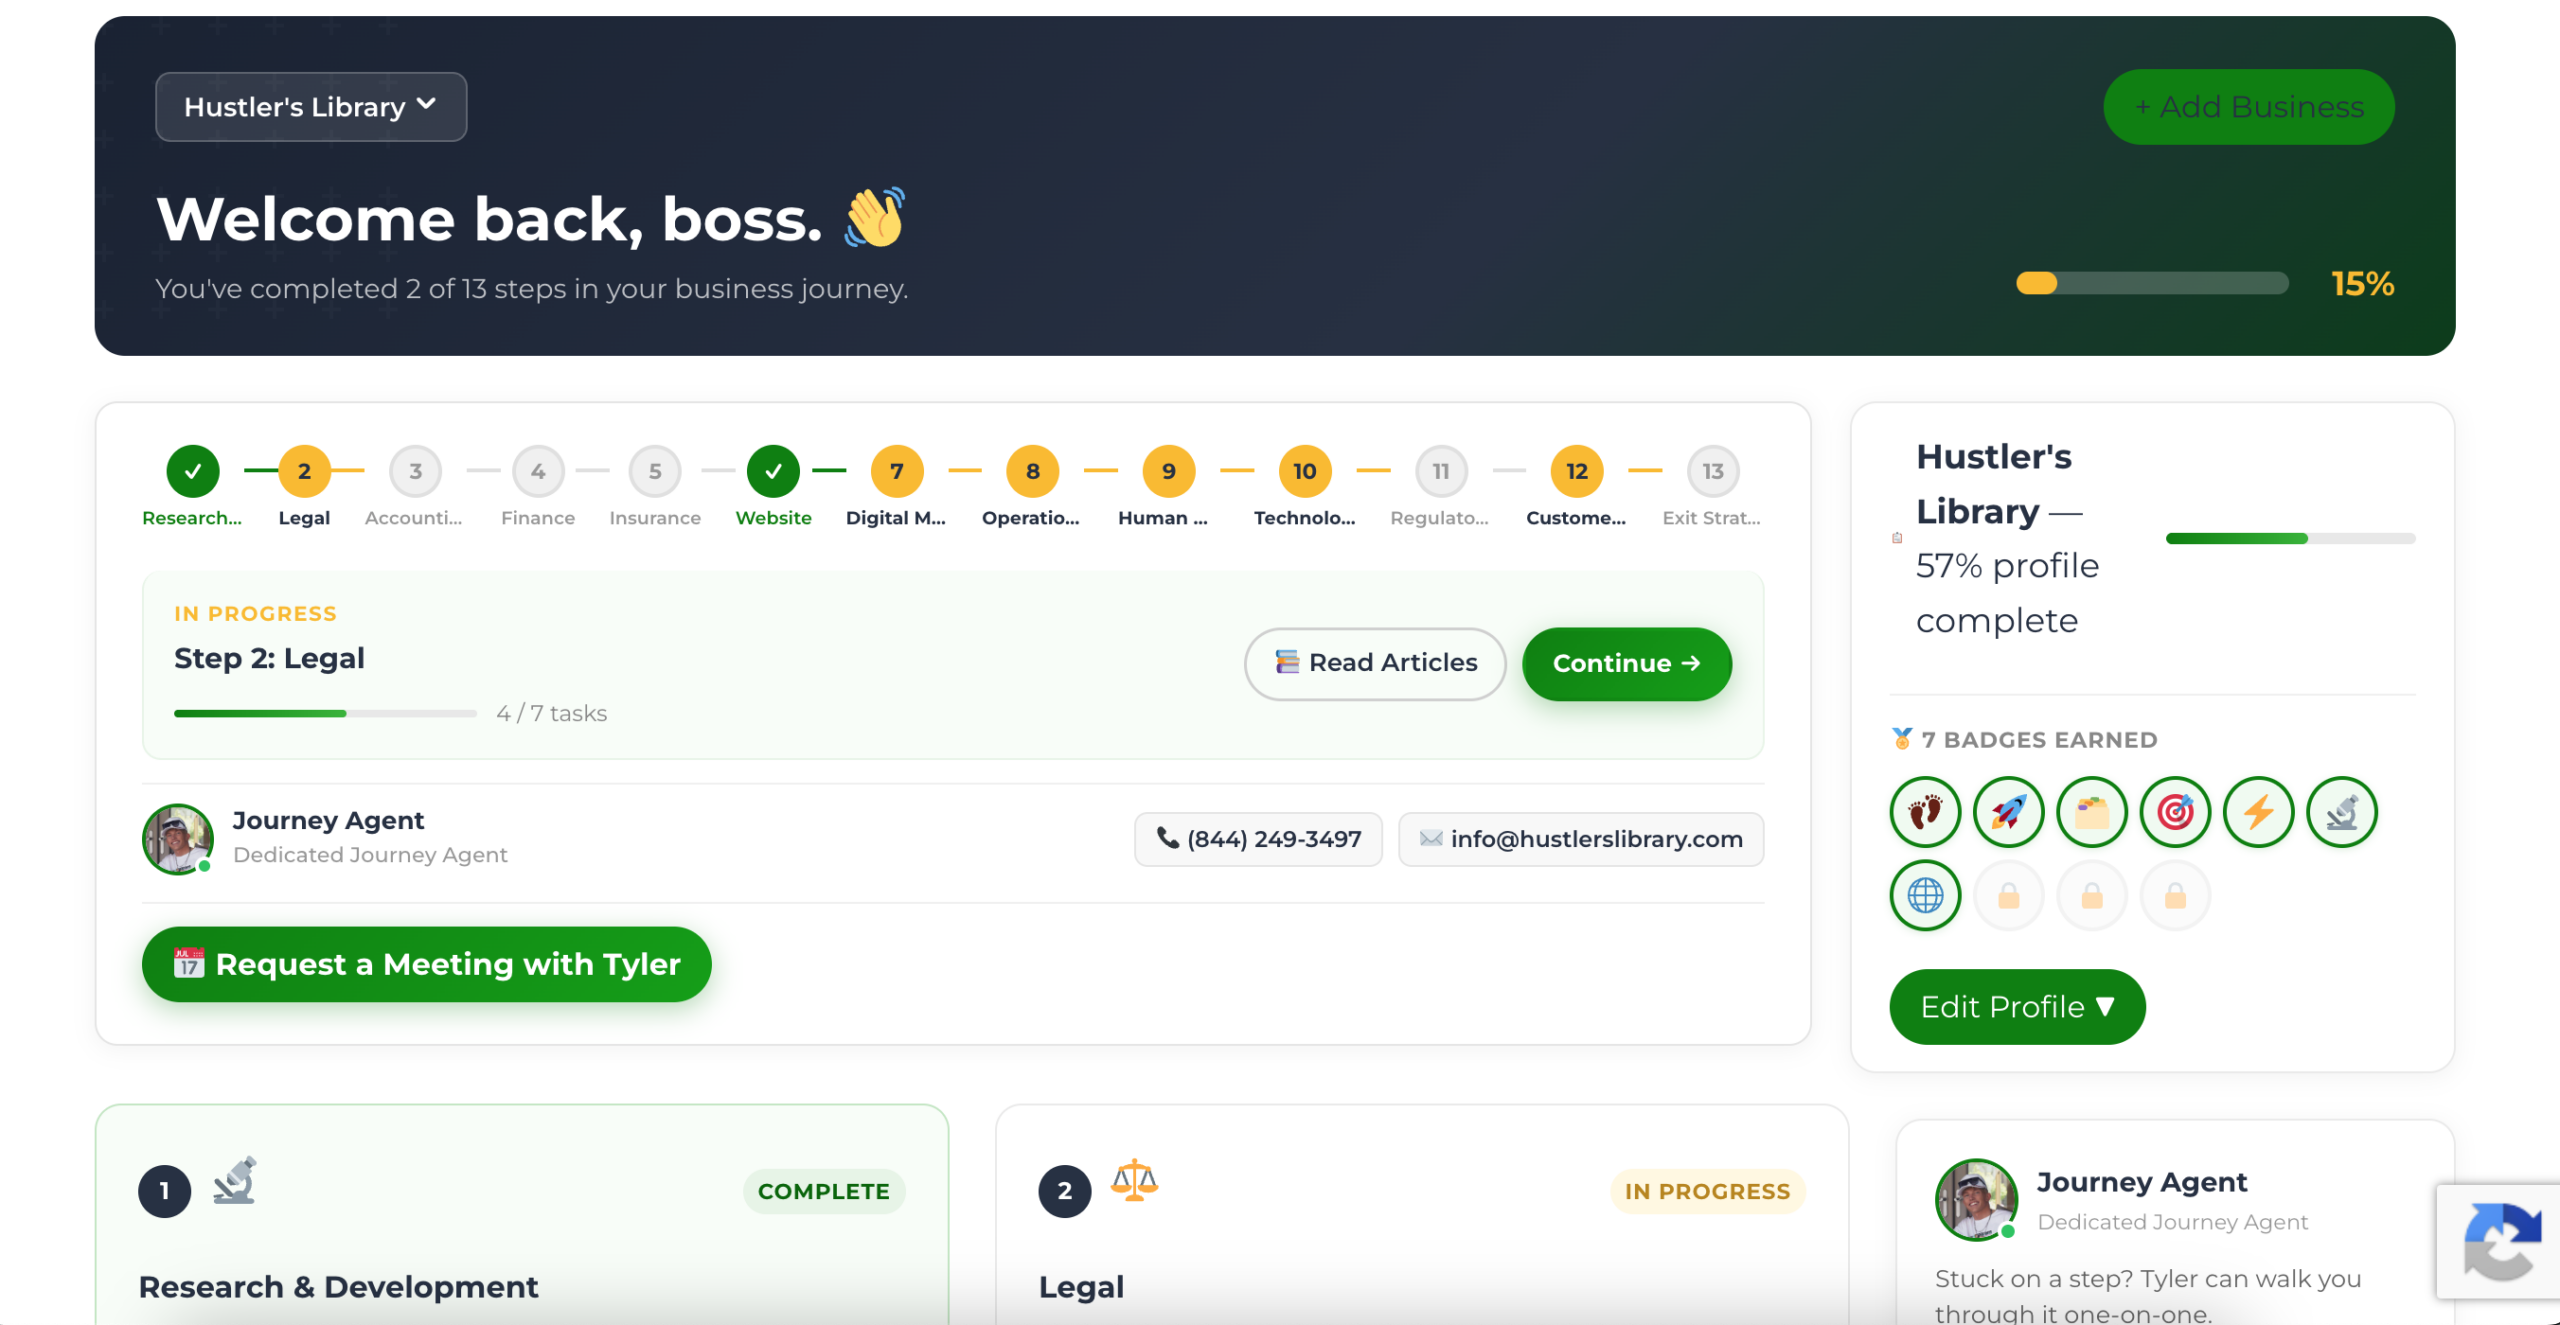
The Business Journey dashboard maps your exact position across all 13 stages. Track your progress, unlock resources for each step, and build with a framework used by thousands of founders at Hustler's Library.
No credit card required · Takes 3 minutes · Personalized to your stage