Most small business owners are great at what they do. They know their craft, their customers, and their market. But ask them to explain their gross margin, interpret a cash flow statement, or calculate their burn rate, and many will go quiet. That gap is not a character flaw. It is simply a skill that was never formally taught.
Financial literacy is the ability to read, understand, and act on the numbers that drive your business. It does not require an accounting degree. It does not mean you need to do your own books. It means you understand what your numbers are telling you well enough to make good decisions. And for small business owners, that understanding is often the difference between growing with confidence and flying blind.
This guide breaks down what financial literacy actually means in practice, which numbers matter most, and how to build the habit of using data to run a sharper, more profitable business.
Why Financial Literacy Is a Competitive Advantage
Businesses run on money. That sounds obvious, but many owners treat their finances like a report card they check after the fact rather than a dashboard they use to steer. Financially literate owners do something different: they use their numbers to make decisions before problems show up, not after.
When you understand your financials, you can tell whether a new client is actually profitable or just busy-work. You can spot a cash flow squeeze three months out instead of panicking when payroll is due. You can walk into a conversation with a lender, investor, or partner and hold your own. These are not small advantages. They compound over time into a business that is genuinely harder to knock down.
The Four Numbers Every Owner Must Know Cold
You do not need to memorize every financial metric. But there are four numbers that every small business owner should be able to recite without looking anything up.
1. Gross Profit Margin
This is your revenue minus the direct cost of delivering your product or service, expressed as a percentage of revenue. If you earn $10,000 in a month and it costs you $4,000 in materials and direct labor to deliver that work, your gross margin is 60 percent.
Gross margin tells you how efficiently your core business model works before you layer in overhead. A high gross margin means more room to cover fixed costs and generate profit. A shrinking gross margin is often the first warning sign that something is wrong with your pricing or your costs.
2. Net Profit
This is what is left after all expenses: direct costs, overhead, salaries, rent, software, taxes, and everything else. Net profit is the real number. Revenue is vanity, profit is sanity. Many small businesses look healthy on revenue but are quietly losing money once all costs are counted.
Track your net profit monthly. If it is consistently negative, that is not a cash flow problem; it is a business model problem that needs structural attention. Keeping close tabs on this number is part of identifying and fixing revenue leaks before they drain your business.
3. Cash Flow
Cash flow is the movement of money in and out of your business over a given period. You can be profitable on paper and still run out of cash if your clients pay late or your expenses hit before your revenue does. This is one of the most common reasons healthy businesses hit walls.
Know your typical cash cycle: how long from sale to payment, how long you can float expenses, and what your minimum operating balance needs to be. If you do not have a cash flow forecast, even a rough 90-day spreadsheet is better than nothing.
4. Break-Even Point
Your break-even point is the revenue you need to cover all your fixed and variable costs for a given period. Anything above that is profit. Anything below is a loss. Knowing your break-even is the foundation of every pricing, hiring, and investment decision you make.
If your break-even is $15,000 per month and you have a $25,000 month, you know exactly how much cushion you have. If a slow month brings in only $12,000, you know exactly how deep you are in the hole and what you need to do to recover.
Understanding Your Three Core Financial Statements
Every business produces three key financial documents. Most owners see them occasionally and ignore them the rest of the time. That is a mistake. Here is what each one actually tells you.
The Income Statement (Profit and Loss)
The income statement shows your revenue, expenses, and profit over a period of time, typically a month, quarter, or year. It is your business’s report card for performance. Read it to understand whether the business is making or losing money, where costs are climbing, and whether revenue trends are moving in the right direction.
The Balance Sheet
The balance sheet is a snapshot of your business’s financial position at a single point in time. It shows what you own (assets), what you owe (liabilities), and the difference (equity). A strong balance sheet means the business has more assets than liabilities and is building equity over time. A weak one means you are overleveraged or have let liabilities grow faster than assets.
The Cash Flow Statement
The cash flow statement shows where your cash came from and where it went during a period. Unlike the income statement, which can include revenue you have earned but not yet collected, the cash flow statement only counts actual money moving. It is the most honest picture of your business’s financial health in real time.
Reading these three statements together gives you a complete picture. The income statement tells you whether you are profitable. The balance sheet tells you whether the business is healthy. The cash flow statement tells you whether you can pay your bills. You need all three.
Practical Habits That Build Financial Literacy Over Time
Financial literacy is not something you develop in a seminar. It is built through consistent engagement with your own numbers. Here are the habits that matter most.
Do a Weekly Money Review
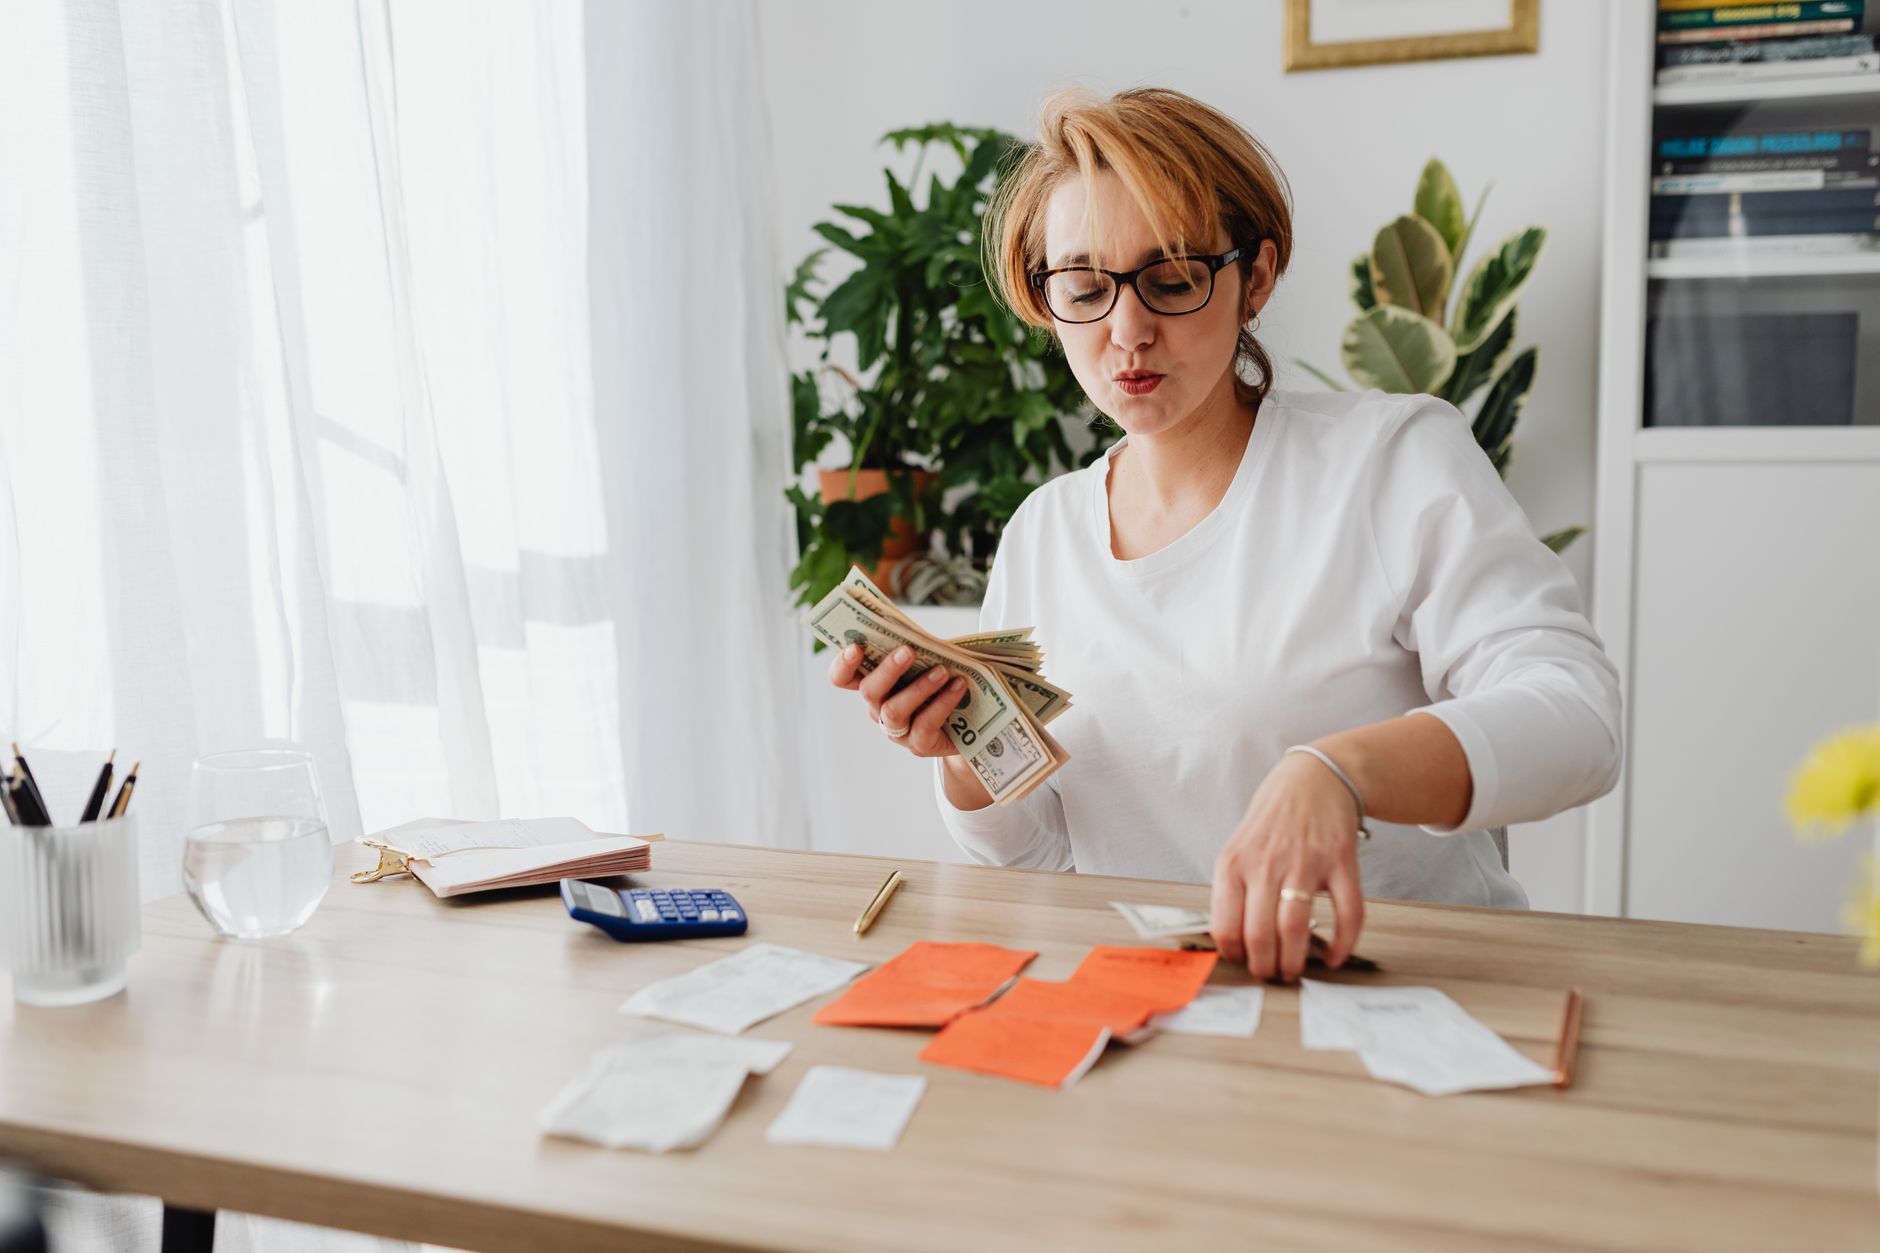
Set aside 20 to 30 minutes every week to review your bank balances, outstanding invoices, upcoming expenses, and recent transactions. This is not accounting; it is awareness. The goal is to stay connected to your financial reality so nothing sneaks up on you.
Read Your Reports Monthly
Once a month, open your income statement and ask three questions: Did revenue go up or down compared to last month and last year? Did any expense categories jump unexpectedly? Was the business profitable? If you use accounting software like QuickBooks, FreshBooks, or Wave, these reports are already being generated automatically. You just need to read them.
Ask Your Accountant to Teach, Not Just File
Many small business owners hand their books to an accountant and never look at the output. That is leaving value on the table. Ask your accountant to walk you through your financials at least once a quarter. Ask what the numbers mean, not just what they are. A good accountant will welcome the opportunity to teach rather than just file.
Learn the Language
Terms like accounts receivable, depreciation, working capital, and EBITDA sound intimidating until you look them up once. The SBA’s financial management resources offer free, plain-English explanations of the concepts small business owners need most. Spend 15 minutes a week learning one new term and how it applies to your business. Within a year, you will have a working fluency that most of your competitors lack.
Connecting Financial Literacy to Strategic Decisions
Financial literacy is not just about understanding the past; it is about making better decisions for the future. When you know your numbers, you can answer questions that otherwise stay fuzzy.
Can you afford to hire right now? Run the numbers. What does adding a $60,000 salary do to your break-even? What revenue increase would it need to generate to pay for itself? Should you take on that large client that requires you to front three months of materials? What does your cash flow forecast say? Is a price increase justified? Look at your gross margins compared to your cost of living increases and decide with data, not instinct.
This is the real power of financial literacy: it turns gut-feel decisions into informed ones. It does not eliminate uncertainty, but it gives you a framework to make better bets. Paired with a habit of thinking like an investor when running your business, financial literacy becomes one of the most durable competitive advantages a small business owner can build.
Tools That Make It Easier
You do not have to do this manually. A few simple tools go a long way.
- Accounting software: QuickBooks, FreshBooks, Xero, or Wave automate your books and generate reports automatically. There is no excuse for not using one of these.
- Dashboards: Tools like LivePlan or Fathom pull your accounting data into visual dashboards that make trends easy to spot without reading spreadsheets.
- Simple spreadsheets: A Google Sheet tracking monthly revenue, expenses, and cash position is better than nothing and better than most owners have.
- Your accountant: Use them as an advisor, not just a tax filer. A monthly or quarterly check-in focused on your numbers pays for itself many times over.
The Bottom Line
Financial literacy will not make you a better plumber, designer, or chef. But it will make you a better business owner regardless of what you do. The owners who build wealth over time are almost always the ones who stay close to their numbers, understand what those numbers mean, and use that understanding to make smarter decisions week after week.
You do not have to master accounting. You just have to stop being afraid of the numbers and start using them as a tool. Start with the four core metrics. Read your monthly report. Ask your accountant a question. Build the habit one step at a time.
The numbers are not there to judge you. They are there to guide you.
Want more plain-English guides to running a smarter small business? Join the Hustler’s Library for free and get the resources, strategies, and insights serious entrepreneurs actually use.
Ready to Know Where You Stand?
The Business Journey dashboard maps your exact position across all 13 stages. Track your progress, unlock resources for each step, and build with a framework used by thousands of founders at Hustler's Library.
No credit card required · Takes 3 minutes · Personalized to your stage