Opening a business credit card is one of the highest-leverage moves you can make when building a business credit profile. Unlike net-30 vendor accounts that report to one or two bureaus, the right business credit card can report to all three major bureaus simultaneously, generating multiple data points from a single account. The challenge is knowing which cards are worth pursuing at each stage of your credit journey. This guide breaks down the best options for 2026, with a focus on businesses that are still in the credit-building phase.
Secured vs. Unsecured Business Credit Cards
If your business credit profile is thin or brand new, your first card will likely be a secured card. A secured business credit card requires a cash deposit that serves as your credit limit. You are not borrowing against your future income; you are borrowing against money you have already deposited. The benefit is that secured cards are far easier to qualify for, and they still report your payment history to business credit bureaus just like unsecured cards.
Unsecured cards, on the other hand, extend credit based on your creditworthiness without requiring a deposit. Most unsecured business cards require either a strong personal credit score, an established business credit profile, or both. Once you have six to twelve months of positive payment history across your net-30 accounts and a secured card, you become eligible for unsecured options with better rewards and higher limits.
For context on what your profile needs to look like before applying for an unsecured card, see our guide on how to build business credit from scratch.
Top Business Credit Cards for Building Credit in 2026
Capital One Spark Classic: Best Overall for Early-Stage Businesses
The Capital One Spark Classic is the most widely recommended card for businesses actively building credit. There is no annual fee, it is accessible to business owners with fair personal credit (typically a 580+ personal score), and it reports to all three major business credit bureaus: D&B, Experian Business, and Equifax Small Business. This triple reporting from a single card makes it extraordinarily efficient for credit profile building.
The card earns 1 percent cash back on all purchases, which is modest but meaningful for a card at this tier. The initial credit limit is typically lower, often between 00 and ,000, but that is fine. The goal is not a high limit; it is consistent, on-time payments that generate bureau reports.
Wells Fargo Business Secured Credit Card: Best for Controlled Starting Limits
The Wells Fargo Business Secured card requires a minimum deposit of 00, which becomes your credit limit. You can deposit up to 5,000. The card reports to D&B and Equifax, making it a useful complement to accounts that report to Experian. Wells Fargo also periodically reviews secured cardholders for upgrade to an unsecured product, which can happen within twelve to eighteen months of responsible use.
The annual fee is 5, which is negligible given the credit-building value. Wells Fargo also reports the account to business credit bureaus under the business name, not the personal name, which is critical for keeping your business and personal profiles separate.
BILL Divvy Corporate Card: Best for Businesses with Established Revenue
The BILL Divvy Corporate Card operates differently from traditional credit cards. Instead of a fixed credit limit, Divvy uses your business revenue and cash flow to set a dynamic spending limit. For businesses with at least six months of consistent revenue, Divvy can offer limits that far exceed what a traditional secured card would provide. There is no annual fee, no personal credit check for established businesses, and the card reports to D&B.
Divvy is particularly useful for businesses that have revenue but lack a deep credit history. The spend-based model means you grow your available credit as your business grows, rather than waiting for a bureau score to catch up with your actual financial health.
Bank of America Business Advantage: Best for Established Businesses
The Bank of America Business Advantage card is better suited for businesses that already have an established credit profile. It offers stronger rewards, higher initial limits, and integration with Bank of America business banking. The application process requires a solid personal credit score and some business history. If you are still in the first year of building credit, this card is likely premature, but it is an excellent target to work toward.
Comparison Table
| Card | Type | Reports To | Annual Fee | Best For |
|---|---|---|---|---|
| Capital One Spark Classic | Unsecured | D&B, Experian, Equifax | None | Early-stage builders |
| Wells Fargo Business Secured | Secured | D&B, Equifax | 5/yr | Thin or no profile |
| BILL Divvy Corporate | Charge (spend-based) | D&B | None | 6+ months revenue |
| Bank of America Business Advantage | Unsecured | D&B, Experian, Equifax | Varies | Established businesses |
The Right Strategy for Using These Cards
Use Cards for Regular Business Expenses
Do not let business credit cards sit in a drawer. Put your recurring business expenses on them: software subscriptions, fuel, supplies, professional services. The goal is consistent monthly activity that generates regular reporting to the bureaus.
Pay the Full Balance Every Month
This is non-negotiable. Carrying a balance on a business credit card means you are paying interest, which erodes any rewards you earn. More importantly, high utilization on a business card can hurt your Experian Intelliscore Plus just as high utilization on a personal card hurts your personal score. Keep utilization below 30 percent at all times, and ideally below 10 percent.
Pay Before the Statement Closes
The balance that gets reported to the credit bureaus is typically the statement balance, not your real-time balance. If you make a large purchase and pay it off before the statement closes, the bureaus see a low or zero balance, which translates to low utilization. This is a simple optimization that many cardholders overlook.
According to the Consumer Financial Protection Bureau’s guidance on business credit cards, understanding how and when balances are reported is one of the most important factors in managing business credit card utilization effectively.
For a broader look at your entire credit-building toolkit, including net-30 accounts, EIN setup, and business bank accounts, see our guide on how to build business credit.
The Verdict
For early-stage businesses with a thin or brand-new credit profile, the Capital One Spark Classic is the clear first choice. It costs nothing, reports to all three bureaus, and is accessible without a perfect personal credit score. Once your business has at least six months of consistent revenue and a growing credit file, add the BILL Divvy Corporate Card for its spend-based limits and seamless expense management. Together, these two cards cover your reporting needs and grow with your business as your revenue scales.
Ready to Build Smarter?
Get access to our full library of business guides, tools, and resources.
Tools like Credit Karma can help you monitor your business credit profile as it builds.
Ready to Know Where You Stand?
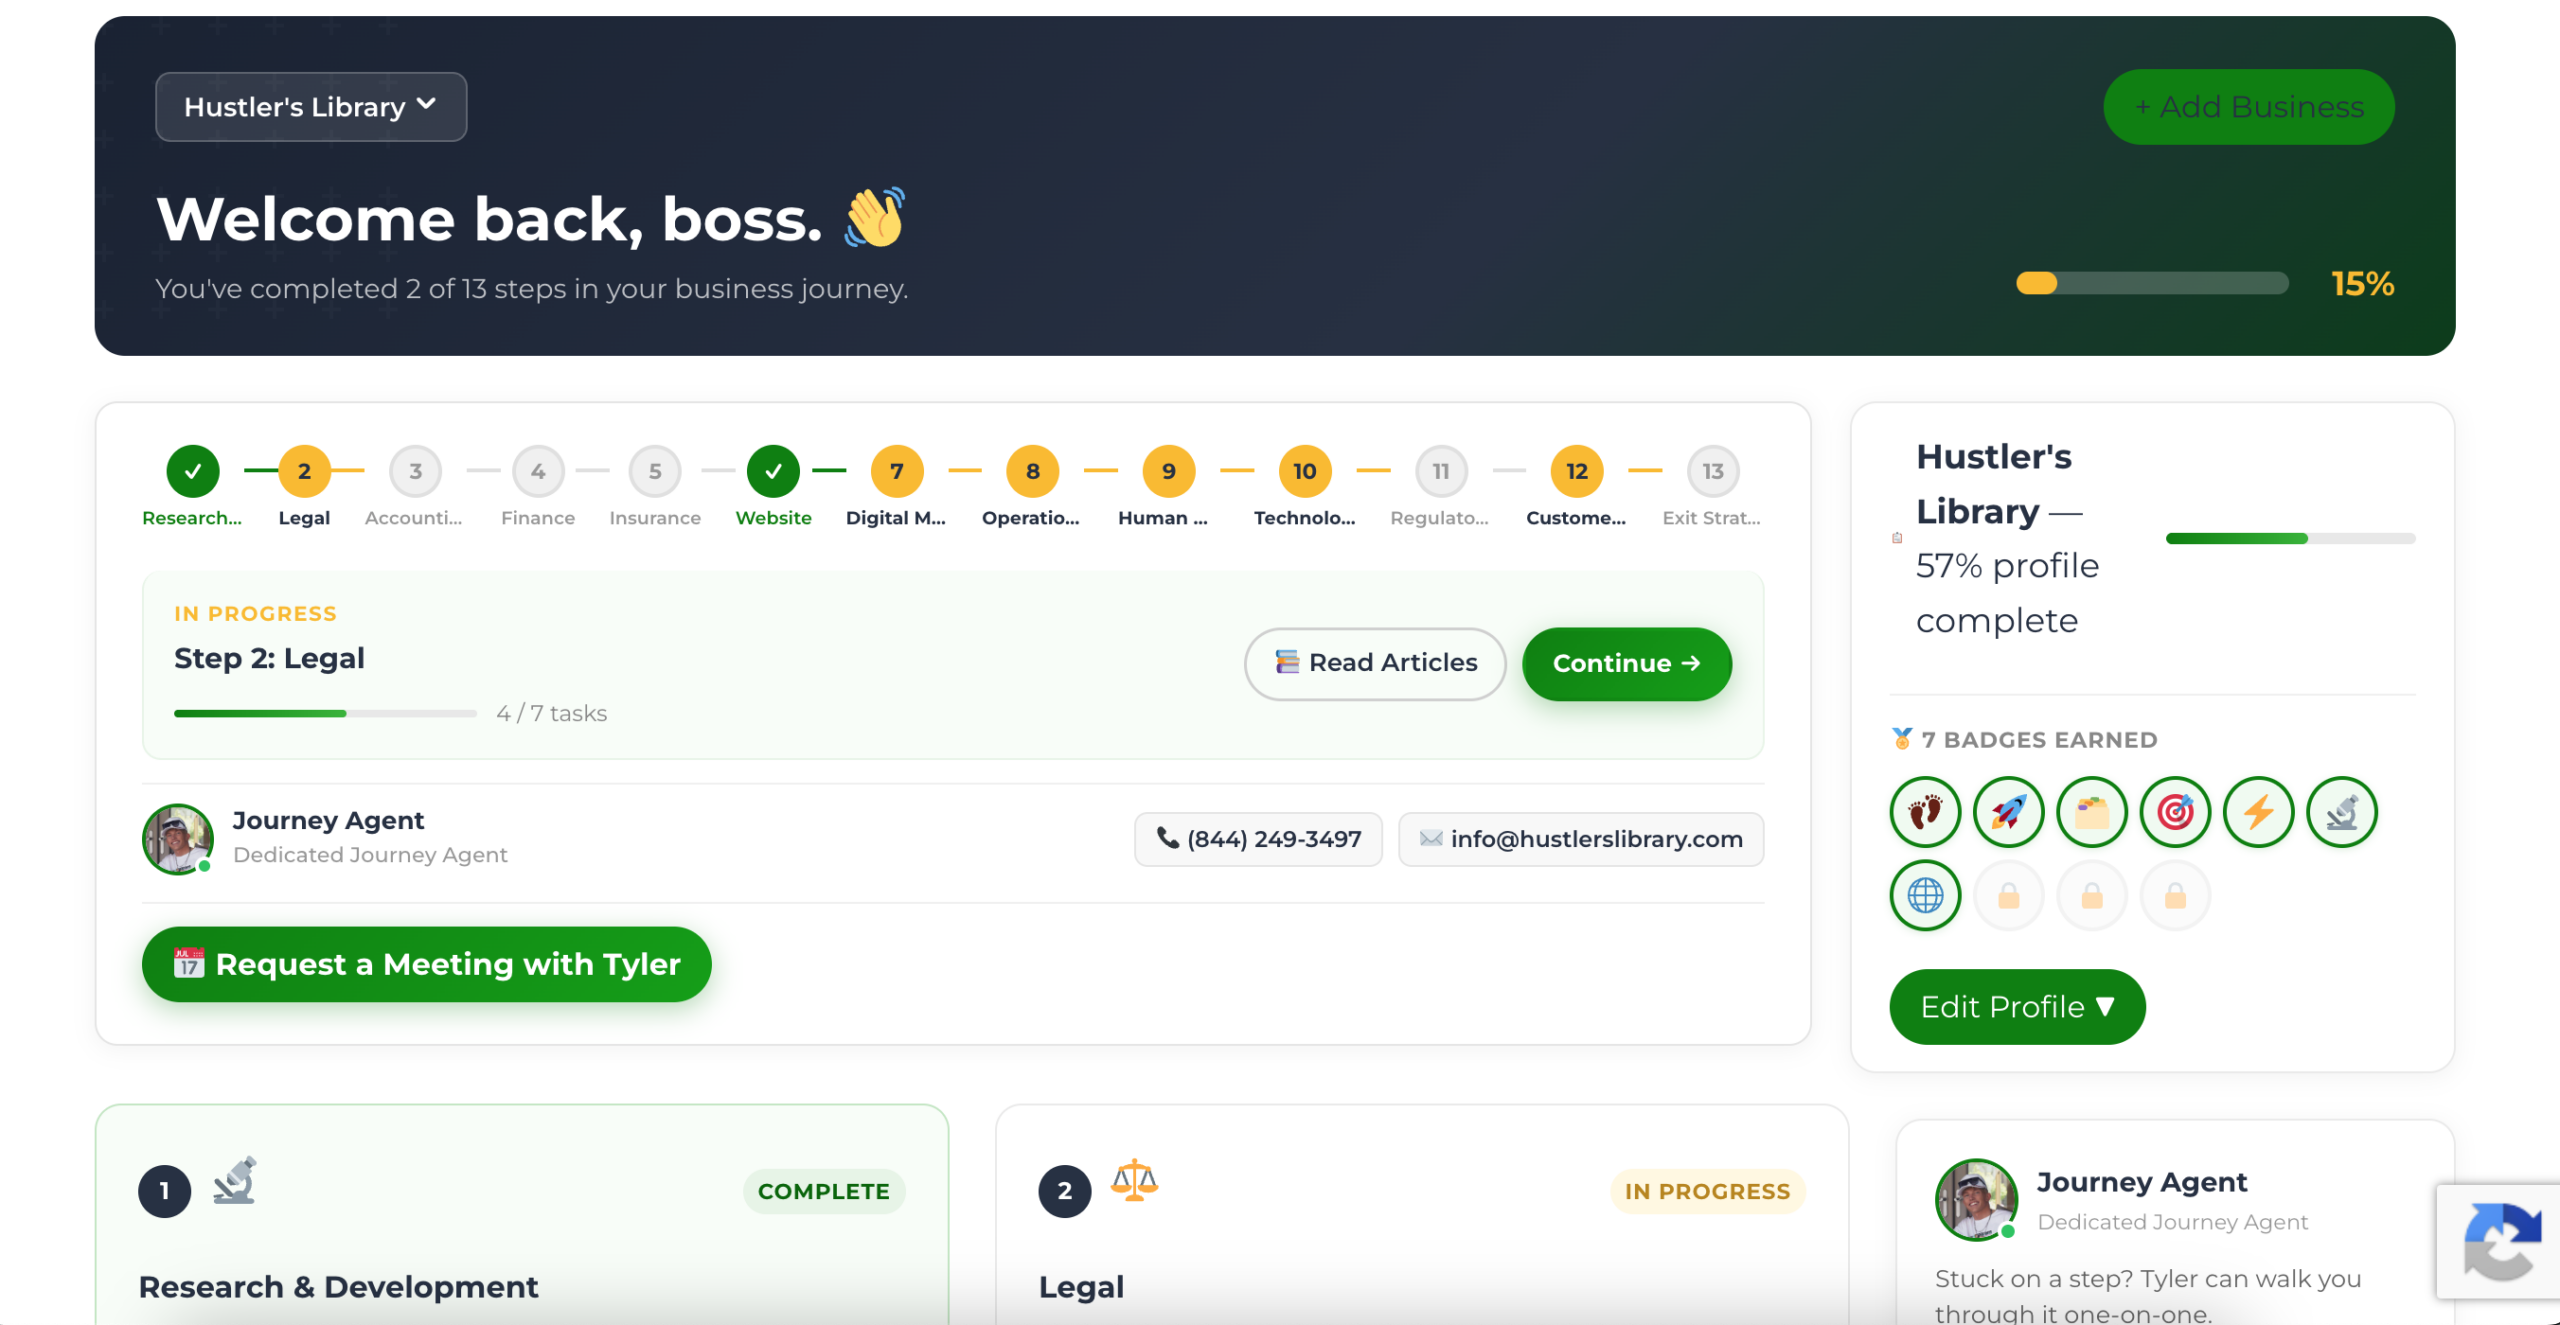
The Business Journey dashboard maps your exact position across all 13 stages. Track your progress, unlock resources for each step, and build with a framework used by thousands of founders at Hustler's Library.
No credit card required · Takes 3 minutes · Personalized to your stage