Your business account is hemorrhaging cash. Payroll is in two weeks. Rent is due. Vendors want payment. This is the moment every entrepreneur dreads and most are completely unprepared for.
Here is what you actually do when your business is running out of cash. Not vague advice. A real 30-day triage framework.
Why Most Businesses Die From Cash Problems, Not Bad Ideas
Profitable businesses go bankrupt every year. The reason is almost always the same: they run out of cash before the money they are owed arrives. Revenue and cash flow are not the same thing. Understanding this distinction is the first step toward surviving a cash crisis.
The 30-day window is critical. If you have less than 30 days of operating cash left, you are in survival mode. Every decision you make in this window either buys you time or accelerates the end.
Days 1-3: Get Brutally Clear on the Numbers
Before you do anything else, you need a real picture of where you stand. Pull your bank statements for the last 90 days. List every recurring expense. List every revenue source and when those dollars actually land in your account.
Build a 30-day cash flow projection. Column one: what cash is coming in and when. Column two: what cash must go out and when. The gap between those two numbers is your crisis number. Write it down. That is the number you are solving for.
What to look for immediately:
- Subscriptions and software you are paying for but not using
- Contracts with auto-renewal clauses that can be cancelled
- Any expense not directly tied to generating revenue this month
- Receivables you are owed but haven’t collected
Days 4-7: Stop the Bleeding
Every dollar you stop spending is a dollar you don’t have to earn. This is the fastest lever you have. To understand which expenses to cut first, read How to Cut Business Expenses Without Cutting the Business for a full framework on what to eliminate versus what to protect.
The short version: cut anything discretionary immediately. Pause marketing spend that isn’t generating direct revenue. Negotiate payment terms with your vendors. Most vendors would rather get paid late than not get paid at all. Call them before they call you. A 30 or 60 day extension buys real breathing room.
Conversations you need to have this week:
- Your landlord: ask about deferral or partial payment
- Your top vendors: negotiate net-60 terms on outstanding invoices
- Your lenders: ask about payment deferral or interest-only periods
- Your top clients: can any of them prepay for future work or services?
Days 8-14: Accelerate Incoming Cash
Cutting expenses buys time. But you also need to speed up money coming in. Review every open invoice. Any receivable over 30 days is a priority collection call, not an email.
Offer a small discount for early payment. If a client owes you $10,000 and you offer 5% off for paying today, you get $9,500 cash now instead of $10,000 in 60 days. In a cash crisis, that trade is almost always worth it.
If you have inventory, consider a clearance sale. Liquidating slow-moving inventory at cost or below cost turns dead assets into operating capital. The inventory isn’t helping you if the business closes.
Days 15-21: Pursue Emergency Funding
If cutting and collecting isn’t closing the gap fast enough, you need capital. The Small Business Funding Guide covers the full range of options. For a crisis specifically, speed matters more than cost.
Your fastest options, roughly in order of speed:
- Business line of credit: If you already have one, draw on it now
- Invoice factoring: Sell your outstanding invoices for immediate cash (typically 80-90% of face value)
- Merchant cash advance: Fast but expensive; only use if you have strong daily card sales
- SBA Economic Injury Disaster Loan (EIDL): Lower cost but slower, often 3-4 weeks to fund
- Friends and family: Document everything; protect the relationship with a formal note
According to the SBA’s lending programs page, most SBA loan programs require time to process. If you’re in a 30-day crisis, traditional SBA loans may not be fast enough. EIDL and emergency options are the exception.
Days 22-30: Stabilize and Build a Buffer
If you’ve made it to week four, you’ve either closed the gap or you have a clearer picture of what it will take. This is when you build the system that prevents this from happening again.
The single most important thing you can do: establish a 90-day cash reserve. Three months of operating expenses sitting in a separate account. Build toward it $500 at a time if that’s what it takes. Businesses with a cash reserve survive; businesses without one don’t.
Systems to put in place before Day 30:
- Weekly cash flow review (not monthly; weekly)
- A rolling 13-week cash projection spreadsheet
- Automatic transfers to a reserve account on every deposit
- Net-30 or shorter payment terms on all new client contracts
When to Call a Professional
If your 30-day projection shows you going negative even after all of the above, you need to talk to a business attorney or a turnaround consultant before the money is completely gone. Options like Chapter 11 reorganization exist precisely to help businesses restructure debt and survive. Waiting until you’re out of cash removes those options.
Resources like NerdWallet, Investopedia, and Hustler’s Library can help you understand the landscape, but a licensed professional can help you execute under pressure.
The Bottom Line
A cash crisis isn’t automatically a death sentence. Businesses survive them every day by moving fast, making hard calls early, and using every lever available. The 30-day window is real. Act in the first 72 hours, not the last 72.
You built this business. Fight for it with the same intensity you built it with.
Want more frameworks like this? Join Hustler’s Library free and get the tools serious business owners actually use.
Ready to Know Where You Stand?
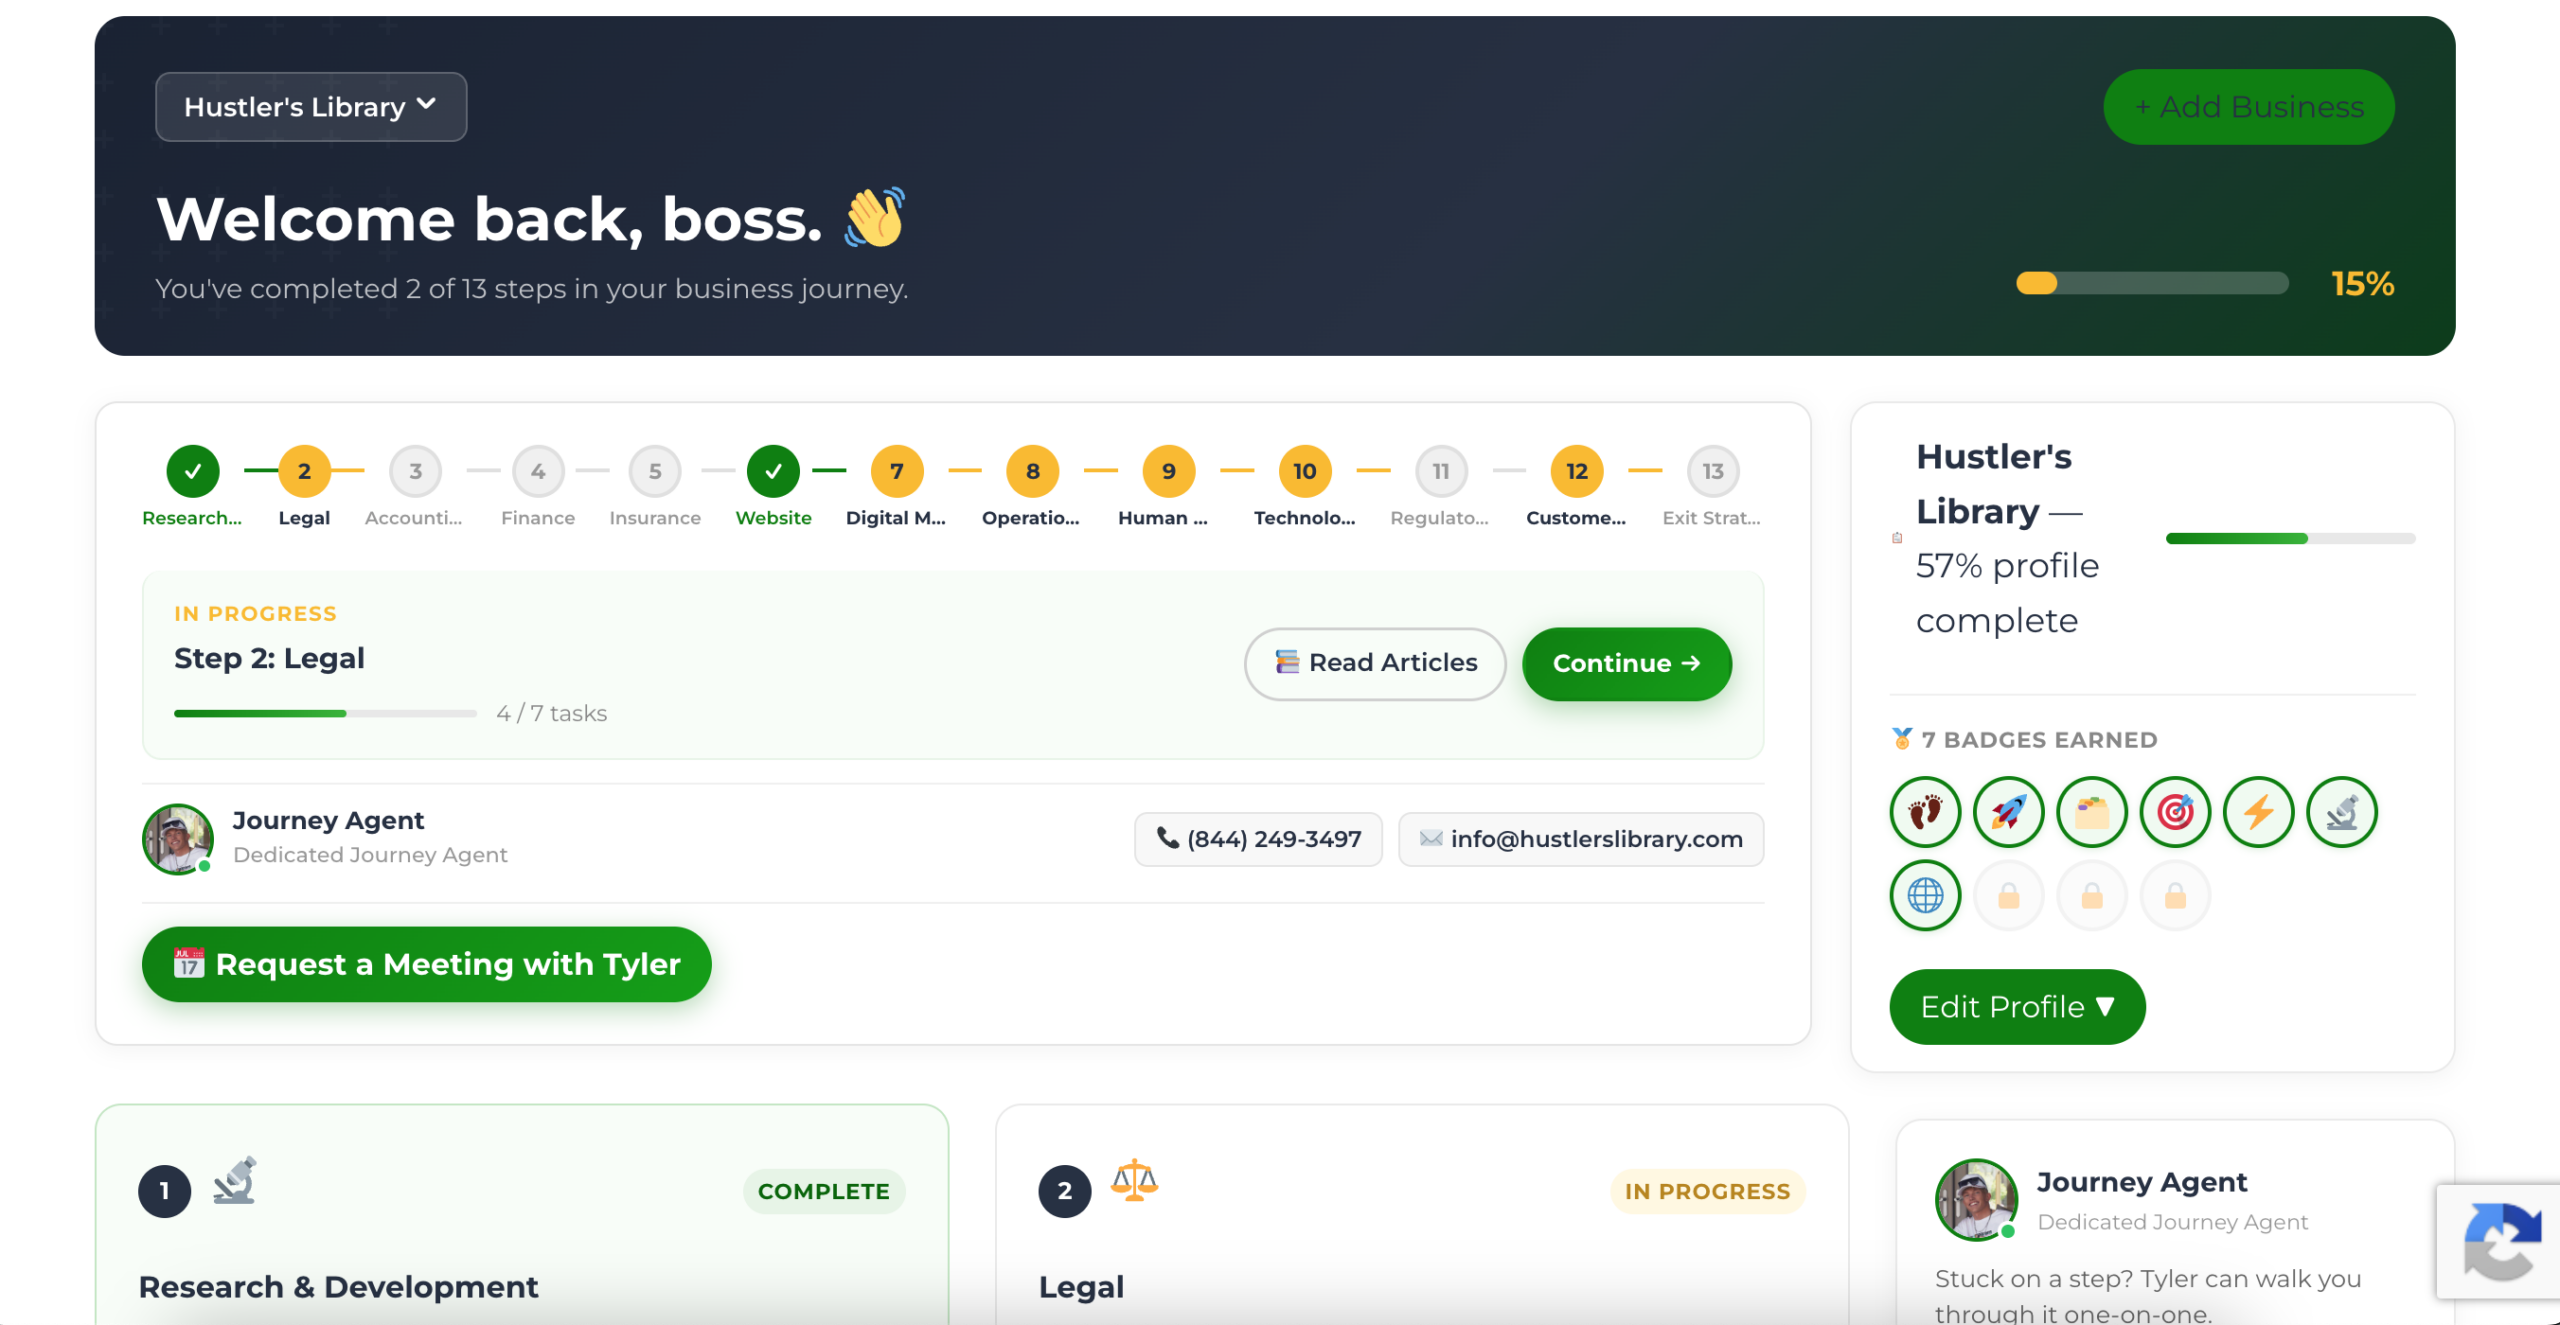
The Business Journey dashboard maps your exact position across all 13 stages. Track your progress, unlock resources for each step, and build with a framework used by thousands of founders at Hustler's Library.
No credit card required · Takes 3 minutes · Personalized to your stage