If you are buying or selling a small business in the United States, there is a good chance the deal will be financed with an SBA 7(a) loan. This program has become the dominant financing mechanism for small business acquisitions, and for good reason: it allows buyers to acquire profitable businesses with as little as 10% down, stretched over a 10-year repayment period. Understanding how it works is essential whether you are the buyer trying to structure a deal or the seller trying to make your business easier to finance.
What Is an SBA 7(a) Loan?
The SBA 7(a) loan program is the Small Business Administration’s primary lending vehicle. The SBA does not lend money directly. Instead, it guarantees a portion of loans made by approved private lenders: typically banks and credit unions. This guarantee reduces the lender’s risk, which allows them to offer better terms to borrowers than they could on conventional loans.
For business acquisitions specifically, the 7(a) program offers:
- Loan amounts up to million
- 10-year repayment terms for business acquisitions (longer than most conventional business loans)
- Interest rates typically set at prime rate plus 2.75%, adjusted periodically
- Down payment as low as 10% of the purchase price in many cases
- No balloon payments on most structures
The combination of low down payment and long repayment term makes monthly payments genuinely manageable. A buyer acquiring a million business with 10% down (00,000) and financing 00,000 at current rates over 10 years might face monthly payments around ,000 to 0,000. If the business generates 00,000 or more in annual cash flow, that debt service is very manageable.
What Qualifies for SBA 7(a) Acquisition Financing?
Not every business or buyer qualifies. Here is what lenders look for:
The Business Being Acquired
- Must have at least two to three years of tax returns showing consistent profitability
- Must be in an eligible industry (most are; exceptions include passive income businesses, gambling, and certain financial companies)
- Must have a debt service coverage ratio that supports the loan: the business needs to generate enough cash flow to cover the new debt payments, typically with a 1.25x cushion
- Must be a for-profit business operating in the United States
The Buyer
- Relevant industry experience or management background is strongly preferred
- Good personal credit (most lenders want 680 or above, though some will go lower)
- Clean financial history: no recent bankruptcies or defaults on government loans
- Ability to inject the required down payment from documented sources
The SBA Acquisition Process
The timeline from application to closing typically runs 60 to 90 days. Here is how it works:
Step 1: Find an SBA-preferred lender. Not all banks are equal in SBA lending. SBA Preferred Lenders have delegated authority to approve loans without going through additional SBA review, which significantly speeds up the process. Search the SBA’s lender match tool or ask your broker for referrals to lenders who specialize in acquisitions.
Step 2: Get pre-qualified before making offers. Sellers and their brokers take buyers more seriously when they come with a lender pre-qualification letter. Get this before you submit a letter of intent. It also helps you understand exactly how much you can borrow and what deal size is realistic.
Step 3: Submit a full loan package. Once your offer is accepted, your lender will require three years of business tax returns, interim financial statements, a purchase agreement, a business plan, and personal financial statements from the buyer.
Step 4: Underwriting and SBA submission. The lender underwrites the deal and, for non-preferred lenders, sends it to the SBA for approval. This is often the longest part of the process.
Step 5: Closing. Funds are disbursed, assets are transferred, and ownership changes hands.
What Sellers Need to Know About SBA Loans
If your buyer is using SBA financing, there are a few things that directly affect you as the seller:
Escrow holdback requirements. SBA lenders often require that 10% to 20% of the purchase price be held in escrow for up to 12 months post-closing. This protects the buyer and lender if undisclosed liabilities surface shortly after the sale. As a seller, this means a portion of your proceeds arrives later, not at closing.
Standby seller notes. The SBA frequently requires sellers to carry a promissory note for 10% to 33% of the purchase price, placed on standby for 24 months. During standby, you cannot receive principal or interest payments on that note. After 24 months, payments resume. This is common when the buyer’s down payment is thin or the deal needs additional credit support.
Your financials will be audited thoroughly. SBA lenders scrutinize tax returns, add-backs, and adjustments. If your books have inconsistencies, expect the loan process to slow down or collapse entirely. Clean, well-documented financials are your best asset when working with SBA buyers.
Why SBA Loans Dominate Small Business Acquisitions
The answer is simple: there is no better alternative for most buyers. Conventional business loans for acquisitions are hard to get, require larger down payments, and carry shorter terms with higher monthly payments. Private equity requires scale. Seller financing alone rarely covers the full purchase price. The SBA 7(a) fills the gap and does it at terms that make acquisitions financially viable for individual buyers.
For sellers, having a business that qualifies for SBA financing dramatically expands your buyer pool. Any business with clean tax returns, consistent profitability, and reasonable pricing is a strong SBA candidate. Making your business SBA-loan-ready is one of the best things you can do before going to market.
For the full official program details, see the SBA 7(a) loan program page. To understand the full acquisition process from the buyer’s perspective, read our guide on how to buy a business, and for valuation methods that will affect your loan sizing, see how to value a business.
Ready to Build Smarter?
Get access to our full library of business guides, tools, and resources.
Ready to Know Where You Stand?
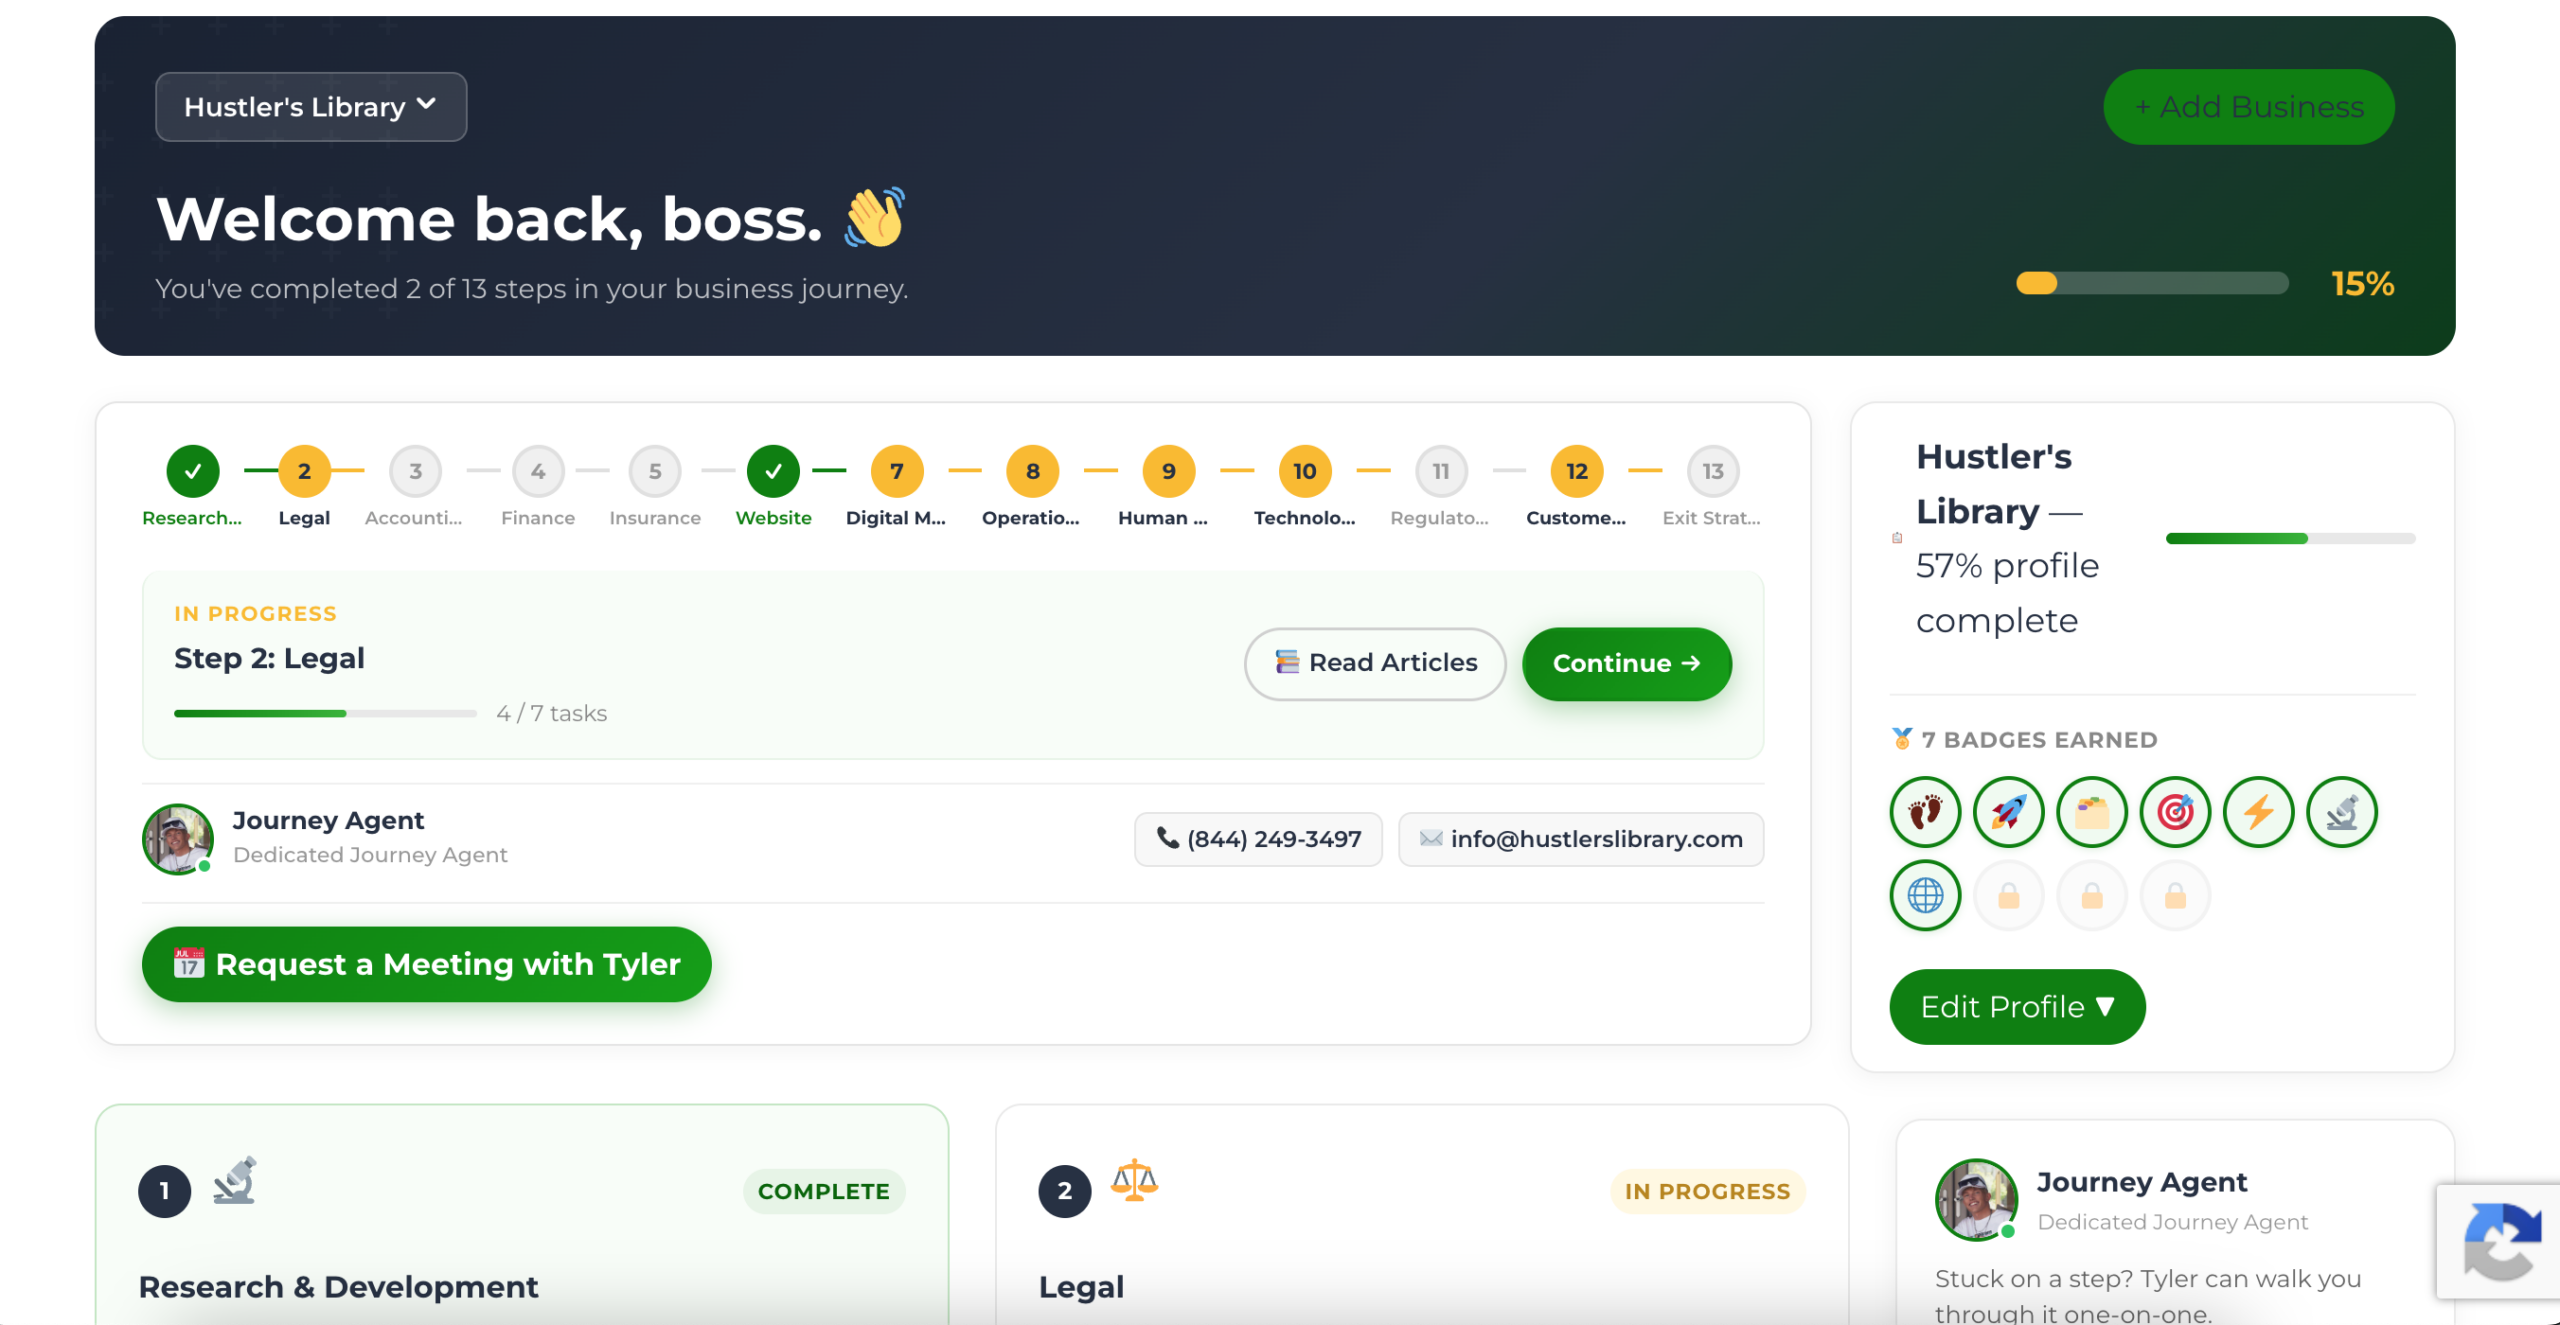
The Business Journey dashboard maps your exact position across all 13 stages. Track your progress, unlock resources for each step, and build with a framework used by thousands of founders at Hustler's Library.
No credit card required · Takes 3 minutes · Personalized to your stage