The Federal Reserve raised interest rates on Tuesday, September 16th — its first rate hike in three years. The Federal Open Market Committee voted 12-0 to lift the target range for the federal funds rate by a quarter point, pushing it to 3.75% to 4.00%. The move was widely telegraphed but still lands hard for small business owners who have spent the last year watching borrowing costs stay elevated while hoping for relief.
In its official statement, the Fed was direct: “Inflation remains elevated. Today’s policy action will support a timelier return to the Committee’s 2 percent goal.” Translation: rates are going up, and they’re not coming down soon.
What This Actually Means
For big corporations, a quarter-point hike is a rounding error. For a small business owner with a $200,000 line of credit, it’s a real number on a real invoice. Every rate hike directly increases the cost of variable-rate business loans, SBA loans tied to the prime rate, business credit cards, and any new financing you take on.
The prime rate — the benchmark most small business lenders use — typically moves in lockstep with the federal funds rate. That means your existing variable-rate debt just got more expensive overnight. If you’re carrying a balance on a business line of credit or a variable-rate SBA loan, your monthly payment just ticked up. Not catastrophically, but noticeably.
The bigger issue is what this signals for the road ahead. The Fed raised rates because inflation is still stubborn. That means input costs, supplier prices, and wage pressures aren’t going away any time soon. The businesses that navigate this well won’t be the ones waiting for rates to drop — they’ll be the ones building operations that work in a higher-cost environment.
And while markets actually rallied after the announcement — according to CNBC, the S&P 500 and Nasdaq Composite both added more than 1.1% Thursday — equity markets often reward certainty over ambiguity. Wall Street got the hike it expected. Main Street got the bill.
The Numbers Behind It
Here’s the context that matters for business owners specifically:
- The SBA counts 33.2 million small businesses operating in the United States. The vast majority rely on some form of external financing. A rate environment above 4% hits nearly all of them.
- The Federal Reserve’s own Small Business Credit Survey consistently shows that access to capital ranks among the top challenges for small businesses — and that challenge intensifies every time the cost of that capital rises.
- According to the NFIB, the Small Business Optimism Index held at 98.6 in Q1 2026, suggesting owners were cautiously holding steady. A rate hike after months of expectations for relief may test that optimism.
The businesses most exposed are those in capital-intensive industries — construction, manufacturing, food service, retail — where operating lines of credit and equipment loans aren’t optional. If you’re in one of those sectors, this hike is more than a headline.
The Hustler’s Library Take
Most small business owners should not panic, but they absolutely should pay attention. Waiting for rates to fall back to 2021 levels is not a strategy. The businesses that thrive in this environment are the ones treating capital efficiency like a competitive advantage, not an afterthought.
This is exactly the wrong moment to be carrying unnecessary debt, over-leveraging on inventory, or taking on variable-rate financing without a clear repayment timeline. The businesses that built lean, cash-flow-positive operations over the last two years are sitting well right now. The ones that stretched thin hoping for cheap money are going to feel this quarter-point hike more than they expected.
If you haven’t already reviewed your outstanding debt and identified which pieces are variable-rate versus fixed, do it today. Not next week. Today.
What You Should Do
1. Audit your variable-rate exposure. Pull every outstanding loan, line of credit, and credit card balance. Flag anything tied to the prime rate. Calculate what a 0.25% increase does to your monthly payment on each. If the number surprises you, that’s a problem to solve now, not later. Our guide on using financial modeling to make better business decisions walks you through exactly this kind of cash flow stress-testing.
2. Lock in fixed-rate terms where you can. If you’re carrying a balance on a variable-rate line of credit, explore converting it to a fixed-rate term loan before rates climb higher. Lenders will negotiate. The time to do this is before you’re under pressure. Start with our breakdown of how to use leverage strategically to understand the difference between debt that builds you and debt that drains you.
3. Recalculate your capital allocation plan. Higher rates change the math on almost every investment decision. Projects that made sense at 3% borrowing costs may not pencil out at 4.5%. Equipment purchases, expansion plans, new hires funded by credit lines: all of these need to be recalculated. Our guide on investing your small business profits wisely covers capital allocation when the cost of money shifts. And if equipment is on the table, our overview of equipment financing will help you run the numbers correctly in this rate environment.
The Fed’s full statement is available directly at federalreserve.gov. Read it. It’s four sentences. And it tells you everything you need to know about where the next 12 months are heading.
Want the news that matters to your business, every morning? Join Hustler’s Library for free and get the playbook, not just the headlines.
Ready to Know Where You Stand?
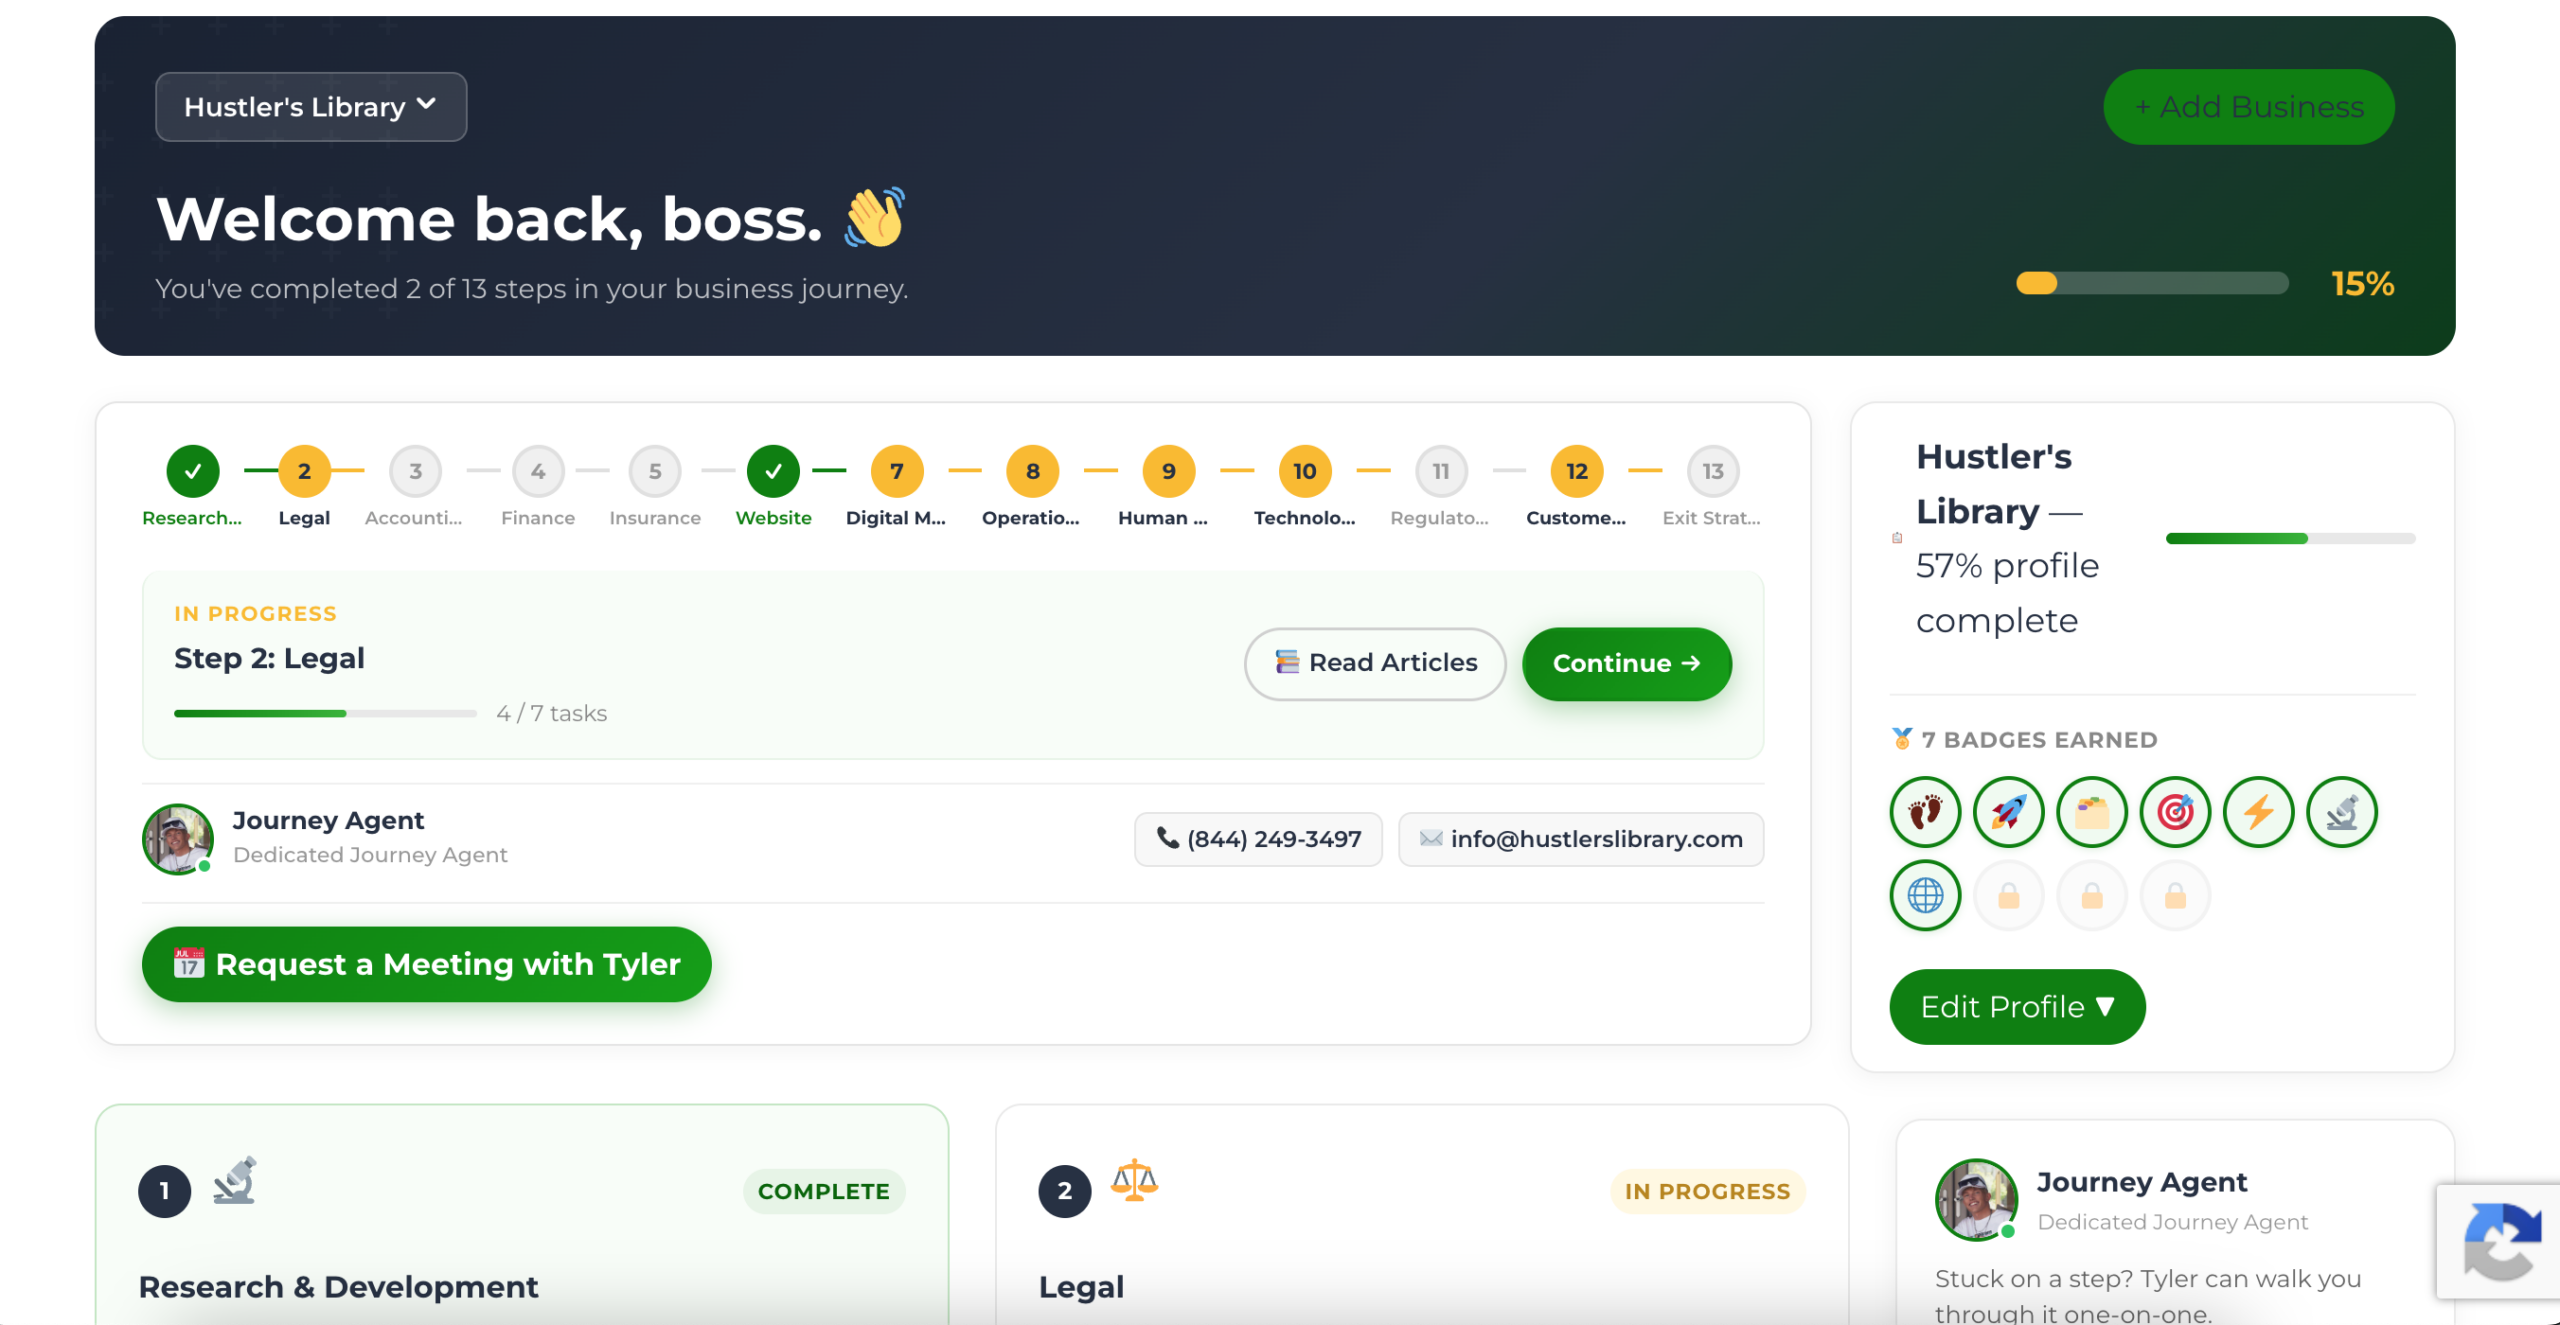
The Business Journey dashboard maps your exact position across all 13 stages. Track your progress, unlock resources for each step, and build with a framework used by thousands of founders at Hustler's Library.
No credit card required · Takes 3 minutes · Personalized to your stage