“How do I pay myself?” is one of the first questions new LLC owners ask, and it is one of the most poorly explained topics in small business content. The answer depends on how your LLC is taxed, how many members it has, and whether you have made an S-Corp election. This guide breaks it all down clearly so you can set up a system that keeps you paid, the IRS satisfied, and your books clean.
The Default: Single-Member LLC and the Owner’s Draw
If you formed a single-member LLC and have not made any special tax elections, your LLC is taxed as a disregarded entity by default. That is IRS language for: the LLC does not pay taxes separately. All profits and losses flow directly onto your personal tax return (Schedule C).
In this structure, paying yourself is straightforward. You take an owner’s draw: you simply transfer money from your business bank account to your personal bank account. There is no payroll required. No W-2. No formal salary structure. You just move the money.
The critical thing to understand is that you are taxed on profits, not on what you withdraw. If your LLC earns 0,000 this year and you only transfer 0,000 to your personal account, you still owe taxes on the full 0,000. This is why separating your business and personal finances is essential. Your business account needs to be a true accounting of what the business earned and spent. You cannot blur those lines and expect to know what you actually owe.
On a single-member LLC taxed as a disregarded entity, you also pay self-employment tax (15.3%) on your net profit. That covers Social Security and Medicare. It is the equivalent of both the employee and employer portions of FICA, because you are both. This is often a shock to first-year LLC owners who expected to owe only income tax.
Multi-Member LLCs: Distributions Per the Operating Agreement
If your LLC has two or more members, it is taxed as a partnership by default. Each member pays taxes on their share of the profits as defined by the operating agreement, regardless of how much they actually withdrew.
Members take distributions rather than draws, and the split is governed by the operating agreement you drafted when the LLC was formed. If you own 60% and your partner owns 40%, profits are typically allocated on that same ratio unless your operating agreement specifies otherwise.
The key mistake in multi-member LLCs is paying members inconsistently or without documentation, then trying to reconcile it at tax time. Keep a clean record of every distribution taken, by whom, and on what date. Your accountant will thank you, and you will avoid partner disputes down the road.
The S-Corp Election: Salary Plus Distributions
This is where LLC compensation gets more complex, and also potentially more tax-advantageous. When you elect S-Corp status for your LLC (by filing IRS Form 2553), the tax rules change significantly.
As an S-Corp, you are required to pay yourself a “reasonable salary” through payroll. You become a W-2 employee of your own company. After paying yourself a salary, additional profits can be distributed to you as an owner distribution. Those distributions are not subject to self-employment tax (15.3%). The salary is.
Here is a simplified example of why this matters:
- Your LLC earns 20,000 in net profit
- You pay yourself a reasonable salary of 5,000 via payroll
- The remaining 5,000 is taken as a distribution
- You save 15.3% self-employment tax on that 5,000 difference: roughly ,400 in savings
That is meaningful money. But the S-Corp strategy comes with real overhead: you need payroll software or a payroll service, you need to file quarterly payroll taxes, and you need an accountant to handle the S-Corp tax return (Form 1120-S), which is more complex than a Schedule C. Most CPAs estimate the S-Corp election makes sense once you are clearing 0,000 to 0,000 in net profit annually. Below that, the costs eat the savings.
For more on the LLC formation process itself, see our guide on how to form an LLC state by state.
The Common Mistake: Irregular Pay and No Tax Set-Aside
The most common mistake new LLC owners make with owner compensation is paying themselves irregularly and not setting aside money for taxes as they go.
Because there is no employer withholding taxes on your behalf (unlike a W-2 job), you are responsible for paying estimated quarterly taxes to the IRS yourself. These are due in April, June, September, and January for the prior year’s income. If you skip estimated payments and owe a large sum at year-end, you may also owe underpayment penalties on top of the tax bill.
The IRS provides clear guidance on self-employment tax and estimated payments at IRS.gov’s self-employment tax resource. Reading it once will save you from several expensive surprises.
A Practical System for Paying Yourself
The best approach for most single-member LLC owners is a simple, consistent system:
Step 1: Build a Buffer First
Before you start taking regular draws, accumulate at least 3 months of business operating expenses in your business account. This gives you a cushion so that a slow month does not force you to choose between paying yourself and paying your vendors.
Step 2: Set a Fixed Monthly Transfer
Decide on a fixed monthly transfer amount from your business account to your personal account. Treat it like a paycheck. Predictability helps your personal budgeting and makes it easier to project your business cash flow. You can revisit and adjust the amount quarterly as your revenue changes.
Step 3: Set Aside 25-30% for Taxes Immediately
Every time revenue hits your business account, move 25% to 30% into a separate savings account designated for taxes. Do not touch it for anything else. When estimated tax due dates arrive, pay from that account. If you over-save, great: you get a refund or carry it forward. Under-saving creates stress and penalties.
Step 4: Pay Quarterly Estimates on Time
Mark the IRS estimated tax due dates on your calendar. Use IRS Direct Pay or EFTPS to submit payments. Keep records of every payment. If you use payroll software for an S-Corp election, these payments are largely handled automatically, but you still need to stay on top of the schedule. You can find the exact due dates and filing requirements in our guide on how to set up payroll for your small business.
The Bottom Line
How you pay yourself as an LLC owner depends on your tax structure. Single-member LLC: owner’s draw, no payroll, pay self-employment tax on profits. Multi-member LLC: distributions per your operating agreement. S-Corp election: reasonable salary through payroll, then distributions on top.
Regardless of structure, the discipline that matters most is this: separate your money cleanly, set aside taxes immediately, and pay yourself consistently rather than randomly. Treat your compensation like a business decision, not an afterthought, and your finances will reflect it.
Ready to Build Smarter?
Get access to our full library of business guides, tools, and resources.
Services like LegalZoom can simplify the business formation process and help ensure your legal documents are filed correctly.
Ready to Know Where You Stand?
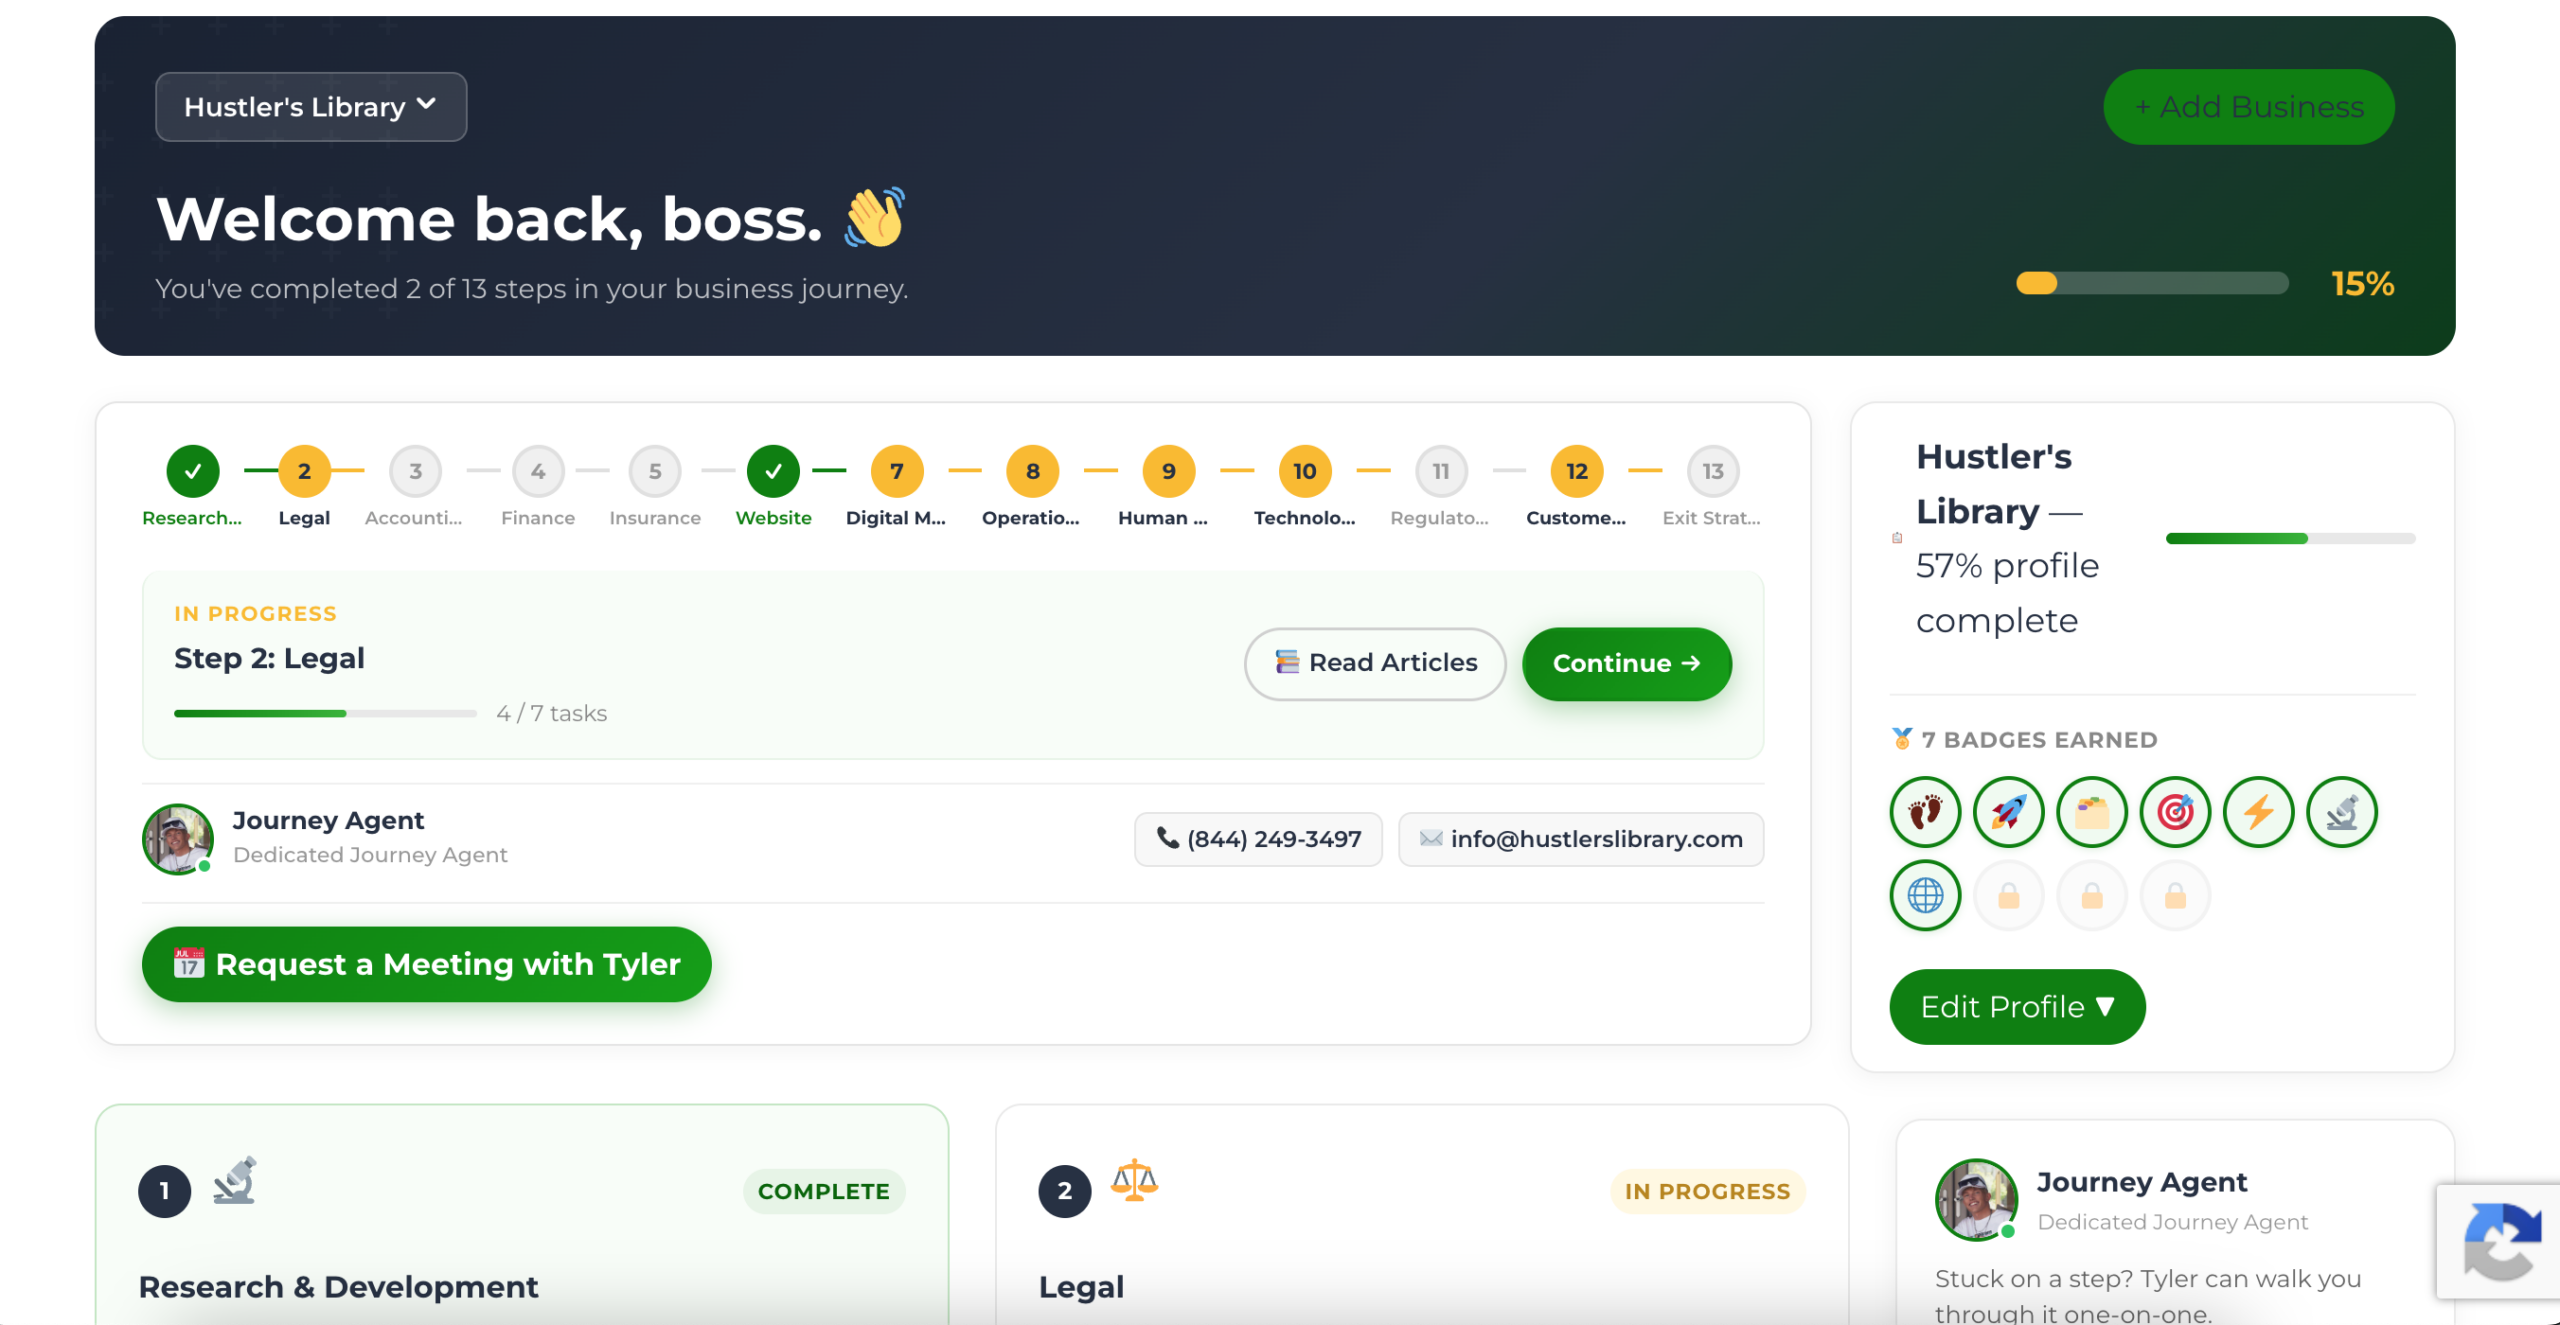
The Business Journey dashboard maps your exact position across all 13 stages. Track your progress, unlock resources for each step, and build with a framework used by thousands of founders at Hustler's Library.
No credit card required · Takes 3 minutes · Personalized to your stage