Most business owners spend years building something valuable, then walk into a sale negotiation without understanding one of the most fundamental deal structures in M&A: the difference between an asset sale and a stock sale. This single distinction affects your tax bill, your liability exposure, and how much money you actually walk away with. Learning it after you have already signed a letter of intent is too late.
What Is an Asset Sale?
In an asset sale, the buyer purchases specific assets from your business rather than buying the company itself. Those assets can include equipment, inventory, contracts, intellectual property, customer lists, goodwill, your phone number, your website, and your trade name. The seller retains the legal entity: the LLC or corporation stays in your name, along with any liabilities attached to it.
Think of it this way: the buyer is picking items off the shelf. They take what they want and leave the rest. Any lawsuits, unpaid taxes, pending warranties, or other legal exposure stays with you and your entity unless explicitly negotiated into the deal.
What Is Typically Included in an Asset Sale?
- Goodwill and trade name
- Customer lists and relationships
- Intellectual property: trademarks, patents, proprietary processes
- Equipment and furniture
- Inventory (sometimes at cost, sometimes negotiated separately)
- Contracts with vendors and customers (with assignment clauses)
- Website, domain, phone numbers, and social accounts
What Is Typically Excluded?
- Real estate (usually sold or leased separately)
- Cash and accounts receivable (retained by seller unless negotiated)
- Business bank accounts
- Pre-existing lawsuits or tax liabilities
- Personal guarantees on existing debt
What Is a Stock Sale?
In a stock sale (also called an equity sale for LLCs), the buyer purchases your ownership interest in the entity itself. They are not buying individual assets. They are buying the entire company: all assets, all contracts, all relationships, and all liabilities. Every lawsuit, every outstanding tax obligation, every employee issue comes with the deal.
The business simply changes hands. The legal entity continues operating with the same EIN, the same contracts, and the same history. For a buyer, this can be convenient in some ways: contracts do not need to be reassigned, licenses may transfer automatically, and there is less paperwork. But it also means they inherit everything, including the skeletons in the closet.
Why Buyers Prefer Asset Sales
The vast majority of buyers for small businesses prefer asset sales. Here is why:
No hidden liabilities. The buyer gets a clean slate. They are not inheriting your old employment disputes, vendor disagreements, or tax issues. What they buy is what they get.
Step-up in tax basis. When a buyer purchases assets, the purchase price gets allocated across those assets. This allows them to depreciate equipment and amortize goodwill at the new, higher purchase price, generating significant tax deductions in the years after closing. In a stock sale, they take your original cost basis, which may be much lower.
Selectivity. Buyers can exclude liabilities or assets they do not want. If your building has an environmental issue, they simply exclude it from the deal.
Why Sellers Prefer Stock Sales
Sellers almost universally prefer stock sales for tax reasons. In a stock sale, all proceeds are typically taxed as capital gains. If you have held your ownership stake for more than one year, you pay long-term capital gains rates, which max out at 20% federally, well below ordinary income rates.
In an asset sale, the tax picture is more complicated. Different asset categories get taxed differently. Goodwill and capital assets get capital gains treatment, but depreciation recapture on equipment is taxed as ordinary income. If you have been depreciating equipment for years, the IRS wants that depreciation back when you sell. This can meaningfully reduce your after-tax proceeds.
Stock sales also avoid double taxation for C-corporations. In an asset sale, a C-corp pays corporate tax on the gain, then shareholders pay personal tax when the proceeds are distributed. In a stock sale, shareholders are taxed only once at the personal level.
How Most Small Business Sales Actually Work
If you are selling a business under million in value, expect it to be structured as an asset sale. Buyers at this level are typically individuals or small operators taking on personal risk. They are not sophisticated enough to conduct deep due diligence on every potential liability, and even if they were, they are not willing to absorb unknown risk. Asset sales protect them.
The smaller the deal, the more leverage the buyer has on deal structure. Sellers who push hard for stock sale treatment on a 00K business will often find buyers simply walk away. Understanding this dynamic before you get to the table is critical. You can still negotiate tax allocations, price, and terms. But the structure itself is often non-negotiable at smaller deal sizes.
For businesses in the M to 5M range, you will find more flexibility. Private equity buyers and strategic acquirers may be willing to consider stock sales depending on the deal. At this level, legal counsel and tax advisors are not optional.
Negotiating the Asset Allocation
When an asset sale is agreed upon, both parties must complete IRS Form 8594 to allocate the purchase price across asset classes. The allocation matters enormously because it determines how each side is taxed.
Buyers want to allocate more to depreciable assets (equipment, inventory, covenant not to compete) because those generate faster deductions. Sellers want to allocate more to goodwill and capital assets because those generate more favorable capital gains treatment.
This is a genuine negotiating point in most deals. Your tax advisor should be at the table during these discussions, not reviewing the final documents after the fact.
Before you can negotiate the structure intelligently, you need a realistic picture of what your business is actually worth. Read our guide on how to value a business to understand the methods buyers use to price acquisitions, and then review how to sell your business for a complete walkthrough of the sale process.
For official IRS guidance on asset acquisitions and Form 8594, see the IRS Form 8594 instructions.
Ready to Build Smarter?
Get access to our full library of business guides, tools, and resources.
Ready to Know Where You Stand?
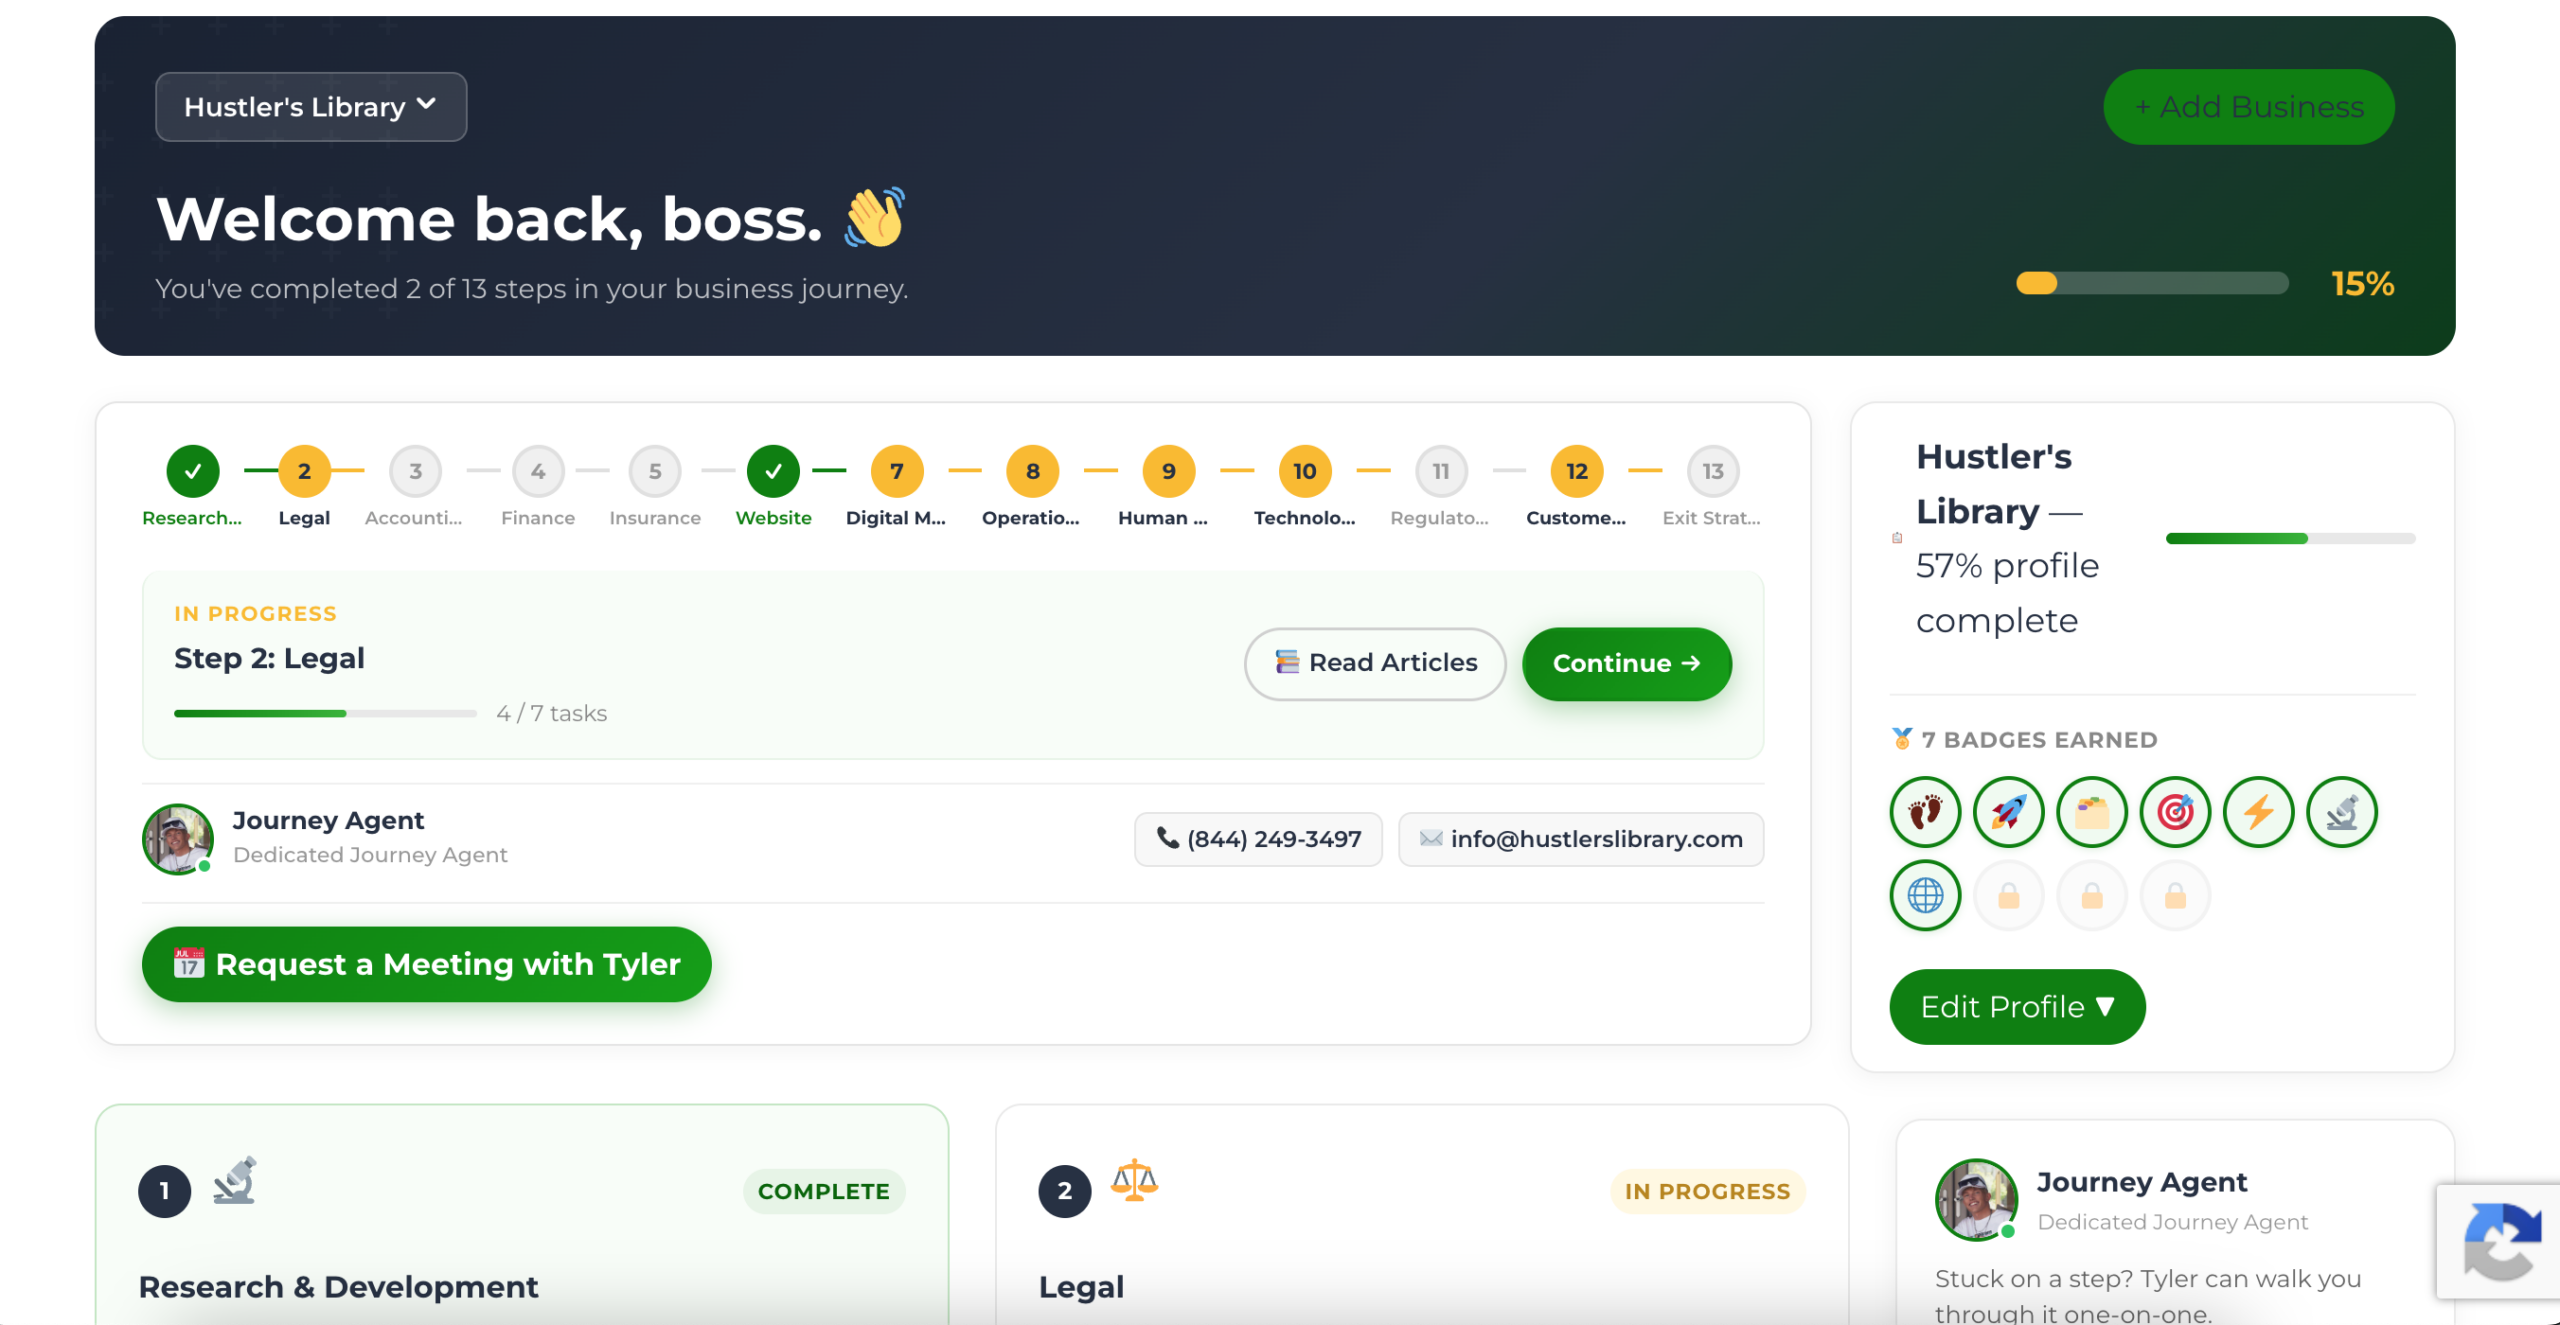
The Business Journey dashboard maps your exact position across all 13 stages. Track your progress, unlock resources for each step, and build with a framework used by thousands of founders at Hustler's Library.
No credit card required · Takes 3 minutes · Personalized to your stage