Opening a US business bank account is one of the most important steps you can take after forming your US company. It separates your business finances from your personal accounts, enables you to accept US dollar payments, and signals legitimacy to clients and partners. But for non-residents, the standard process at traditional banks does not work. Here is what actually does.
Why Traditional Banks Are Hard for Non-Residents
Walk into a Chase, Bank of America, or Wells Fargo branch and ask to open a business account, and the banker will ask for your Social Security Number (SSN), a physical US address, and in many cases a personal visit to the branch. As a non-resident founder living outside the US, you likely have none of these. This is not discrimination; it is the result of strict Know Your Customer (KYC) and Anti-Money Laundering (AML) regulations that banks are required to comply with under FinCEN guidelines. The FinCEN Customer Due Diligence rule requires banks to verify the beneficial owners of any business account, and for non-residents, satisfying that requirement remotely is something most traditional banks are not set up to do.
The Better Path: Remote-Friendly Banks
Several newer banks and fintech platforms have built their onboarding processes specifically to accommodate non-resident founders. The two most widely used by international startup founders are Mercury and Relay.
Mercury Bank
Mercury is a banking platform built for startups and tech companies. It accepts non-US residents with no SSN requirement; what you need is:
- A valid US business entity (LLC or C-Corp)
- Your EIN
- Formation documents (Articles of Organization or Certificate of Incorporation)
- A valid passport or government-issued ID
- A US address (your registered agent’s address works)
Mercury’s application is entirely online. Most accounts are approved within one to three business days. Mercury offers FDIC-insured accounts, no monthly fees, a Visa debit card, wire and ACH transfers, and a clean interface that integrates with accounting tools like QuickBooks and Xero. It is widely considered the default recommendation for international founders setting up US operations. Learn more at mercury.com.
Relay Bank
Relay is another strong option, particularly if you want to run multiple sub-accounts for budgeting or have a small team. Relay also accepts non-resident founders with an EIN and formation documents, and their application is fully remote. They offer up to 20 checking accounts under one business, physical and virtual debit cards, and no transaction fees. Relay is FDIC-insured through Thread Bank.
What Documents You Need
Regardless of which bank you choose, prepare the following before starting your application:
- EIN confirmation letter (CP 575 or 147C from the IRS)
- Formation documents filed with the state (stamped Articles of Organization or Certificate of Incorporation)
- Operating Agreement or Bylaws (some banks require this)
- Government-issued photo ID (passport is best)
- US business address (your registered agent’s address is acceptable)
- Beneficial ownership information (names and ownership percentages of anyone owning 25% or more)
Having clean, properly formatted documents speeds up approval significantly. If your EIN letter is on its way by mail and you need proof sooner, you can call the IRS to request a 147C letter by phone.
What to Do If You Get Rejected
Mercury and Relay approve the majority of non-resident applications, but rejections do happen. Common reasons include:
- Incomplete or mismatched formation documents
- Operating in a high-risk industry (crypto, cannabis, adult content, firearms)
- Unclear beneficial ownership structure
- Country of residence flagged for enhanced due diligence
If you are rejected by Mercury, try Relay, and vice versa. Other options to explore include Wise Business (good for multi-currency needs), Brex (targeted at startups with VC backing), and First Internet Bank. Each has different requirements and risk tolerances. For a broader overview of startup-focused credit options, our guide on Brex vs Ramp vs Divvy compares the major startup financial products side by side.
The SBA Perspective on Business Banking
The SBA’s guidance on opening a business bank account outlines the general requirements that any business account applicant should be prepared to meet. While the SBA guidance is written for US-based businesses, the core documentation requirements (EIN, formation documents, operating agreement) apply to foreign-owned entities as well. Use their checklist as a baseline and layer in the specific requirements of the bank you are applying to.
What Comes After Banking
Once your US business bank account is open, you have the infrastructure to operate professionally: accept payments, pay expenses, run payroll, and build a financial track record. That track record matters later if you pursue business credit, apply for funding, or need to demonstrate financial history to investors.
If you are building toward raising capital, understanding your full financial setup is critical. Our breakdown of how to start a company in the US as a foreign founder ties all of these pieces together in sequence.
Banking is a gatekeeper step, but it is a very passable one. With the right bank and the right documents, international founders open US business accounts every day without setting foot in the country.
Ready to build your US business the right way? Join Hustler’s Library free and get your personalised roadmap.
Services like LegalZoom can simplify the business formation process and help ensure your legal documents are filed correctly.
Ready to Know Where You Stand?
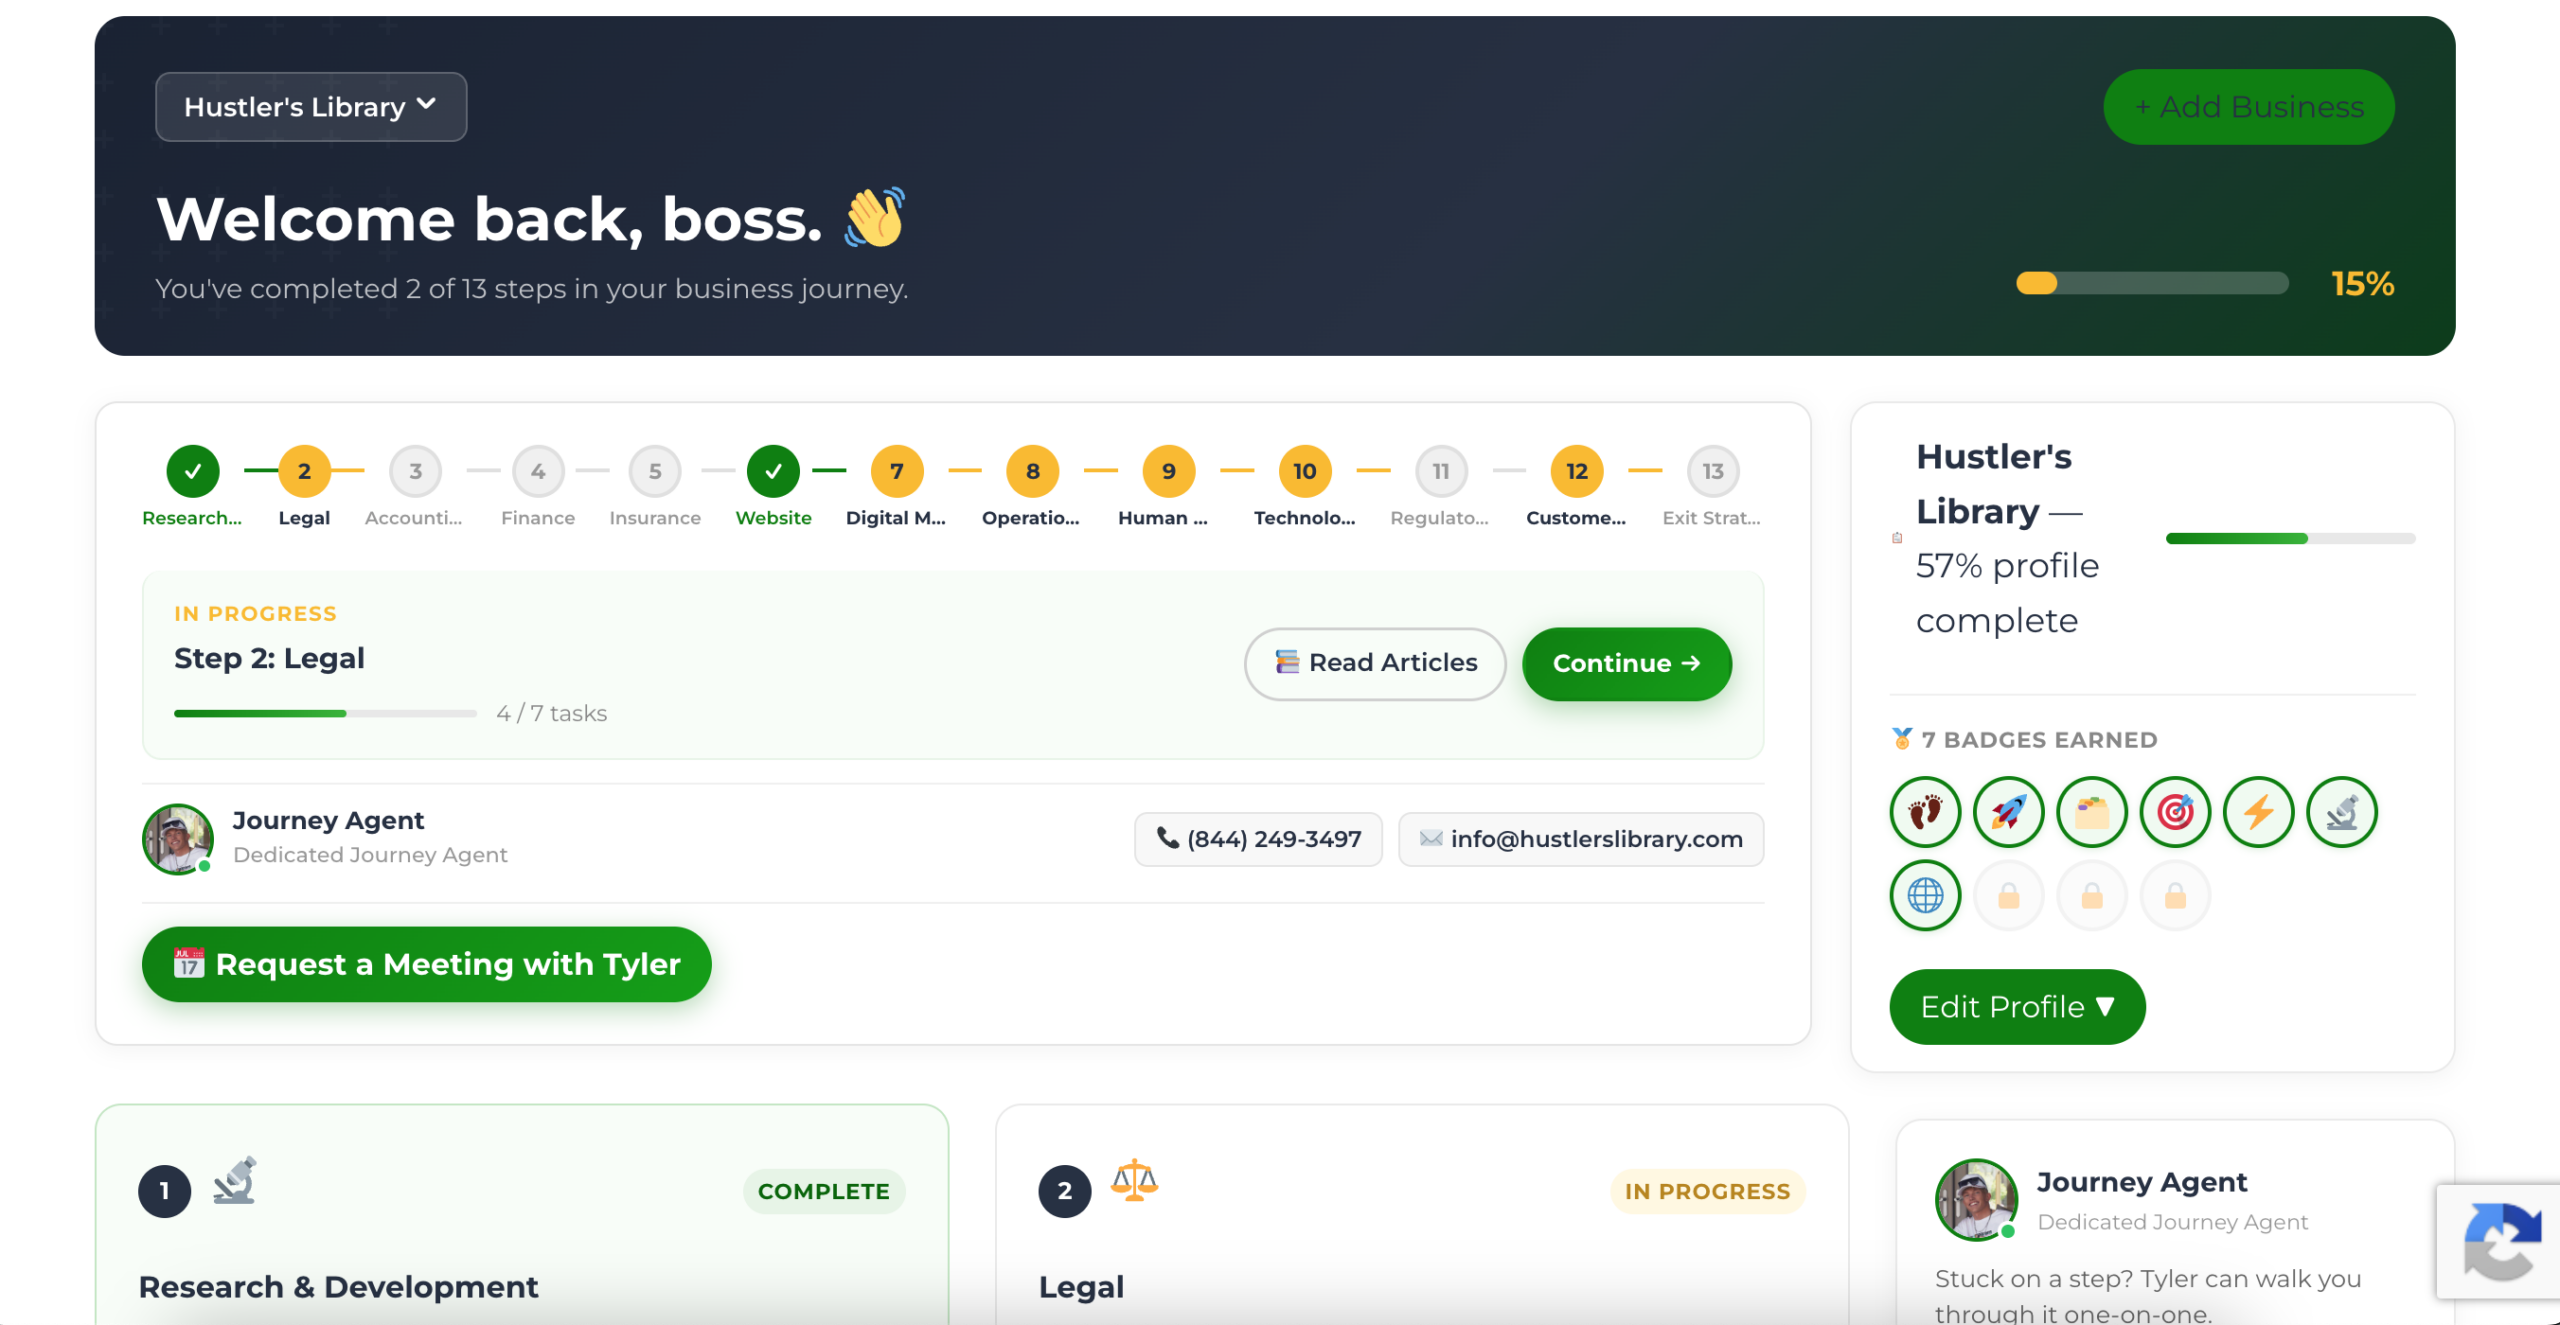
The Business Journey dashboard maps your exact position across all 13 stages. Track your progress, unlock resources for each step, and build with a framework used by thousands of founders at Hustler's Library.
No credit card required · Takes 3 minutes · Personalized to your stage