Most small businesses exist in a frustrating middle ground. They are too established and too profitable to qualify for a predatory merchant cash advance, but too small or too young to walk into a bank and get a traditional business loan. Fundbox was built specifically for that gap, and it has turned that niche into a profitable fintech operation powered by one key insight: cash flow data is a better predictor of repayment than a credit score.
What Fundbox Actually Is
Fundbox is a B2B financial services company that offers two core products: a revolving line of credit for small businesses and a B2B payments solution that lets companies pay their vendors now and spread the cost over time. It launched in 2013 and has extended over billion in credit to small businesses across the United States.
The company is not a bank. It is a technology-driven lender that uses software integrations, real-time cash flow analysis, and machine learning to make underwriting decisions in minutes rather than weeks. That speed and accessibility are central to its business model.
How Fundbox Makes Money: The Fee Model
Fundbox earns revenue primarily through draw fees on its revolving line of credit. When a business draws funds, it pays a flat fee rather than a traditional interest rate. The fee structure breaks down like this:
- 12-week repayment term: Typically around 4.66% of the drawn amount
- 24-week repayment term: Typically around 8.99% of the drawn amount
These fees are paid weekly over the term as the borrower repays the principal. The structure is straightforward: draw 0,000 on the 12-week plan, pay roughly 66 in total fees while repaying principal in equal weekly installments. There are no prepayment penalties, so businesses that repay early pay less in total fees.
On an annualized basis, these fees translate to APRs in the range of 15% to 50% depending on term and timing. That is significantly cheaper than most merchant cash advances, which routinely carry equivalent APRs of 40% to 150% or higher, but more expensive than a traditional bank line of credit at 7% to 12%.
Fundbox sits in the middle of the market by design: accessible like an MCA, but priced closer to a real loan.
The Underwriting Advantage: Cash Flow Over Credit Score
The core innovation at Fundbox is not the product itself. Lines of credit have existed for centuries. The innovation is in how Fundbox decides who gets one and for how much.
Traditional lenders rely heavily on personal credit scores, years in business, and tax returns. These are backward-looking signals that tell a lender what happened in the past. Fundbox takes a different approach. When a business applies, it connects its accounting software (QuickBooks, FreshBooks, Xero) or its business bank account directly to the Fundbox platform. The system ingests real-time transaction data and builds a dynamic picture of the business’s cash flow: how much money comes in, how regularly, from how many customers, and how predictable the pattern is.
This approach has several advantages:
- Speed: Decisions happen in minutes, not weeks, because the data analysis is automated.
- Accuracy: A business with a thin credit file but consistent invoicing is a better credit risk than its FICO score suggests.
- Access: Businesses that have been operating for as little as three months with at least 0,000 in annual revenue can qualify.
According to Federal Reserve data on small business credit access, roughly 40% of small businesses that apply for credit are denied or receive less than they requested. Fundbox targets the creditworthy portion of that rejected group.
The B2B Payments Product
Fundbox expanded beyond lending with its B2B payments solution, which operates on a similar principle. In B2B commerce, buyers frequently want extended payment terms (net 30, net 60, net 90) while sellers need cash now. This creates a cash flow gap that Fundbox fills.
With Fundbox Pay, a buyer can pay a vendor immediately while Fundbox extends credit to bridge the gap. The buyer repays Fundbox over the agreed term, paying the same draw-fee structure. The vendor gets paid immediately and does not have to chase invoices. Fundbox earns its fee from the buyer.
This product turns Fundbox into an embedded financial infrastructure layer within B2B supply chains, which is a stickier and more scalable position than consumer-facing lending.
Why Small Businesses Are the Target Market
Large banks have minimum thresholds. A 5,000 line of credit costs a bank nearly as much to underwrite as a 50,000 line, so they prefer larger deals. That leaves small businesses with genuine credit needs underserved.
Merchant cash advance companies fill some of that gap, but they do it predatorily: factor rates of 1.2x to 1.5x on the advance, daily ACH pulls from the business account, and no clear APR disclosure because they are structured as purchases of future receivables rather than loans.
Fundbox positions itself as the responsible middle option. It uses technology to underwrite small deals cheaply, which makes the unit economics work at loan sizes that banks ignore. If you are comparing your options, the full breakdown is worth reading: Emergency Business Funding: Every Option Ranked by Speed and Cost.
Risk Model and Loss Rates
Every lender lives and dies by its loss rates. Fundbox’s edge is that its cash-flow underwriting model, trained on millions of data points from connected accounts, is better at predicting default than traditional credit scoring for the small business segment.
When a business has predictable weekly deposits from multiple clients, that is a strong signal of stability. When those deposits are from a single client, or when they are irregular and declining, that raises flags. Fundbox’s algorithms weight these patterns dynamically, which means the credit limit offered to a business can increase or decrease over time as the underlying data changes.
This dynamic adjustment also protects Fundbox during downturns. If a business’s cash flow deteriorates, the platform can reduce available credit before the business draws more than it can repay.
Also relevant: Kabbage and other fast lenders
Fundbox is not the only player in this space. The fast-lending market includes names like OnDeck, BlueVine, and Kabbage (now Amex Business Blueprint). Each has a slightly different model and fee structure. For a full comparison, see: Kabbage vs OnDeck vs Fundbox: Best Fast Business Loans Compared.
The Entrepreneur Takeaway
If you run a business with consistent invoicing and real cash flow, you are a better credit risk than your FICO score may show. Cash-flow lenders like Fundbox can recognize that and price it accordingly. The fees are not cheap compared to a bank, but they are transparent, predictable, and often significantly better than the MCA your broker is trying to sell you.
The lesson is not to reflexively use Fundbox. The lesson is to understand that the lending market has multiple tiers, and your access to better rates often depends on whether you can show real cash flow data. Connect your accounting software, know your numbers, and you become a more attractive borrower across every category.
For any business considering fast capital, the math of annualized costs matters more than the headline fee. A 4.66% draw fee sounds modest. Across 12 weeks it works out to roughly 20% APR. That is the number to compare against your alternatives.
Ready to Build Smarter?
Get access to our full library of business guides, tools, and resources.
Ready to Know Where You Stand?
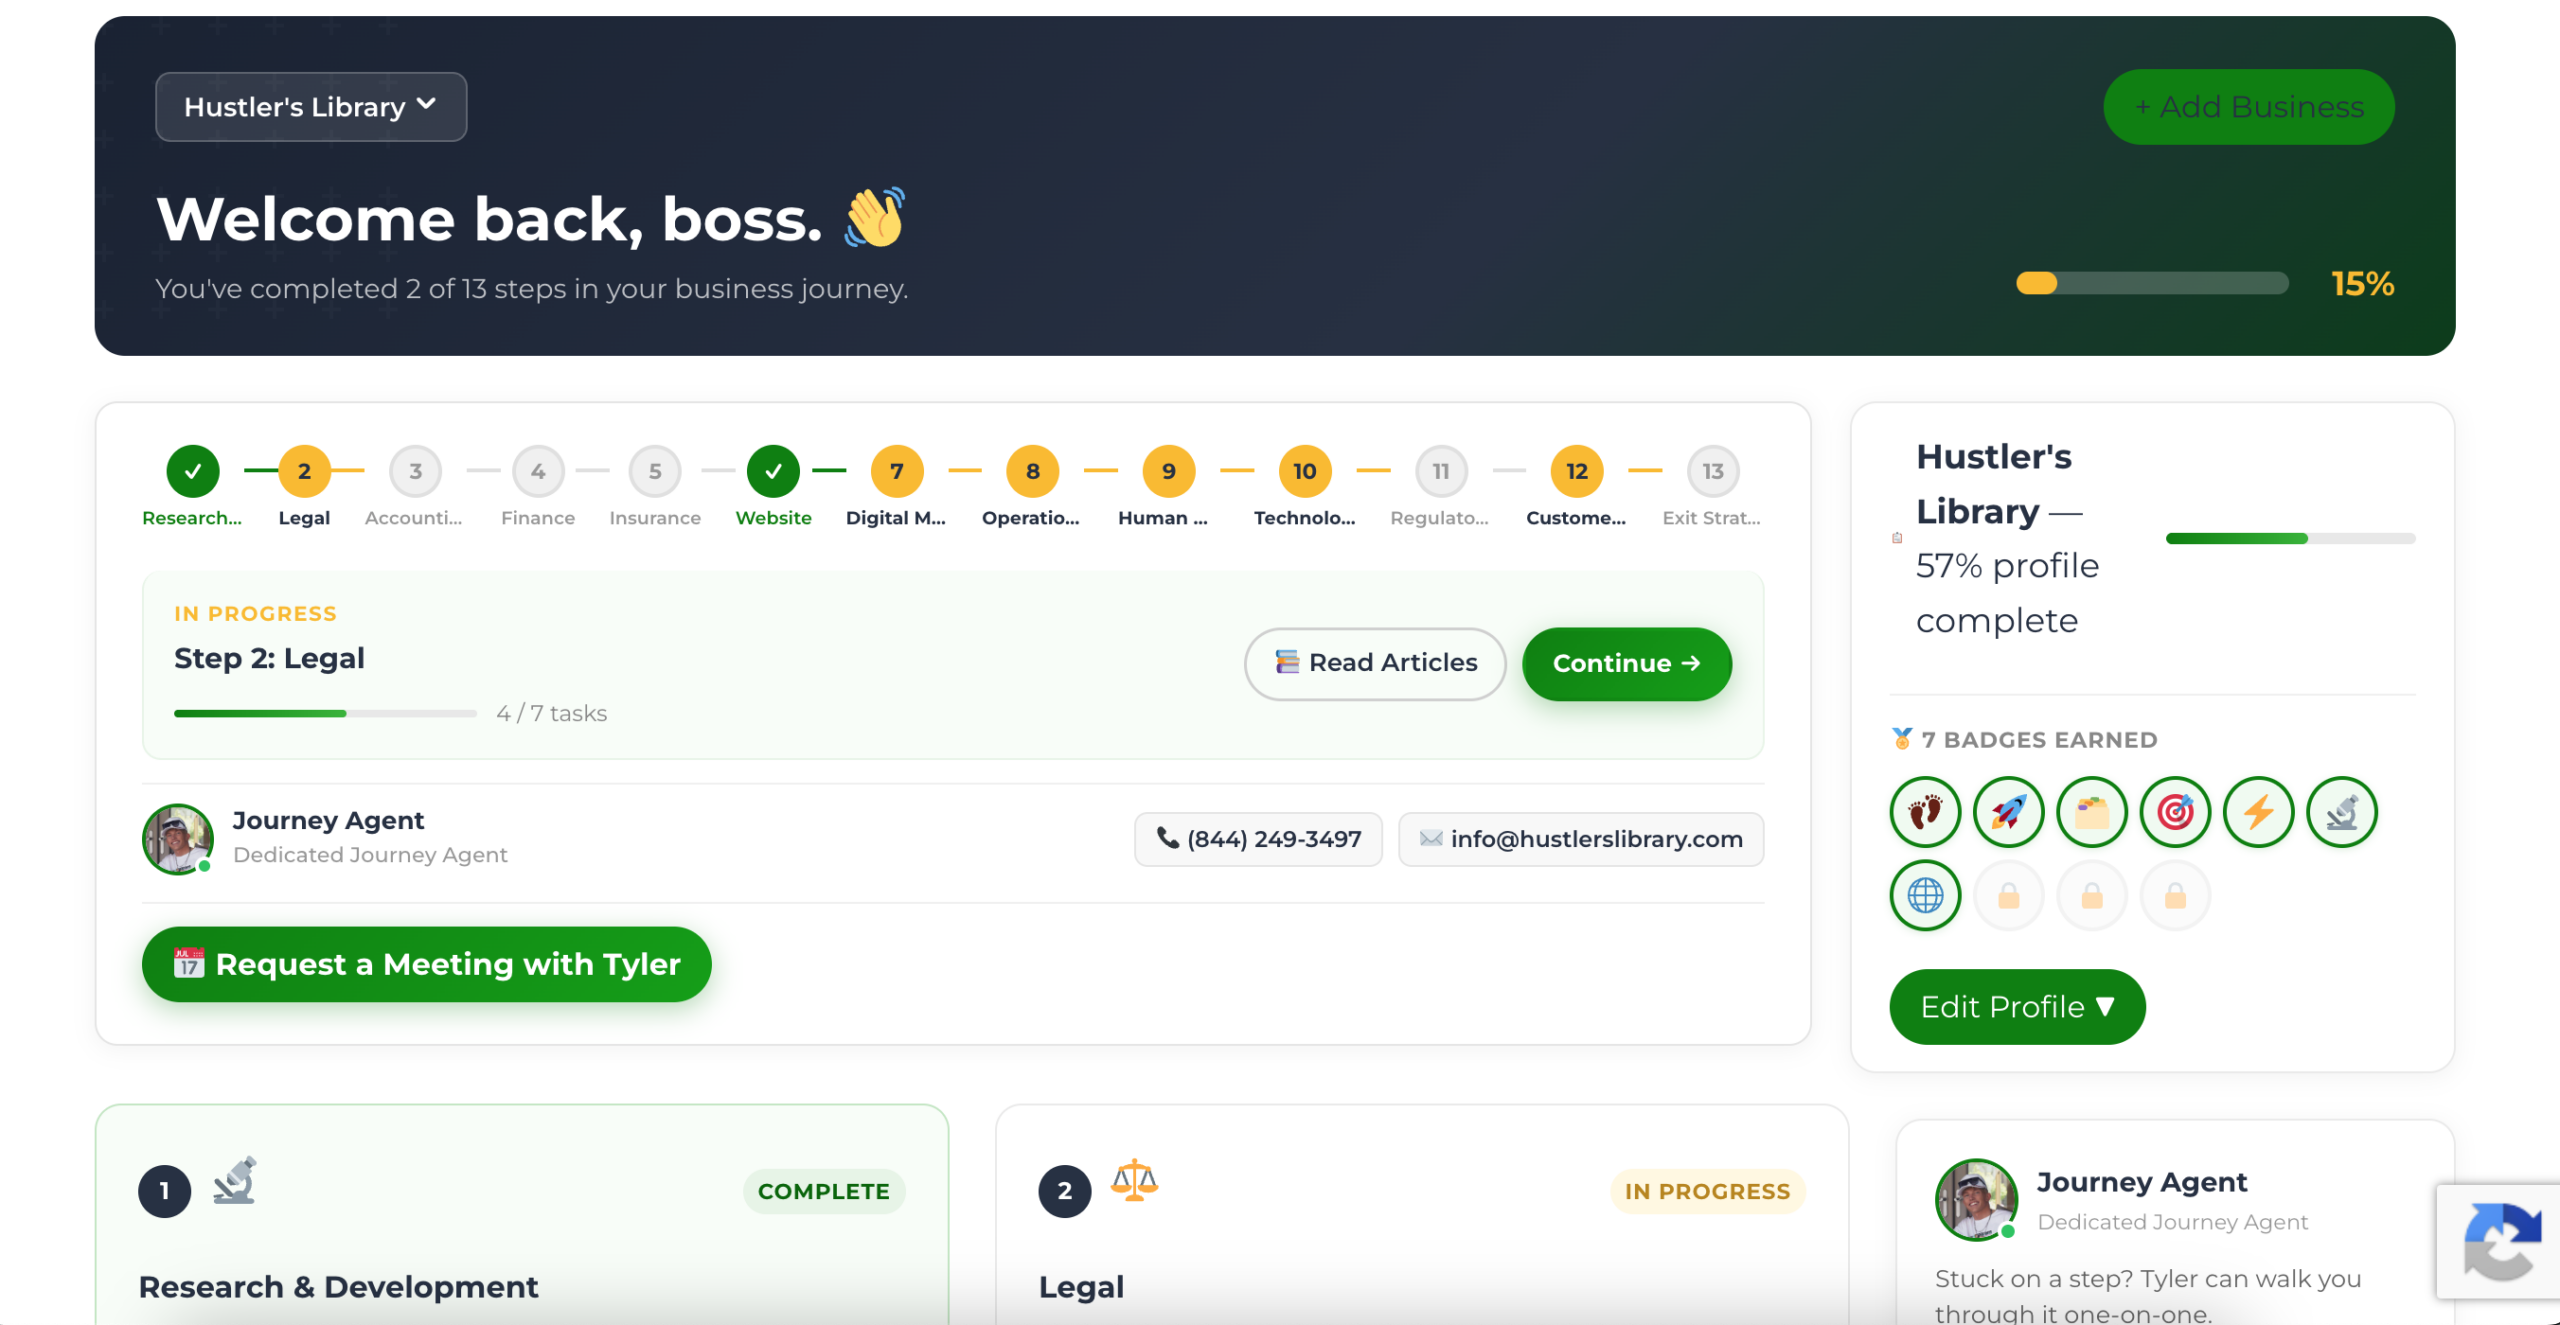
The Business Journey dashboard maps your exact position across all 13 stages. Track your progress, unlock resources for each step, and build with a framework used by thousands of founders at Hustler's Library.
No credit card required · Takes 3 minutes · Personalized to your stage