One of the first decisions every business owner faces is choosing a legal structure. The structure you choose determines how you pay taxes, whether your personal assets are protected from business liability, how you bring in investors or partners, and how complicated your operations will become as you grow. This guide covers all seven types of business structures in plain language, with a clear recommendation at the end for which structure fits which situation.
Why Your Business Structure Matters More Than You Think
Most first-time founders pick a structure without thinking it through, often because someone told them to form an LLC or because they saw their structure on a form and clicked it. That works until it does not. Choosing the wrong structure can mean paying unnecessary taxes, losing personal liability protection, or being unable to raise outside funding when the opportunity arises.
Get this decision right early, and you will avoid costly restructuring later.
The 7 Types of Business Structures
1. Sole Proprietorship
Best for: Freelancers, consultants, and early-stage testing before committing to a formal structure.
Tax treatment: All business income flows directly to your personal tax return (Schedule C). No separate business tax filing required.
Key downside: Zero liability protection. If your business is sued or cannot pay its debts, your personal assets, including your home, savings, and car, are on the line.
A sole proprietorship requires no formal registration. You are simply operating as yourself. It is the default structure for anyone who does not form a separate entity. This works fine for low-risk, low-revenue activity, but you should graduate out of it as soon as your business generates meaningful income or faces any customer-facing liability.
2. General Partnership
Best for: Two or more people testing a business concept informally, or professional service firms where both parties are actively involved.
Tax treatment: Pass-through taxation. Each partner reports their share of income and losses on their personal return. The partnership files an informational return (Form 1065) but does not pay entity-level tax.
Key downside: Each partner is personally liable for the actions of the other partners. If your partner makes a bad business decision or gets sued, you share that liability equally. Never operate as a general partnership without a written partnership agreement.
3. Limited Partnership (LP)
Best for: Real estate investment deals, private equity structures, and investment funds with passive investors.
Tax treatment: Pass-through. The general partner manages the business and bears unlimited liability. Limited partners are passive investors whose liability is limited to their investment.
Key downside: The general partner retains full personal liability. Most general partners hold their GP interest through an LLC to solve this problem. LPs are not typically used for operating businesses because of their complexity.
4. Limited Liability Company (LLC)
Best for: The majority of small businesses, from solo operators to multi-owner companies.
Tax treatment: Flexible. A single-member LLC is taxed as a sole proprietorship by default. A multi-member LLC is taxed as a partnership. Either can elect S-Corp taxation with the IRS for potential savings. LLCs can also elect to be taxed as a C-Corporation.
Key downside: Not ideal for venture-backed startups because VCs prefer C-Corporations for legal and structural reasons. Also, self-employment taxes apply to active members unless an S-Corp election is made.
The LLC is the most popular business structure for small businesses in the United States for good reason. It is simple to form, provides meaningful liability protection, and offers tax flexibility that no other structure matches. If you are not sure what to form, start here.
5. S-Corporation
Best for: Profitable service businesses, including consulting firms, agencies, medical practices, and similar operations where the owner takes active income from the business.
Tax treatment: Pass-through, but with a meaningful tax advantage. The owner takes a reasonable salary (subject to payroll taxes) and can distribute additional profits as distributions not subject to self-employment tax. This split can generate significant savings for businesses earning 0,000 or more in net profit.
Key downside: Requires running actual payroll, quarterly filings, and compliance with IRS reasonable compensation rules. Capped at 100 shareholders, and shareholders must be U.S. citizens or residents. Not compatible with VC investment.
An S-Corp is not a separate entity type in most states; it is a tax election made with the IRS. You form an LLC or a C-Corporation first, then file Form 2553 to elect S-Corp status. For profitable owner-operators, this is often the single biggest tax planning move available.
The IRS provides detailed guidance on S-Corp requirements at IRS.gov.
6. C-Corporation
Best for: Startups planning to raise venture capital, businesses planning an IPO, and any company that needs to issue multiple classes of stock.
Tax treatment: The C-Corp pays taxes at the entity level (currently 21% federal corporate tax rate). Profits distributed to shareholders as dividends are taxed again at the individual level. This is the so-called double taxation. However, most VC-backed startups reinvest profits rather than paying dividends, so double taxation is rarely the practical concern it sounds like for early-stage companies.
Key downside: More administrative overhead, more expensive to maintain, and potentially higher taxes for small profitable businesses that would be better served by a pass-through structure.
Delaware is the default state for C-Corporation formation for startups because of its well-developed corporate law, specialized courts, and investor familiarity. If you plan to raise from institutional investors, form a Delaware C-Corp from the beginning.
7. Nonprofit 501(c)(3)
Best for: Organizations with a charitable, educational, religious, or other public benefit mission that qualifies under IRS rules.
Tax treatment: Exempt from federal income tax on qualifying activities. Donors can deduct contributions. The organization cannot distribute profits to individuals; all surplus must be reinvested into the mission.
Key downside: Significant ongoing compliance requirements, including annual IRS filings (Form 990), required board of directors, and strict limitations on political activity and private benefit. Formation typically requires an attorney and takes several months to receive IRS determination.
Nonprofits are not tax-free businesses. They are mission-driven organizations subject to specific rules. If you are trying to minimize taxes on a for-profit operation, this is not the path.
Comparison Table: All 7 Structures at a Glance
| Structure | Liability Protection | Tax Treatment | Best For | Key Downside |
|---|---|---|---|---|
| Sole Proprietorship | None | Personal return (Sch. C) | Early testing, freelancers | Full personal liability |
| General Partnership | None | Pass-through (Form 1065) | Informal co-ventures | Partners liable for each other |
| Limited Partnership | LP investors protected; GP is not | Pass-through | Real estate, investment funds | GP holds full liability |
| LLC | Yes | Flexible (default or S/C election) | Most small businesses | Not VC-compatible by default |
| S-Corporation | Yes | Pass-through, payroll split | Profitable service businesses | Payroll required; 100 shareholder cap |
| C-Corporation | Yes | Entity-level + dividend tax | VC-backed startups | Double taxation, higher overhead |
| Nonprofit 501(c)(3) | Yes (directors) | Tax-exempt on qualifying activity | Charitable/public benefit orgs | No profit distribution; heavy compliance |
The Clear Recommendation
For the vast majority of small business owners, the LLC is the right choice. It is straightforward to form in any state, provides meaningful personal liability protection, and gives you tax flexibility that you can optimize as the business grows. If your business becomes profitable enough, adding an S-Corp tax election on top of your LLC can save you thousands in self-employment taxes each year.
If you are building a startup with plans to raise money from venture capital investors, form a Delaware C-Corporation from day one. Trying to convert an LLC to a C-Corp after you have already started raising money creates legal and tax complications that are expensive to unwind.
For everything else, including service businesses, retail operations, real estate, e-commerce, and consulting, the LLC with optional S-Corp election covers almost every scenario without the overhead of a C-Corp.
If you are just getting started, our guide on getting your EIN covers the next step after forming your entity. And if you are thinking about how your structure affects your ability to get business funding, our guide on SBA loans explained is a natural next read.
The Bottom Line
Your business structure is the legal foundation everything else is built on. Take the time to choose correctly rather than defaulting to whatever is easiest at the moment. For most people reading this, that means forming an LLC. For startup founders seeking VC funding, it means a Delaware C-Corp. For profitable owner-operators, it means an LLC with an S-Corp election. Everything else is a special case.
When in doubt, spend an hour with a business attorney or CPA before you file. The cost of a consultation is nothing compared to the cost of restructuring after the fact.
Ready to Build Smarter?
Get access to our full library of business guides, tools, and resources.
Services like LegalZoom can simplify the business formation process and help ensure your legal documents are filed correctly.
Ready to Know Where You Stand?
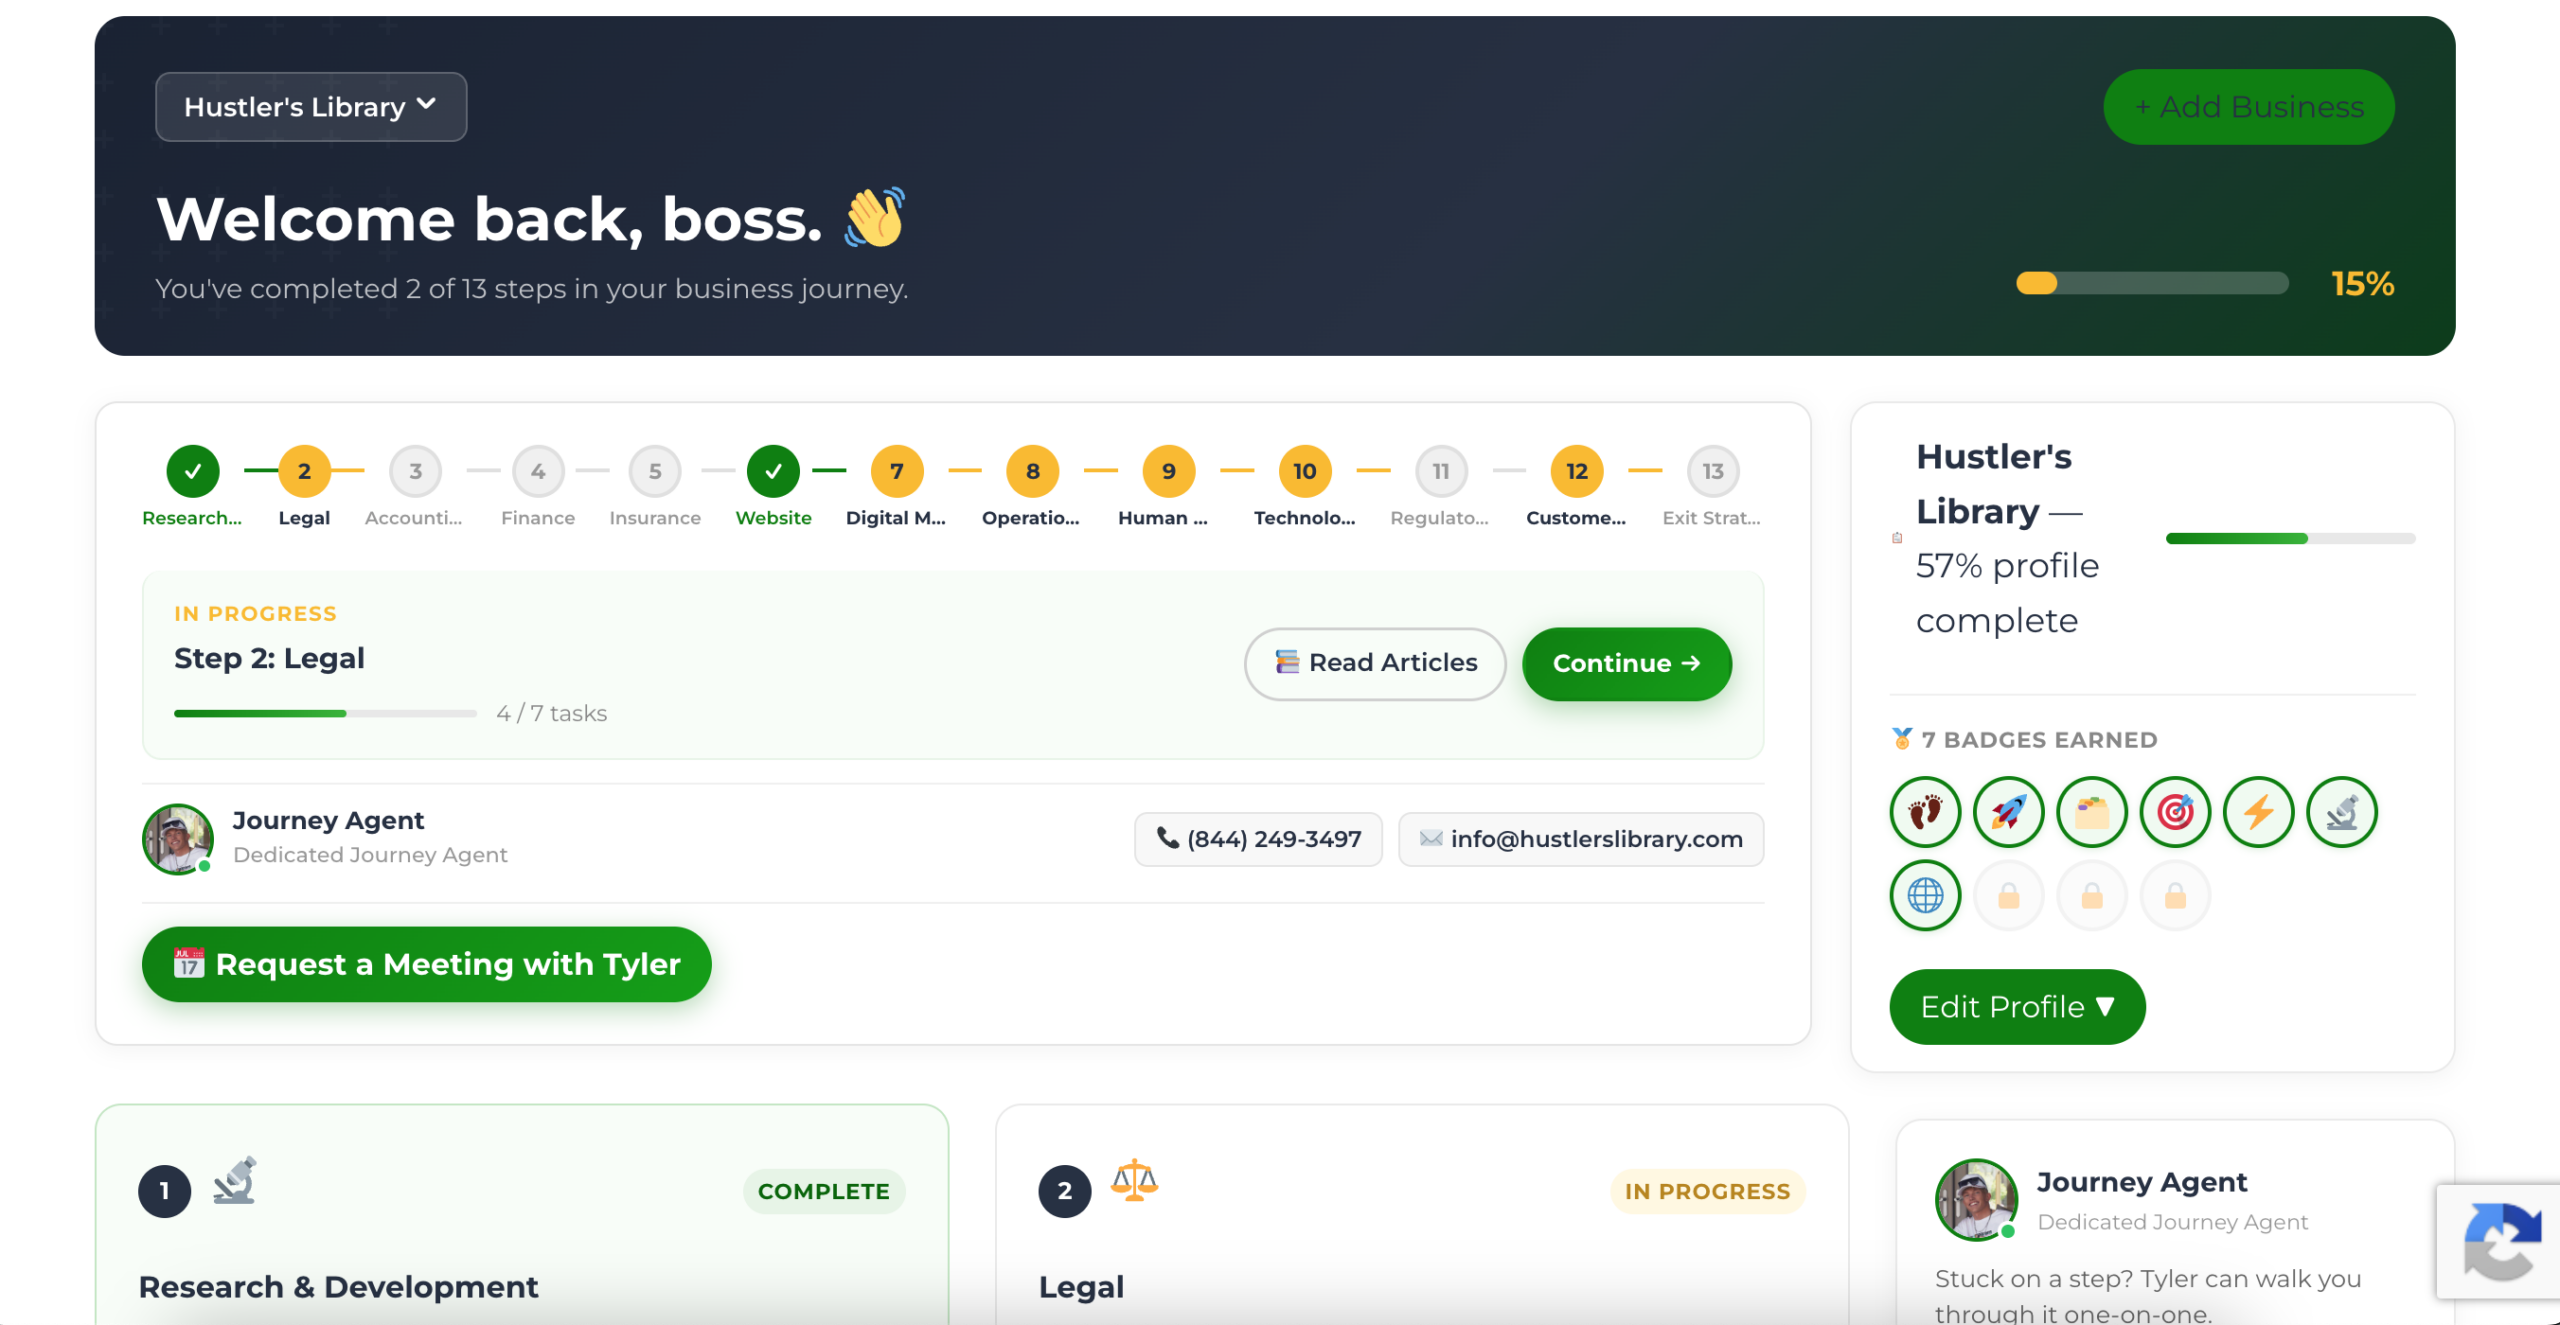
The Business Journey dashboard maps your exact position across all 13 stages. Track your progress, unlock resources for each step, and build with a framework used by thousands of founders at Hustler's Library.
No credit card required · Takes 3 minutes · Personalized to your stage