If you’ve ever Googled “health insurance for small business owners,” you already know the problem: the results are either designed for HR departments at 500-person companies or so vague they’re useless. What you actually need is a plain-English breakdown of your real options, what they cost, and how to make a decision that doesn’t leave you or your employees out in the cold.
This guide covers everything a small business owner needs to know about health insurance in 2026, from solo options to group plans to alternatives that might work better than you’d expect.
First, Clarify Your Situation
Health insurance looks completely different depending on whether you’re a:
- Solo business owner with no employees (self-employed, sole proprietor, single-member LLC)
- Small business owner with 1 to 50 employees
- Small business owner who wants to offer benefits to attract and keep talent
Each situation has different leverage, different legal requirements, and different cost structures. Don’t waste time researching options that don’t apply to you.
Option 1: The Health Insurance Marketplace (For Solo Owners)
If you’re self-employed with no employees, the ACA Marketplace (healthcare.gov) is your starting point. You can buy an individual or family plan there, and depending on your reported income, you may qualify for premium tax credits that significantly lower your monthly cost.
What most owners miss: self-employed individuals can deduct 100% of health insurance premiums paid for themselves and their families from their federal taxes. That deduction is above-the-line, meaning you don’t need to itemize to claim it. Over a year, this can make a plan that looks expensive feel a lot more manageable.
Key tip: Open enrollment runs from November 1 through January 15 for most states. If you miss it, you’ll need a qualifying life event (like losing other coverage or getting married) to enroll outside that window.
Option 2: Group Health Plans (For Businesses With Employees)
If you have employees, a traditional group health plan is the most well-known option. You purchase coverage through a private insurer or broker, and you typically share the premium cost with your employees. Most insurers require at least two eligible employees to qualify for a group plan.
Group plans have real advantages: broader networks, lower per-person premiums, and the ability to offer a benefit that genuinely helps you recruit and retain people. But they also come with costs and administrative complexity that can be overwhelming if you’re running lean.
Expect to pay anywhere from $400 to $800+ per employee per month depending on your location, the plan tier, and how much your employees contribute. Health insurance is one of the hidden costs of small business that can blindside owners who don’t plan for it in their operating budget.
Option 3: QSEHRA and ICHRA (The Flexible Alternatives)
These two options have become increasingly popular with small businesses, and for good reason. Both let you reimburse employees for individual health insurance costs without running a traditional group plan.
QSEHRA (Qualified Small Employer Health Reimbursement Arrangement)
Available to businesses with fewer than 50 full-time equivalent employees that don’t offer a group health plan. You set a monthly reimbursement cap, employees buy their own individual plans, and you reimburse them tax-free up to that cap. In 2024, the limits were $6,150 per year for self-only coverage and $12,450 for family coverage (amounts adjust annually).
The benefit: you control exactly how much you spend. The limitation: all employees must be offered the same reimbursement amount (though you can vary it by family status).
ICHRA (Individual Coverage Health Reimbursement Arrangement)
The ICHRA is more flexible. There’s no cap on reimbursement amounts, and you can set different allowances for different classes of employees (full-time, part-time, seasonal, etc.). Any size business can offer one. Employees use the money to buy their own ACA-qualified plans.
This model works especially well for businesses with a mixed workforce or owners who want predictable, budgetable healthcare costs without the headaches of administering a group plan.
Option 4: Health Sharing Plans
Health sharing plans (sometimes called health sharing ministries) are not insurance, but they function similarly for many routine and major medical needs. Members pay a monthly share, and the pool is used to cover eligible medical costs across the membership.
Monthly costs are typically 30 to 50% lower than ACA plans, which makes them attractive. But the tradeoffs are real: pre-existing conditions may not be covered, mental health coverage is often limited, and there’s no legal guarantee that costs will be paid. These plans work for some business owners and are genuinely risky for others. Do your research carefully before committing.
Option 5: Professional Employer Organizations (PEOs)
A Professional Employer Organization essentially co-employs your team and bundles HR services, payroll, and benefits, including health insurance, into one package. Because PEOs pool employees from many small businesses, they can access group insurance rates that a 5- or 10-person company could never get on its own.
For small businesses trying to offer competitive benefits without a full HR department, PEOs can be a smart option. Popular providers include Justworks, Gusto, TriNet, and Rippling. Costs vary but are typically a per-employee monthly fee on top of your payroll.
What About the ACA Small Business Tax Credit?
If you have fewer than 25 full-time equivalent employees, pay average wages below a certain threshold, and cover at least 50% of employee premium costs through a SHOP Marketplace plan, you may qualify for the Small Business Health Care Tax Credit. The maximum credit is 50% of premiums paid for small business employers (35% for tax-exempt employers).
In practice, the credit phases out as your workforce and wages grow, so it’s most valuable for the smallest businesses with lower-wage employees. Check IRS Form 8941 and consult your accountant to see if it applies to you.
How to Actually Make the Decision
There’s no universal right answer. Here’s a simple framework:
- Solo owner, no employees: Start with the ACA Marketplace, maximize your self-employed premium deduction, and consider pairing a high-deductible plan with an HSA to reduce taxable income further.
- Small team, tight budget: Look at QSEHRA or ICHRA. You get the benefit of offering health support without the unpredictable cost of a group plan.
- Growing team, want to compete for talent: A traditional group plan or PEO gives you the strongest benefit package. Health insurance is one of the top reasons employees stay at or leave small businesses in a competitive labor market.
- Want predictable costs above all else: ICHRA gives you a fixed monthly commitment per employee class. No surprises.
Whatever route you take, building a competitive compensation package that includes health benefits, even a reimbursement-based one, signals to your team that you’re serious about their wellbeing, not just their productivity.
Don’t Sleep on an HSA
If you choose a High Deductible Health Plan (HDHP), you become eligible to open a Health Savings Account (HSA). Contributions are tax-deductible, growth is tax-free, and withdrawals for qualified medical expenses are tax-free. It’s essentially a triple-tax-advantaged account, and it rolls over year to year with no use-it-or-lose-it rule.
For business owners who are relatively healthy and want to minimize current tax burden while building a reserve for future medical costs, an HDHP paired with a funded HSA is one of the smartest financial moves available.
Work With a Broker (It’s Free)
One of the most common mistakes small business owners make is trying to navigate health insurance alone. Licensed health insurance brokers are paid by the insurer, not by you, so their advice costs you nothing. A good broker will compare plans across carriers, explain what’s actually covered, help you set up a QSEHRA or ICHRA, and handle enrollment logistics for your team.
Look for brokers who specialize in small business health plans specifically. A broker who mostly works with large employers may not know the small-group market as well.
The Bottom Line
Health insurance is one of the most significant financial decisions you’ll make as a business owner, whether you’re buying for yourself or for a team. The good news is that the options have genuinely expanded over the last several years. ICHRA and QSEHRA have given small business owners flexibility that didn’t exist a decade ago, and PEOs have made competitive group benefits accessible to companies of almost any size.
The key is matching the option to your actual situation, your headcount, your budget, your growth trajectory, and how much you’re willing to manage administratively. Don’t default to what your neighbor’s business does. Make a deliberate choice.
Want more plain-English guides to running a smarter, stronger small business? Join Hustler’s Library free and get the tools and strategies that actually move the needle.
Ready to Know Where You Stand?
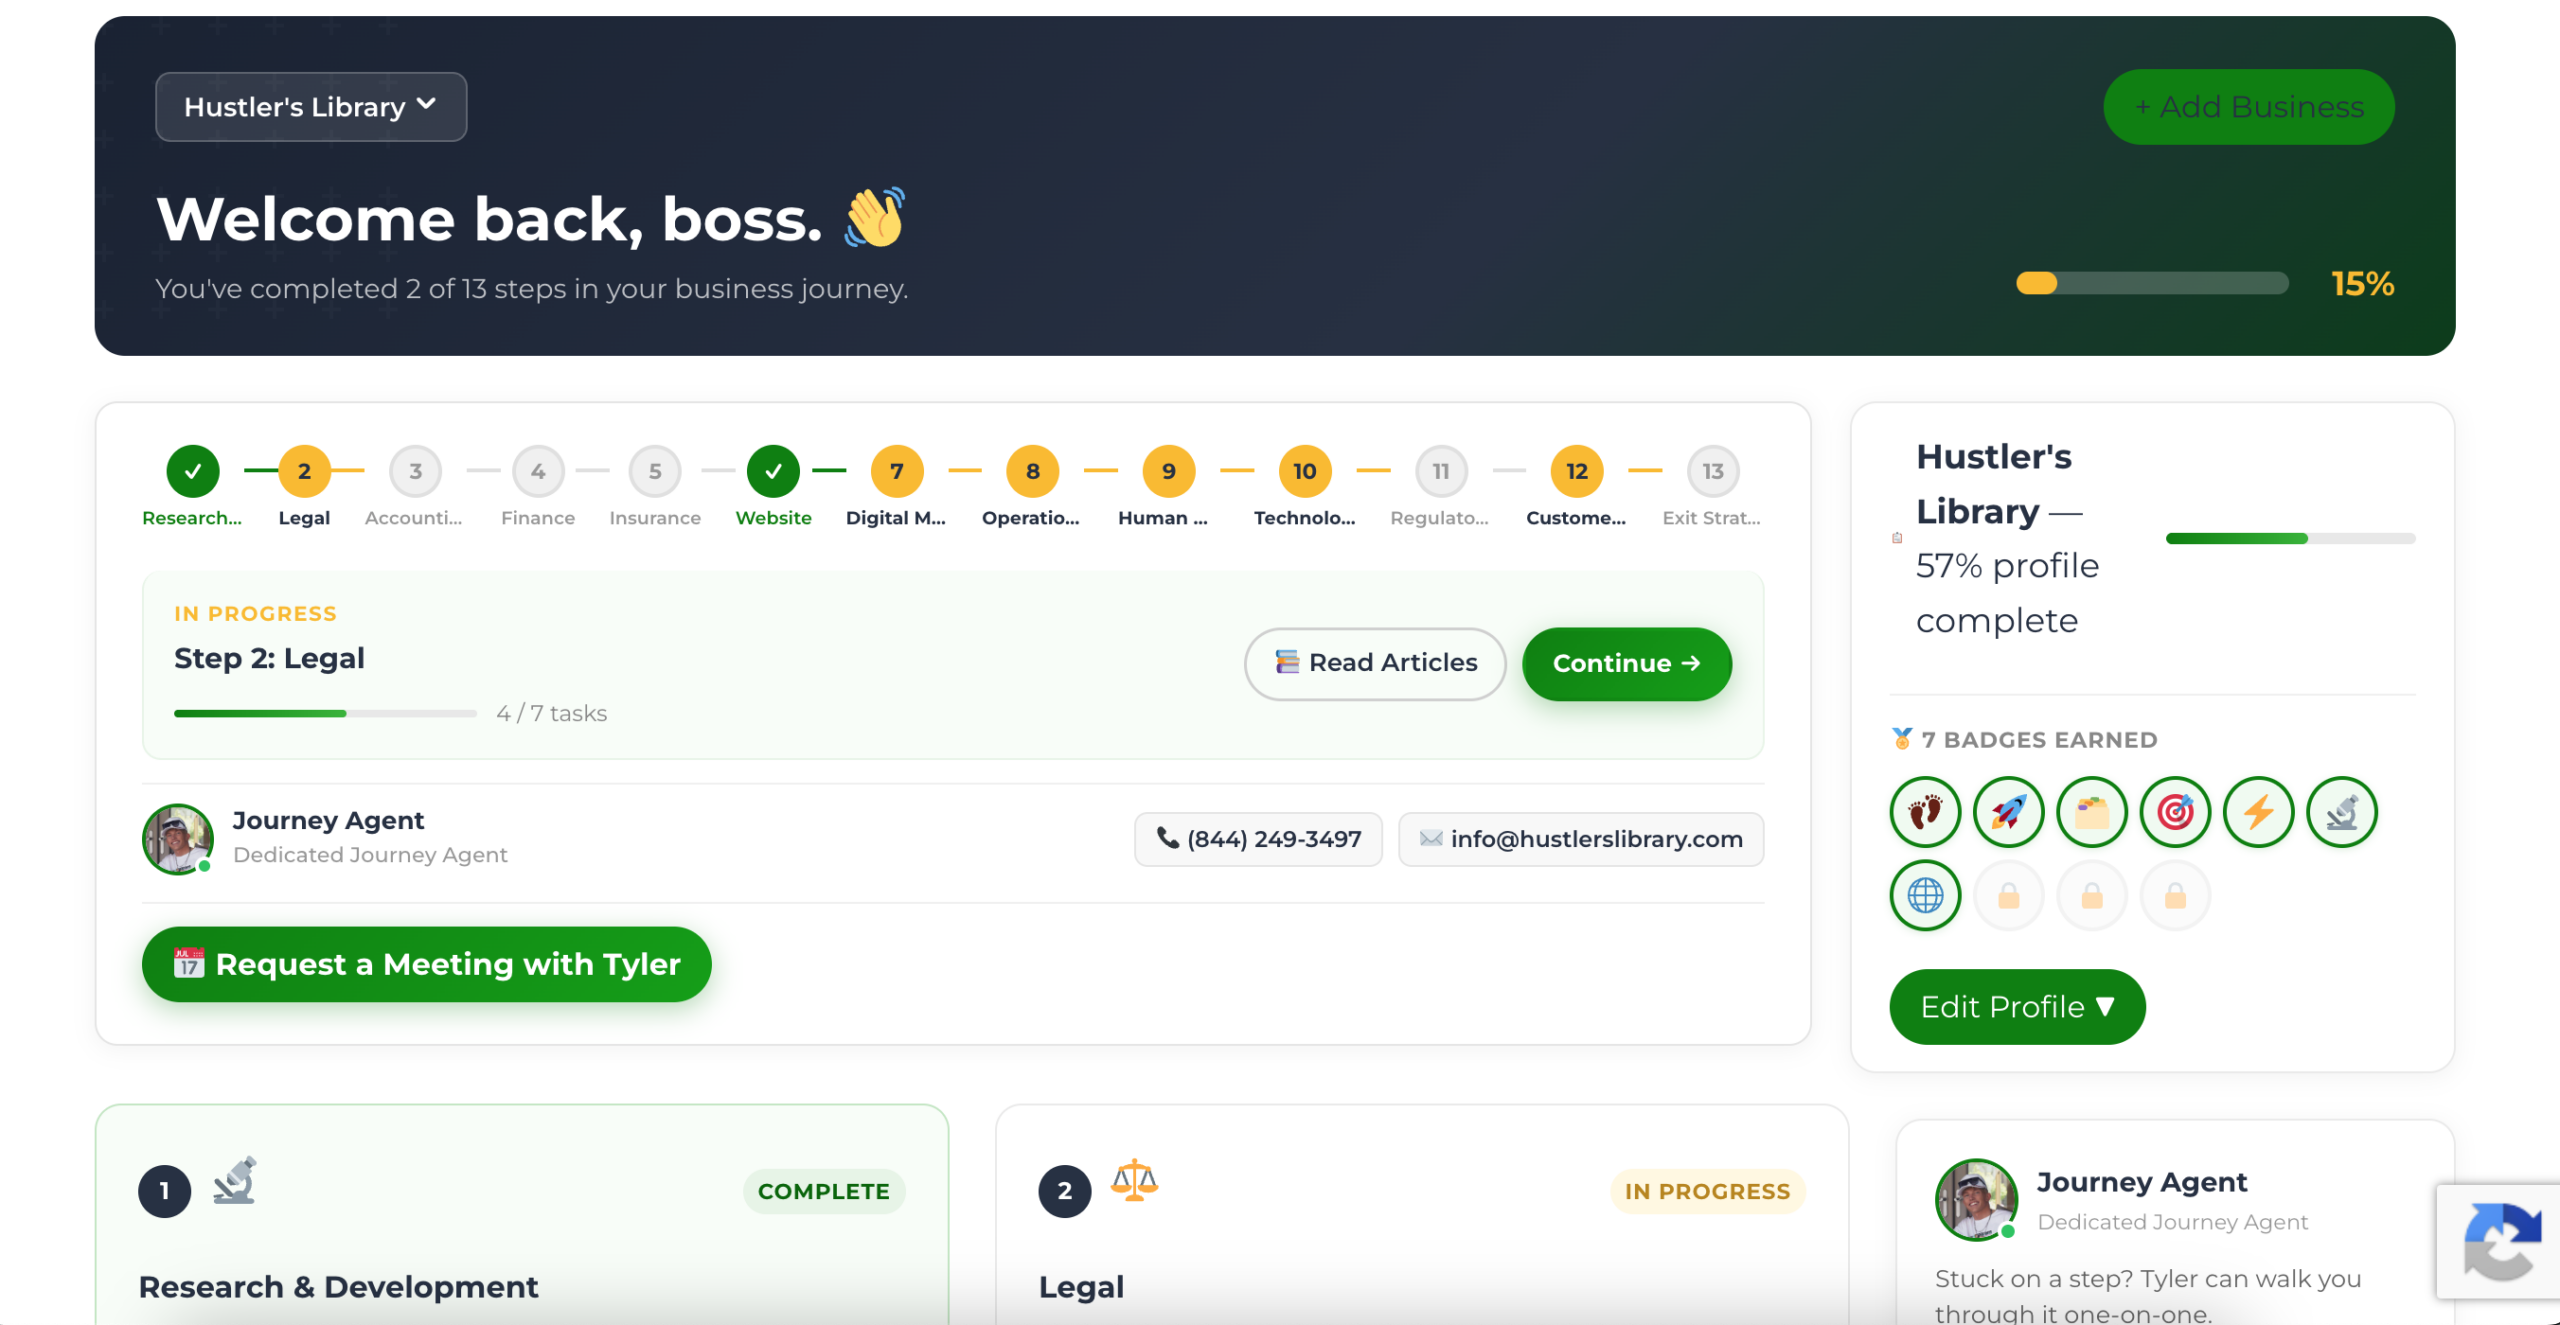
The Business Journey dashboard maps your exact position across all 13 stages. Track your progress, unlock resources for each step, and build with a framework used by thousands of founders at Hustler's Library.
No credit card required · Takes 3 minutes · Personalized to your stage