The Question That Keeps Small Business Owners Up at Night
You’ve outgrown your home office. The co-working space is getting cramped. Your clients are starting to ask where you’re located. The question hanging over your head: do you rent a commercial space or take the plunge and buy?
It’s one of the biggest financial decisions a small business owner will ever make. And most people get the answer wrong not because they’re careless, but because they don’t know what questions to ask. This guide gives you a practical, plain-English framework for making the right call.
Why This Decision Matters More Than Most
Commercial real estate is typically the second-largest expense for a small business after payroll. Whether you rent or own, the financial and operational consequences play out for years. A bad decision can drain cash, limit your flexibility, or trap you in a space that no longer fits your business.
The stakes are high. But with the right framework, the answer often becomes clearer than it seems at first.
The Case for Renting
Renting commercial space is the right move for most small businesses, especially in their early and mid-growth stages. Here’s why.
Flexibility Is Worth a Premium
Businesses change. Your team size fluctuates. You might expand into a new market, pivot your service offering, or decide to go fully remote. When you rent, you have the ability to move, downsize, upsize, or renegotiate. When you own, you’re anchored.
For businesses under five years old or those in fast-changing industries, flexibility usually outweighs the financial upside of ownership.
Lower Upfront Capital Requirement
Buying commercial property typically requires a 20 to 30 percent down payment. On a $500,000 property, that’s $100,000 to $150,000 out the door before you open your doors. For most small businesses, that capital is better deployed into operations, marketing, and people.
Renting keeps more cash available for the things that actually drive growth. And cash availability is often the difference between thriving and surviving. If you’re not sure how much capital you have on hand, this guide on using working capital to fuel growth is a good place to start.
Predictable Monthly Costs
A lease locks in your occupancy costs for the term. You know what you’re paying each month, which makes budgeting simpler. Ownership comes with variable costs: maintenance, repairs, property taxes, insurance, and the occasional roof that needs replacing.
Easier to Right-Size Your Space
With a lease, you can move into a space that’s exactly the right size for your business today. If you grow, you look for a larger space at renewal. If you shrink, you negotiate out or sublet. Ownership locks you into whatever you bought, and reselling commercial property takes time.
The Case for Buying
That said, buying commercial space can be a powerful wealth-building move for the right business in the right situation. Here are the conditions where it makes sense.
You Have Stable, Predictable Revenue
Ownership works when your cash flow is consistent and you can comfortably cover a mortgage payment plus maintenance without straining operations. If revenue is lumpy or seasonal, a mortgage adds a fixed obligation that can become a liability in slow periods.
You’ve Been in the Same Location for Three or More Years
Location stability is a strong signal that buying might make sense. If you’ve operated from the same area for several years and have no foreseeable reason to move, you’re essentially paying rent to build someone else’s equity. Owning would let you build yours.
The Property Can Generate Income
One of the strongest arguments for buying commercial real estate is the ability to rent out unused space. If you purchase a building and only need half of it, renting the other half to a compatible tenant can offset or eliminate your mortgage payment. This turns a business expense into a cash-generating asset.
You Want to Build Long-Term Wealth
Commercial real estate generally appreciates over time. Owning your business’s physical home means you’re building an asset separate from the business itself. When you eventually sell or retire, you have two things of value: the business and the property. That’s a significantly stronger financial position.
Many successful business owners use their property as a retirement vehicle: they sell the business but keep the building and collect rent from the new owner. It’s a strategy worth considering from the start.
Key Factors to Weigh Before Deciding
How Long Will You Be Here?
The breakeven horizon for buying commercial property versus renting is typically seven to ten years. If you’re not confident you’ll be in the same location for at least that long, renting usually comes out ahead financially once you factor in transaction costs, carrying costs, and market uncertainty.
What Does the Local Market Look Like?
In some markets, commercial real estate is overpriced relative to rental rates, making renting significantly more efficient. In other markets, buying offers strong value. Always run a rent-versus-own comparison using actual local numbers, not national averages. A commercial real estate broker can help you model this out.
Can You Qualify for an SBA 504 Loan?
The SBA 504 loan program is specifically designed to help small business owners buy commercial real estate with lower down payments (as low as 10 percent in some cases) and below-market interest rates. If you’re seriously considering buying, this program should be on your radar. It can dramatically change the financial math in favor of ownership.
What Are the Tax Implications?
Both renting and owning have tax implications worth understanding. Rent is generally fully deductible as a business expense. Ownership allows you to depreciate the building, deduct mortgage interest, and take advantage of other real estate-specific deductions. Talk to your accountant before making a decision, because the tax picture can vary significantly depending on your structure and situation.
If You Decide to Rent: Protect Yourself
If renting is the right call, make sure you go into the lease with your eyes open. Commercial leases are not standardized, and the terms landlords put in their standard agreement are almost always favorable to the landlord, not you.
Key things to negotiate: who pays for repairs and maintenance, what happens if you need to exit early, whether you have a renewal option at a set rate, and what improvements you can make to the space. Our guide to negotiating a commercial lease walks through this in detail.
If You Decide to Buy: Manage Your Risk
Commercial real estate ownership is not passive. You take on responsibility for the physical asset, and that comes with financial and operational risk. Having a clear-eyed approach to that risk is essential.
Before buying, get a thorough inspection, review zoning restrictions, understand environmental liability exposure, and stress-test your cash flow against a scenario where revenue drops by 25 percent. Can you still cover the mortgage? If the answer isn’t clearly yes, buying might be premature. For more on protecting your business from financial risk, see our guide on managing business risk.
A Simple Decision Framework
When in doubt, run through these five questions:
- Have I been operating from the same location for at least three years? If no, rent.
- Do I have stable, consistent revenue with no major changes expected? If no, rent.
- Can I put 10 to 20 percent down without depleting working capital? If no, rent.
- Am I confident I’ll be in this market for the next seven to ten years? If no, rent.
- Does the property offer income potential from unused space? If yes, buying becomes more attractive.
If you answered yes to questions one through four and no to question five, you likely have a strong case for buying. If you answered no to any of questions one through four, renting is probably the smarter move right now, and that’s completely fine. Most successful businesses rent for a long time before buying, and many never buy at all.
The Bottom Line
Renting gives you flexibility, lower upfront costs, and simpler operations. Buying gives you equity, stability, and income potential. Neither is universally better. The right answer depends on your business’s financial position, growth trajectory, and long-term location plans.
What’s almost always wrong is making the decision based on gut feeling or what a landlord or real estate agent tells you. Do the math. Know your numbers. And when in doubt, prioritize the choice that keeps more cash in your business and more options on the table.
Want more plain-English guides for building a smarter business? Join thousands of entrepreneurs at Hustler’s Library for free access to our full resource library.
Ready to Know Where You Stand?
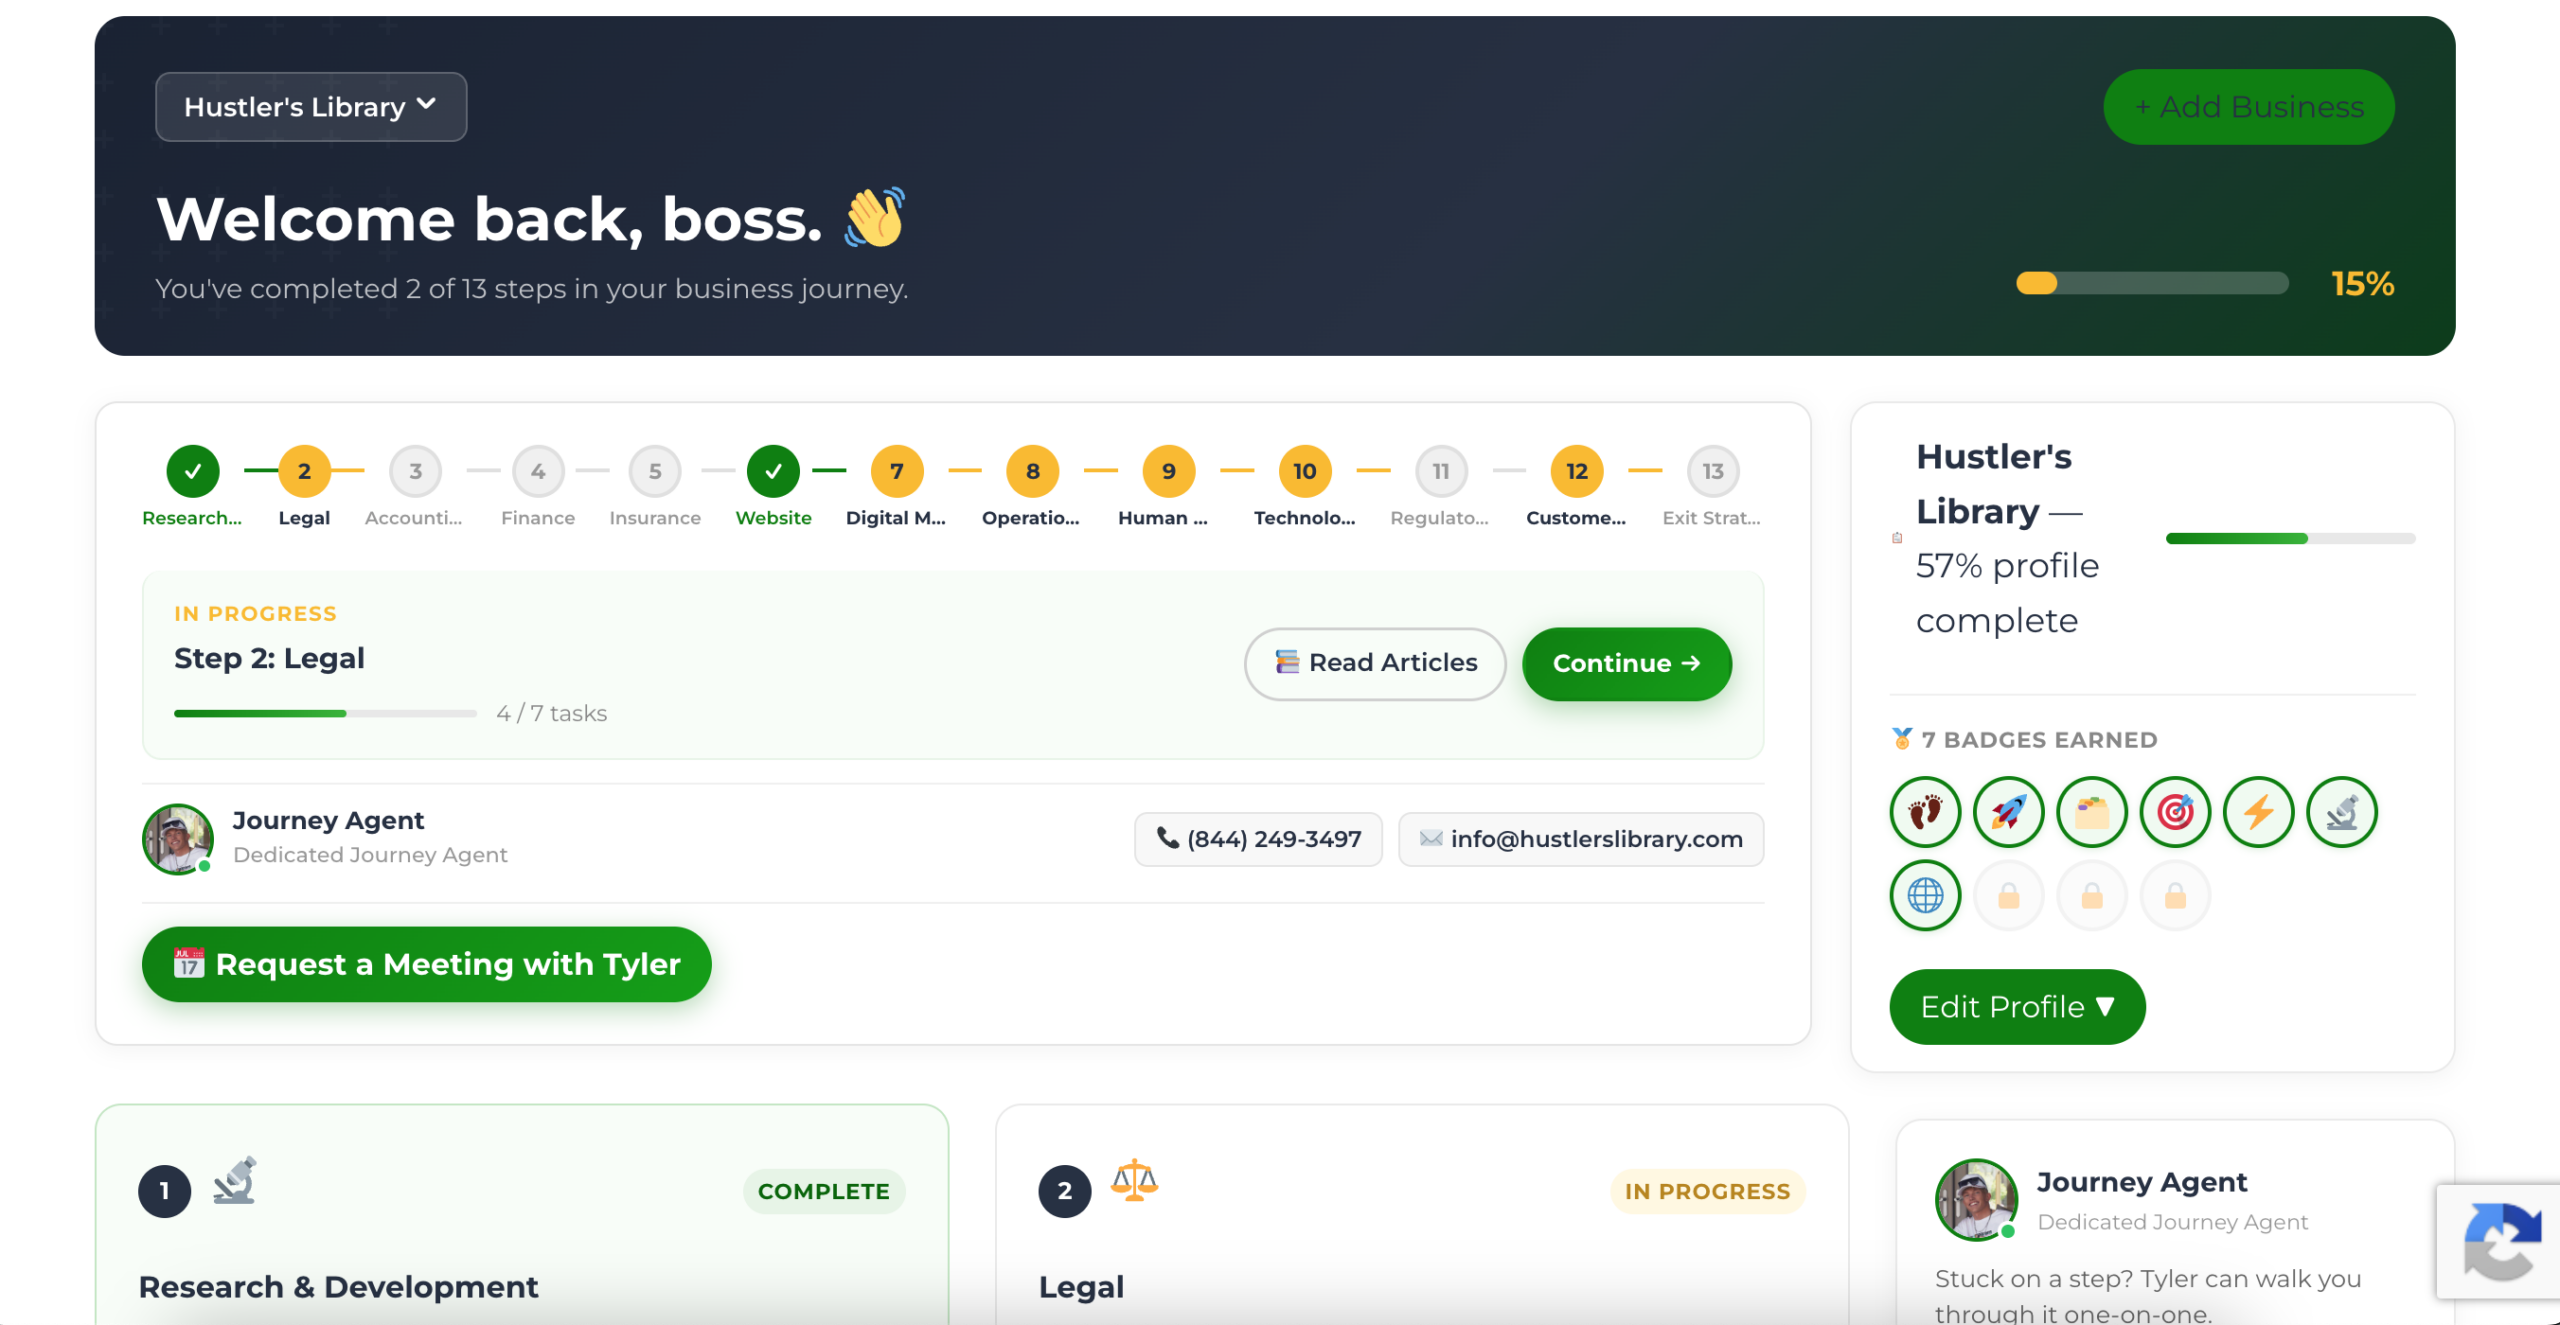
The Business Journey dashboard maps your exact position across all 13 stages. Track your progress, unlock resources for each step, and build with a framework used by thousands of founders at Hustler's Library.
No credit card required · Takes 3 minutes · Personalized to your stage