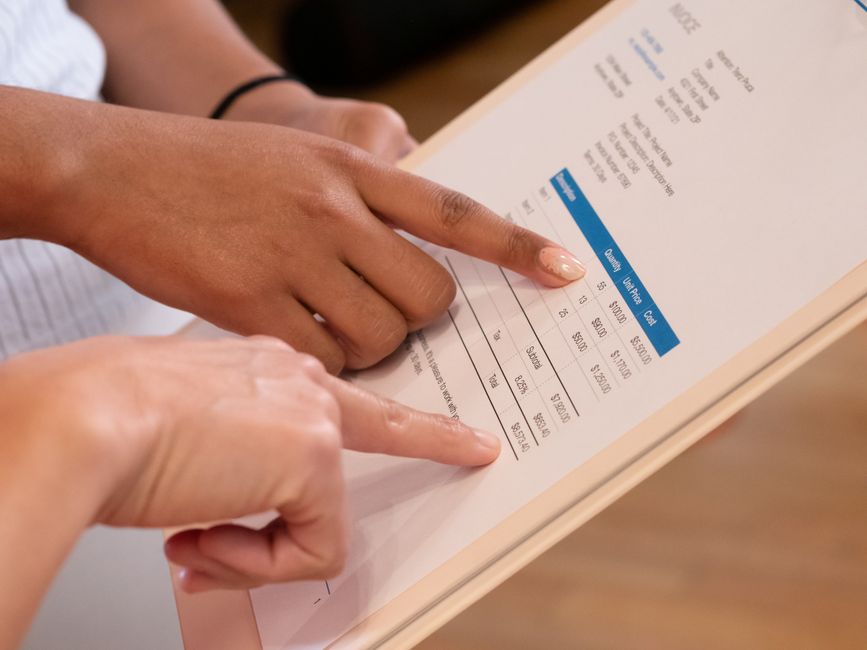
You did the work. You sent the invoice. And then you waited. And waited.
If that sounds familiar, the problem probably isn’t your clients. It’s your payment terms. Most small business owners set them once, never revisit them, and spend years chasing money that should’ve already been in their account.
This guide breaks down exactly how to structure payment terms that protect your cash flow, set clear expectations, and make getting paid the normal, frictionless part of every client relationship.
What Payment Terms Actually Are
Payment terms are the conditions under which you expect to be paid. They cover when payment is due, what methods are accepted, whether a deposit is required, and what happens when someone pays late. Think of them as the financial rules of engagement for every project or sale.
The most common mistake small business owners make is treating payment terms as an afterthought. You close the deal, do the work, and only think about money when the invoice goes out. By then, you’ve already lost your leverage.
Good payment terms are established upfront, in writing, before any work begins. They’re part of your client agreement, your proposals, and your invoices. They’re not a negotiation. They’re a standard.
The Most Common Payment Term Structures
Here are the terms you’ll see most often and when they make sense for a small business:
Due on Receipt
Payment is expected immediately upon receiving the invoice. This is standard for retail, e-commerce, and any business where goods or services are delivered instantly. It’s also a good default for new clients you don’t have a track record with.
Net 15, Net 30, Net 60
“Net 30” means payment is due 30 days after the invoice date. Net 15 and Net 60 follow the same logic. These are common in B2B service businesses and professional services. The shorter the net term, the better your cash position.
A word of caution: many small businesses default to Net 30 because it sounds professional, but if you’re doing a 60- or 90-day project, Net 30 after completion means you might wait three to four months to see any money. That’s a cash flow problem waiting to happen.
50% Upfront, 50% on Completion
This is one of the most practical structures for service businesses. You collect a deposit before starting and the balance when the work is done. It protects you from scope creep, non-payment, and clients who disappear mid-project. It also tells you immediately whether a client is serious.
Milestone Payments
For longer projects, milestone-based payments tie invoicing to specific deliverables. For example, 25% upfront, 25% at the halfway point, and 50% on final delivery. This keeps cash flowing throughout the project and ties payments to real progress both sides can verify.
Retainers
A retainer is a recurring monthly payment for ongoing access to your services. It’s the holy grail for service businesses because it creates predictable revenue and simplifies billing. Clients pay at the start of each month for a defined scope of work. If you can move clients to retainers, do it.
How to Set Payment Terms That Protect Your Business
The best payment terms are the ones you’ll actually enforce. Here’s how to build a structure that works:
1. Start with a deposit for every new client
A deposit of 25 to 50 percent does three things: it covers your initial costs, it filters out low-commitment clients, and it makes the final invoice feel smaller. New clients who push back hard on a deposit are a yellow flag. Established clients who have a history with you can sometimes get more flexibility.
2. Keep your net terms as short as reasonably possible
Unless your industry has an established norm for longer terms, start with Net 15 or even due on receipt. You can always extend terms for a great client. It’s much harder to tighten them up after you’ve established a pattern of Net 30 or Net 60.
3. Add a late fee clause
State in your contract and on your invoices that a late fee applies after the due date. A common structure is 1.5% per month on unpaid balances. Most clients won’t pay the late fee, but the clause signals that you’re serious and gives you a conversation starter. Check your state laws; some have limits on late fee percentages.
4. Offer an early payment discount (only if it makes sense)
A “2/10 Net 30” term means the client gets a 2% discount if they pay within 10 days, otherwise the full amount is due in 30 days. This works well with larger invoices where the discount is worth the cash flow boost. Don’t use it universally or you’ll train clients to always expect a discount.
5. Put your terms in writing before the work starts
Every project should start with a signed agreement that includes payment terms, scope, and consequences for non-payment. This is non-negotiable. A verbal agreement is not a payment policy. If you need a starting point, check out How to Build a Winning Client Intake Process for a framework that covers this from the first touchpoint.
Handling Late Payments Without Damaging Relationships
Even with solid payment terms, some invoices will go past due. Here’s the system that keeps you professional without becoming a pushover:
- Day 1 after due date: Send a friendly reminder. Keep it brief. A short email with the invoice attached and a polite note that payment appears to be outstanding.
- Day 7 after due date: Follow up more directly. Reference the invoice number, the amount, and your late fee policy. Ask if there’s an issue you can help resolve.
- Day 14 after due date: Pick up the phone. Email is easy to ignore. A brief, professional call often unlocks payment that emails couldn’t.
- Day 30 after due date: Issue a formal demand letter with a deadline. State that you will pause future work and may pursue collections or legal remedies if the invoice remains unpaid.
The goal is to stay professional at every stage. Most late payments are the result of client cash flow issues, not bad intent. Your job is to make it easy for them to pay and uncomfortable for them not to.
Making Payment Easy Reduces Late Payments
This sounds obvious but it’s worth saying: friction kills payment speed. The more steps a client has to take to pay you, the longer they’ll wait. Here’s how to reduce that friction:
- Accept multiple payment methods. Credit cards, ACH transfers, and digital wallets. Don’t force clients to write checks in 2026.
- Use invoicing software. Tools like QuickBooks, FreshBooks, or Wave let clients pay directly from the invoice with one click. This alone speeds up payment significantly.
- Include a pay link on every invoice. Don’t make them find your payment portal. Put the link front and center.
- Send invoices immediately. Don’t batch invoices at the end of the month if you can send them when the work is done or the milestone is hit. Delay in invoicing trains clients to delay payment.
Managing cash flow is directly tied to how quickly you get paid, which is why your payment terms are one of the most important financial levers in your business. The SBA’s guide on managing business finances covers cash flow management practices that align well with strong payment policies.
When to Adjust Your Payment Terms
Your payment terms aren’t set in stone. Review them at least once a year or any time you notice a pattern of late payments, cash flow strain, or client friction around billing. Signs that your terms need work:
- You’re regularly waiting more than 45 days to collect after completing work
- More than 10 to 15 percent of invoices require follow-up beyond the due date
- You’ve had to dip into reserves or a credit line because of slow-paying clients
- New clients frequently push back on your terms or try to extend them
If any of these apply, tighten your terms, require larger deposits, or both. The right payment structure isn’t about being difficult. It’s about running a business that can sustain itself.
For a broader look at how payment terms connect to your overall financial health, check out How to Pay Yourself as a Small Business Owner, which walks through how owner compensation, cash flow, and profit all work together.
The Bottom Line
Getting paid isn’t luck. It’s policy. The businesses that consistently get paid on time aren’t more charming or better connected. They have clearer terms, set expectations earlier, and follow through when those terms aren’t met.
Start with a deposit. Keep net terms short. Add a late fee clause. Make payment easy. And put everything in writing before the work starts. Those five moves alone will transform how money flows into your business.
Want more guides like this? Join Hustler’s Library for free and get practical business content delivered straight to your inbox.
Ready to Know Where You Stand?
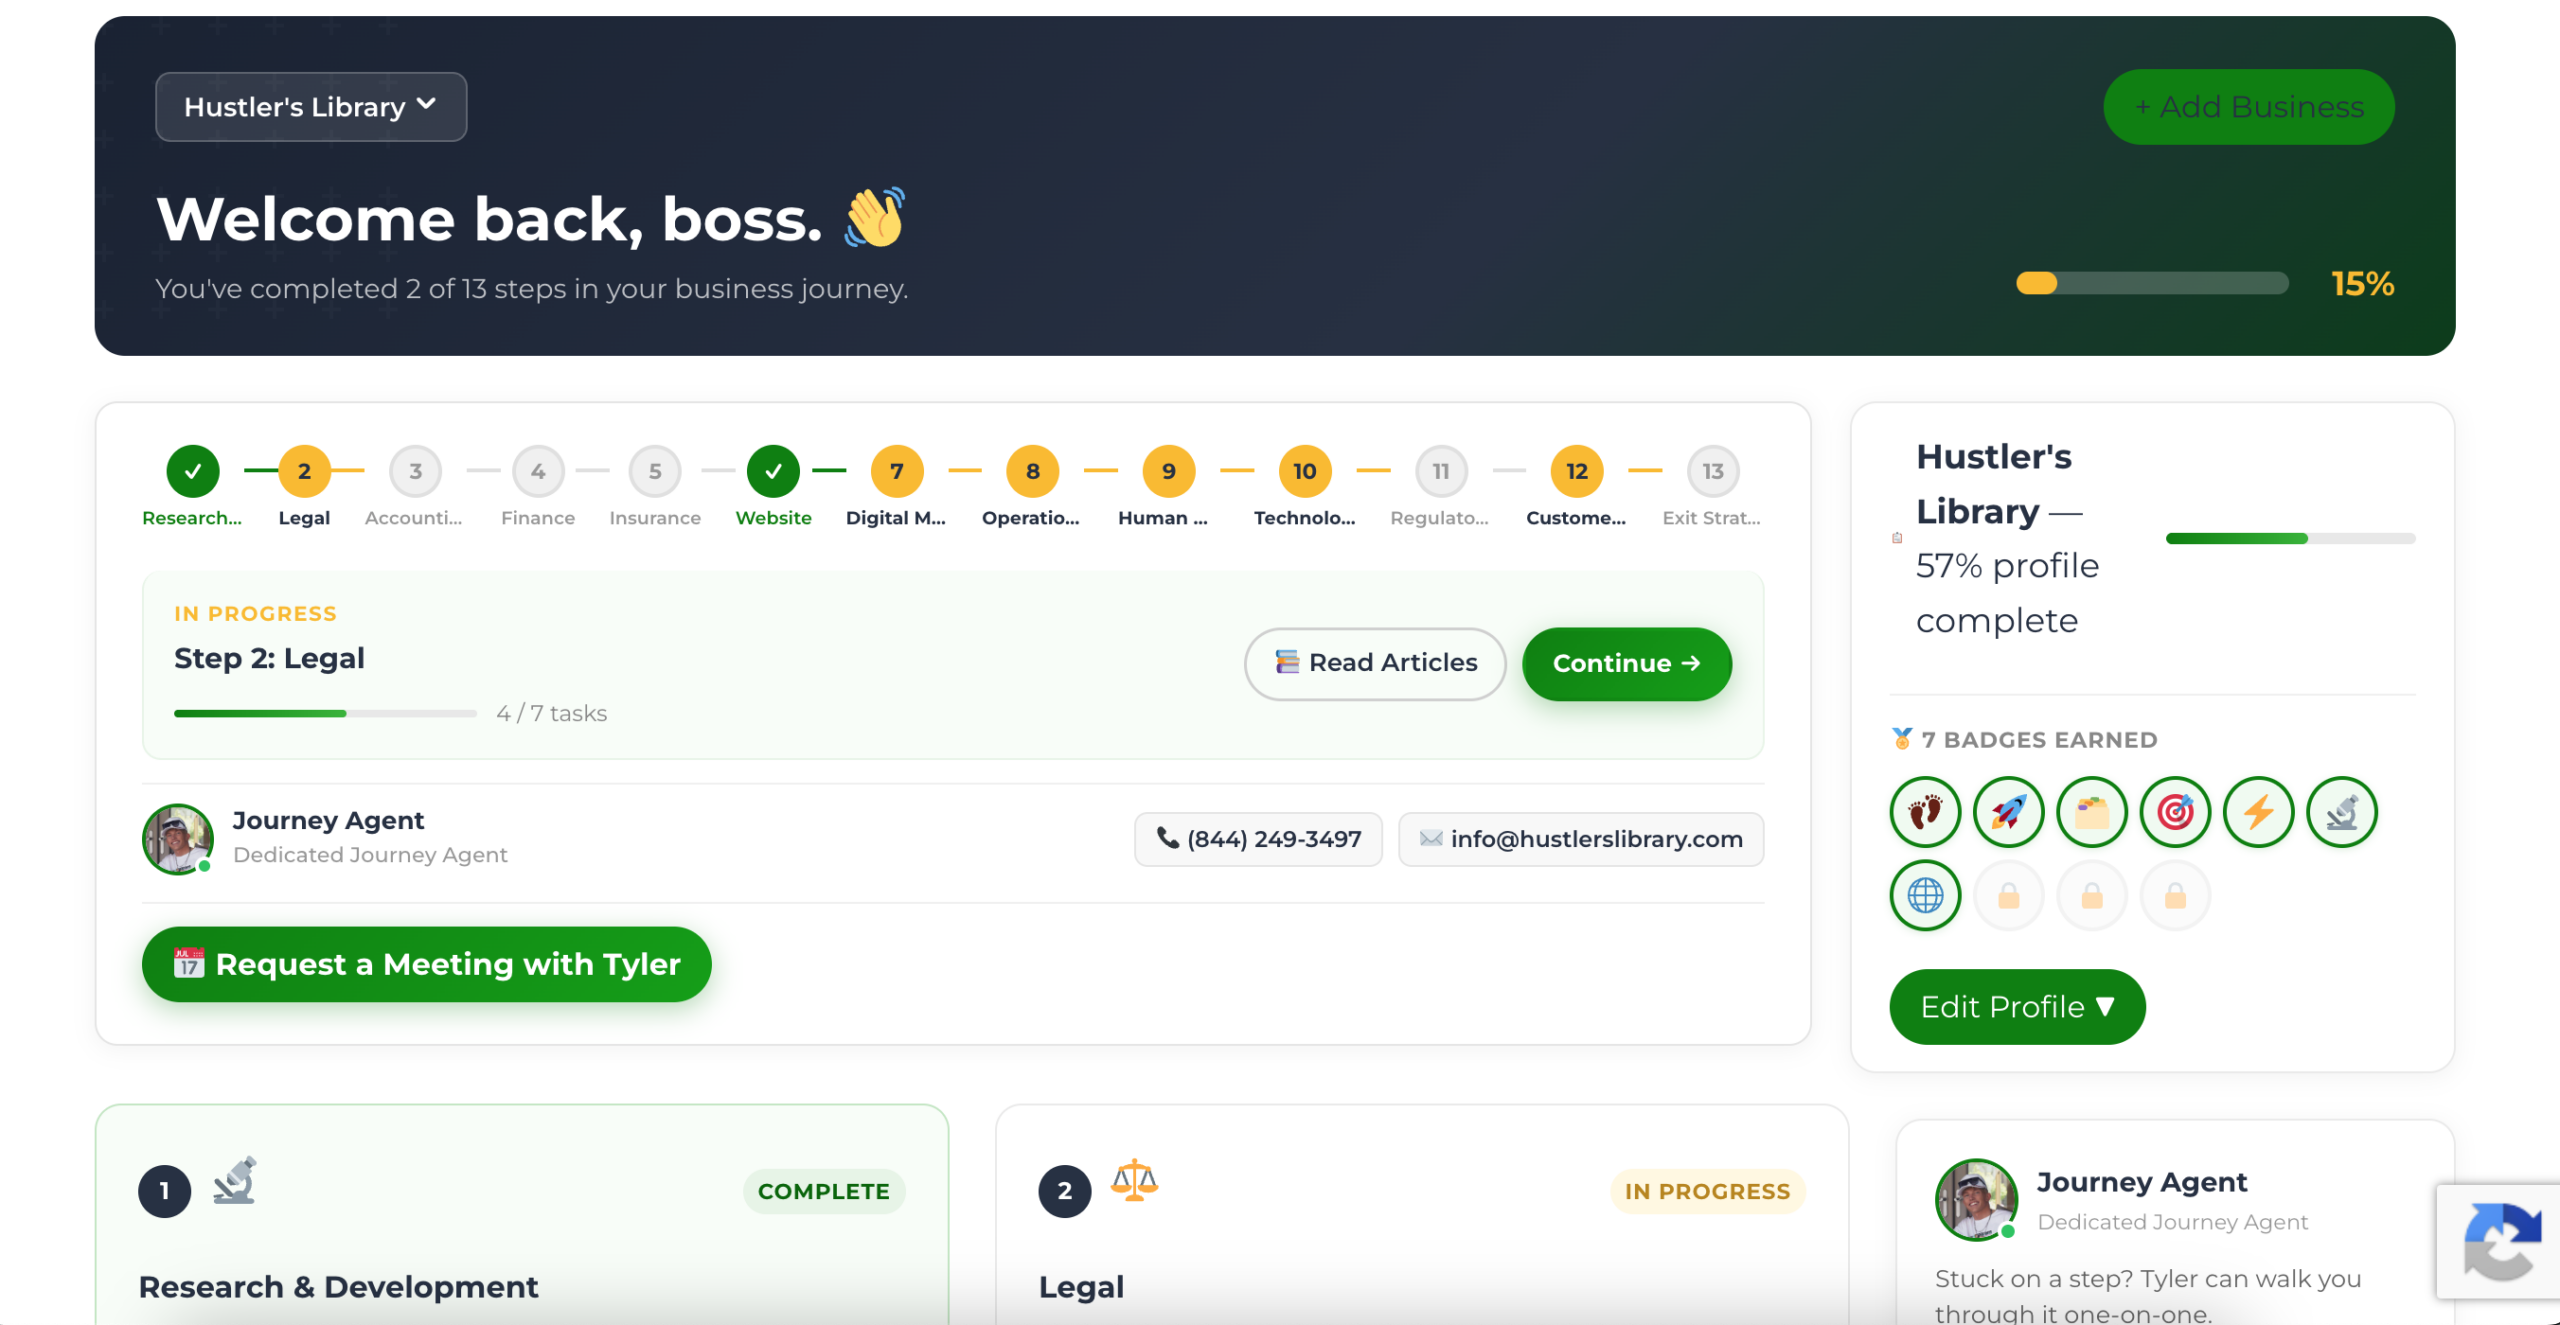
The Business Journey dashboard maps your exact position across all 13 stages. Track your progress, unlock resources for each step, and build with a framework used by thousands of founders at Hustler's Library.
No credit card required · Takes 3 minutes · Personalized to your stage