Buying a business is one of the largest financial decisions you will ever make. The asking price is just a starting point. If you walk into negotiations without a strategy, you will either overpay, miss value-creating opportunities in the deal structure, or lose the business to a better-prepared buyer. This guide gives you a practical, step-by-step negotiation framework for acquiring a small business at the right price on the right terms.
Start With Valuation: Your Anchor Before You Negotiate
Before you can negotiate effectively, you need to know what the business is actually worth. The most common valuation method for small businesses is the SDE multiple: Seller Discretionary Earnings multiplied by an industry-specific number that reflects market conditions and business quality.
SDE multiple ranges by industry vary, but here are general benchmarks as reference points:
- Service businesses (consulting, staffing, agencies): 2x to 3x SDE
- Retail and e-commerce: 2x to 3.5x SDE
- SaaS and subscription businesses: 3x to 6x SDE (or higher based on growth)
- Manufacturing and distribution: 3x to 5x SDE
- Food and beverage / restaurants: 1.5x to 2.5x SDE
These multiples are influenced by factors like revenue trend, owner dependence, customer concentration, and documented systems. A business with strong recurring revenue and low owner dependence will command the top end of its range. A business with messy books and a single dominant customer will land at the bottom, or lower.
Run your own valuation before you make any offer. If the seller is asking for a multiple that is not supported by the fundamentals, you have a data-backed basis for your counter. That is your anchor.
To understand how SBA financing fits into your acquisition strategy, review our guide on the SBA 7(a) loan program, which is the most common financing tool for small business acquisitions.
Due Diligence as a Negotiation Lever
Every issue you uncover during due diligence is either a price reduction or a term improvement. This is not adversarial; it is the natural function of the process. Buyers are paying for what the business actually is, not what the listing says it is.
Document everything you find. If the financials show inconsistencies, that is a lever. If a key employee does not have a contract, that is a lever. If one customer accounts for 40 percent of revenue, that is a significant lever. If there is deferred maintenance on equipment or a lease expiring in 18 months, those are levers.
Present your findings professionally with a written summary. Sellers respond better to organized, data-driven buyers than to buyers who seem to be nitpicking. Your goal is to have a factual conversation about risk, not to attack the seller personally.
Negotiation Levers Beyond Price
Most first-time buyers fixate on the purchase price. Experienced acquirers know that the terms of the deal are often worth more than the price itself. Here are the key levers to negotiate beyond the headline number:
Seller Financing
Seller financing means the seller holds a note for part of the purchase price, which you pay back over time. This reduces the cash you need at close, aligns the seller’s interests in a smooth transition, and signals that the seller has confidence in the business continuing to perform. A seller who refuses any seller financing is worth pressing on why.
Earn-Out Structure
An earn-out ties a portion of the purchase price to future performance. If the seller is claiming strong forward revenue but the track record does not fully support it, an earn-out bridges that gap. You pay a base price now and additional amounts only if the business hits agreed-upon milestones after the acquisition.
Training Period and Transition Support
How long will the seller stay on to support the transition? Negotiate a meaningful training period, typically 30 to 90 days, included in the purchase price. For complex businesses, you may want six months or longer with the seller available as a consultant.
Non-Compete Scope
Make sure the non-compete agreement is specific about geography, time period, and industry. A non-compete that is too narrow leaves the door open for the seller to compete with you. Too broad and it may not be enforceable. Get this right in the purchase agreement.
Inventory Adjustment at Close
Inventory levels fluctuate. Negotiate a mechanism that adjusts the purchase price based on actual inventory at close compared to a target amount. This protects you from a seller who depletes inventory before closing or inflates it above agreed levels.
How to Make Your First Offer
Come in 10 to 20 percent below the asking price with a written rationale. This is not lowballing; it is informed negotiation. Your rationale should reference your valuation work, any due diligence findings, and market comps if available.
Sellers respect buyers who bring data. A buyer who simply says “I want to pay less” is easy to dismiss. A buyer who presents a written analysis showing why the current asking price reflects a multiple above market for this type of business, given specific risk factors, is much harder to ignore.
Make your offer in writing, even if informal at first. Written offers are taken more seriously and force both parties to get specific about terms rather than having vague conversations that go nowhere.
When the Seller Won’t Budge on Price
Some sellers are emotionally attached to a number. If price is genuinely off the table, shift the negotiation to terms. A longer seller note at a low interest rate can be worth significantly more than a price reduction. A 12-month training period with full transition support has real value. A broader non-compete with stronger enforcement provisions protects your investment in ways that price alone does not.
You can also ask for additional assets to be included: equipment, customer lists, domain names, social accounts, or favorable lease assignment terms. These additions increase the value of what you are purchasing without changing the headline price.
Understanding the deal structure matters here too. Whether you are structuring this as an asset purchase or a stock purchase has major tax and liability implications for both parties. Our guide on how to buy a business covers the structural options in detail.
Walking Away as a Tactic
The most powerful negotiating position is genuine willingness to walk away. This is not a bluff or a tactic you perform; it is a mindset you need to actually have before you sit down to negotiate.
If you are emotionally committed to a specific deal, the seller will sense it and the terms will reflect it. There are always other businesses for sale. If this deal cannot get to terms that make financial sense for you, the right answer is to walk away, clearly and professionally, and leave the door open if the seller reconsiders.
More than once, a buyer who walked away received a call back within weeks because the seller could not find a better offer. Your walk-away posture is real leverage only when you are actually prepared to use it.
For additional perspective on acquisition financing, the SBA 7(a) loan program page outlines how acquisition financing works and what lenders require from buyers.
The Bottom Line
Negotiating a business acquisition is not about winning at the seller’s expense. It is about arriving at a deal structure that reflects the real risk and value of the business, protects you financially, and sets the acquisition up for success. Come prepared with your valuation work, document everything in due diligence, and think beyond price to the full structure of the deal. The buyers who close the best deals are the ones who are the most prepared.
Ready to Build Smarter?
Get access to our full library of business guides, tools, and resources.
Ready to Know Where You Stand?
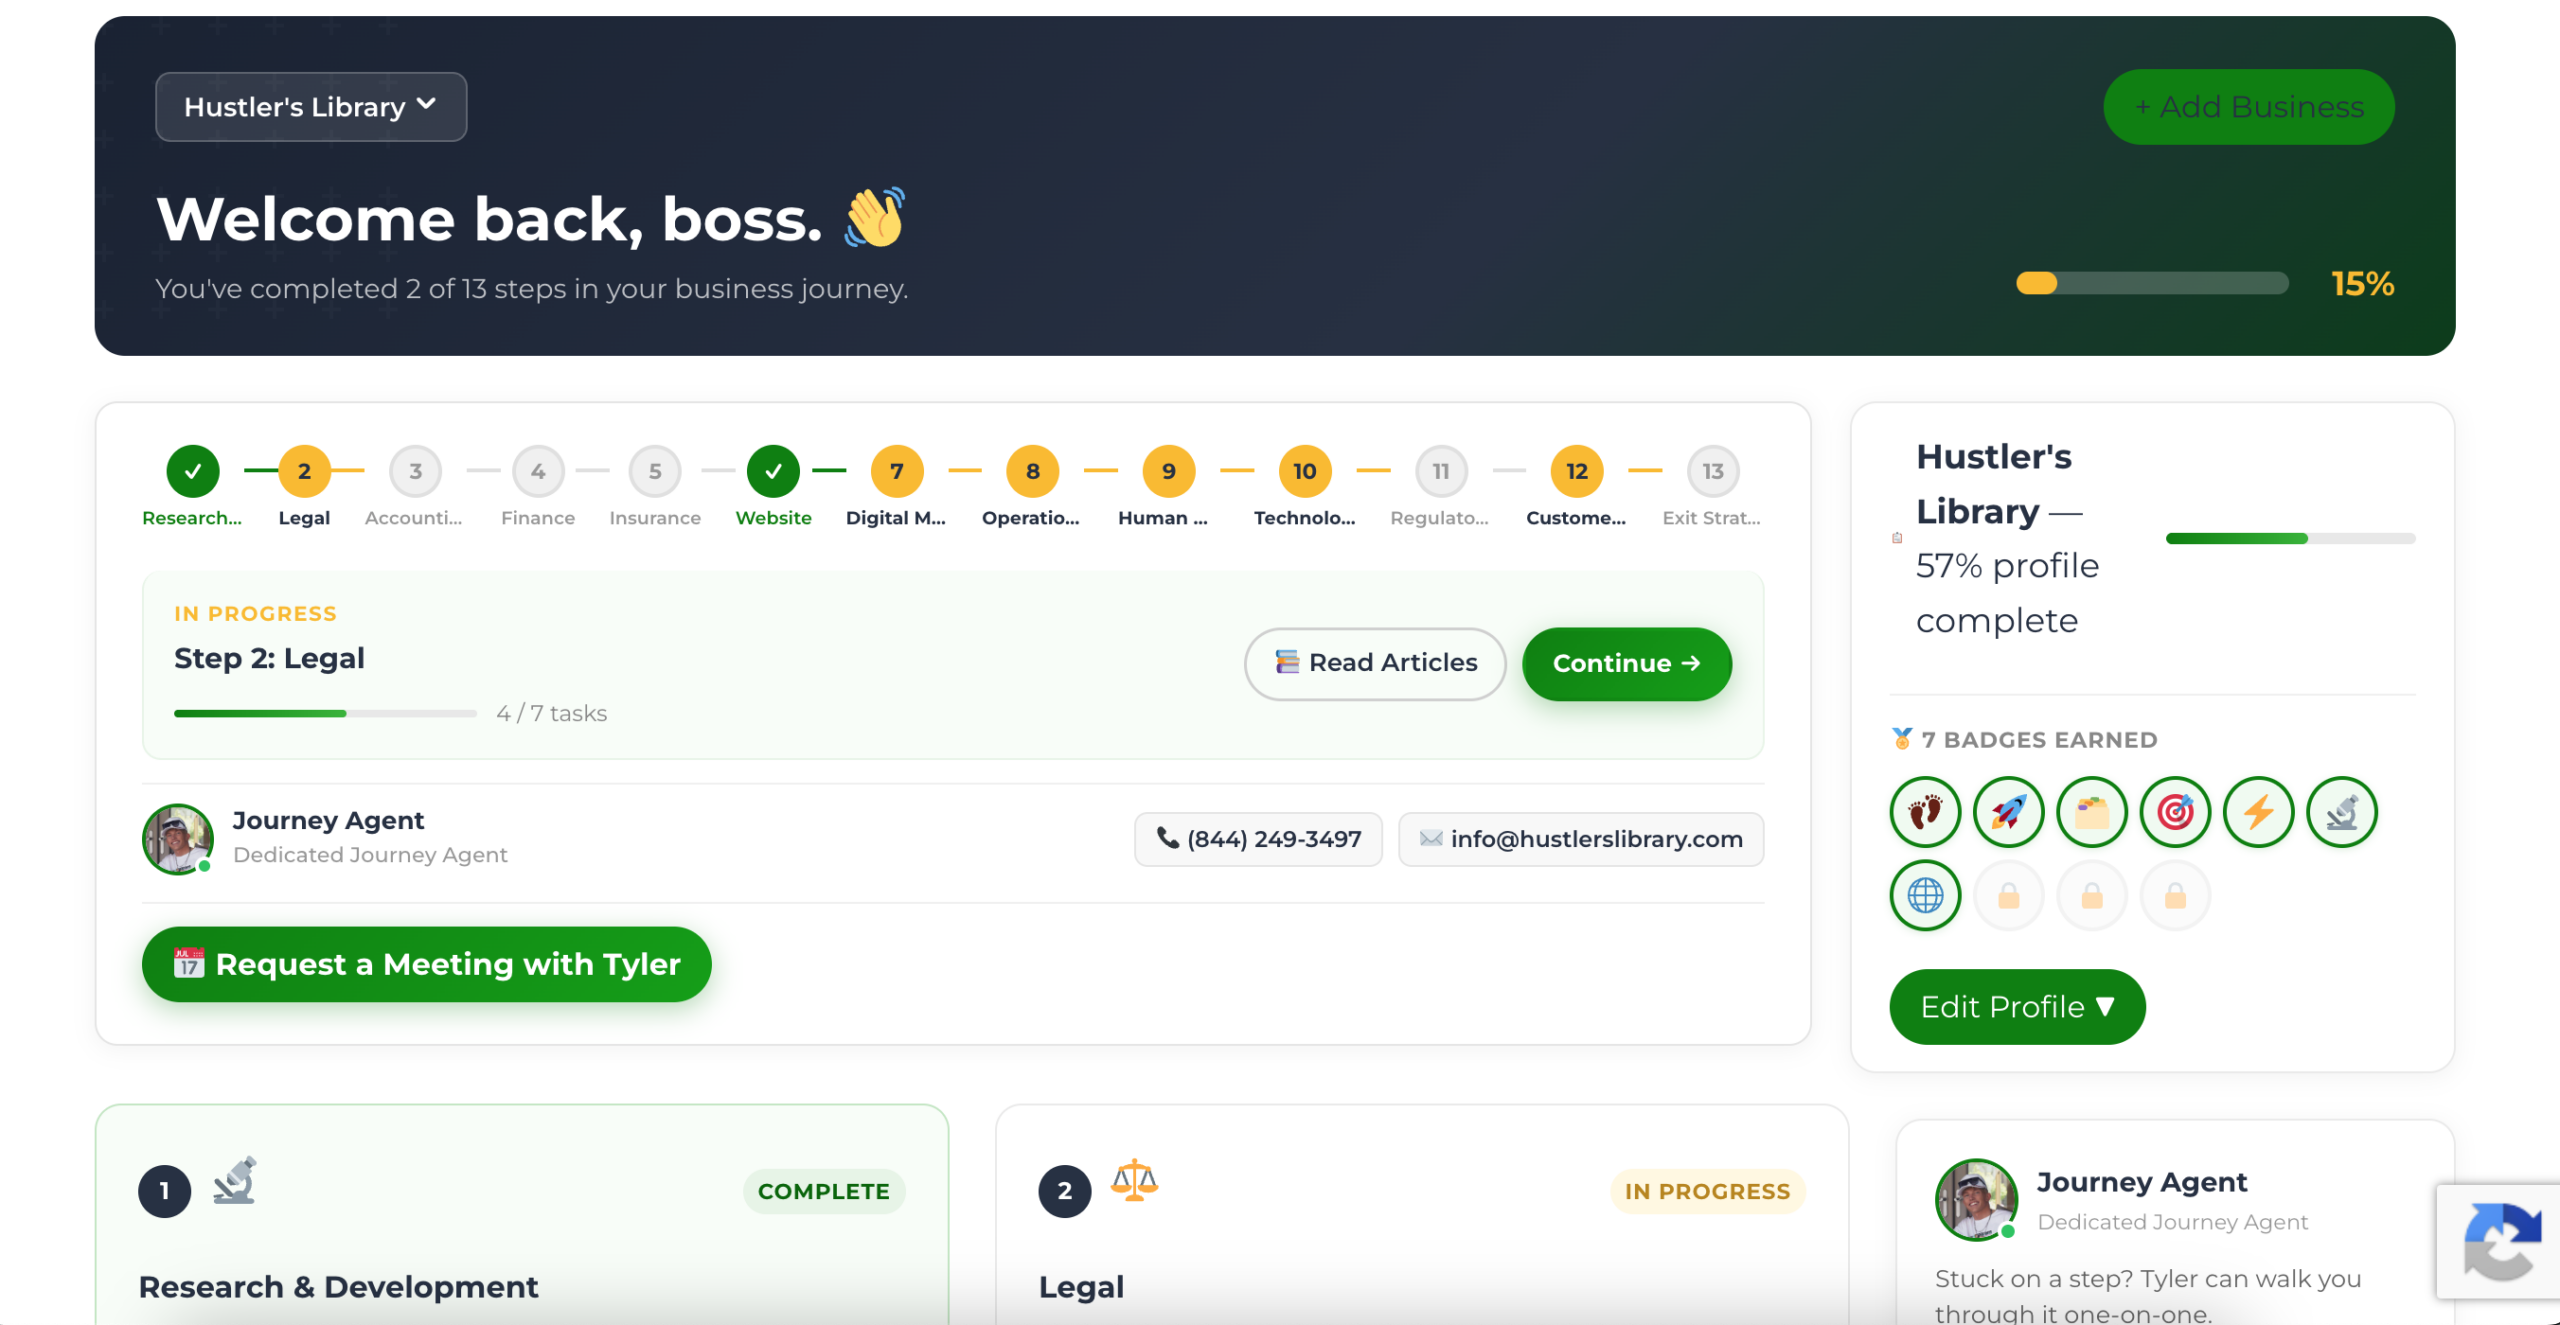
The Business Journey dashboard maps your exact position across all 13 stages. Track your progress, unlock resources for each step, and build with a framework used by thousands of founders at Hustler's Library.
No credit card required · Takes 3 minutes · Personalized to your stage