
You need a business loan. Or maybe you’re trying to lease a commercial space. Or sign up for a line of credit. Everything looks good until you get to page seven and see the words: personal guarantee required.
Most small business owners sign without fully understanding what they’re agreeing to. That’s a mistake that can follow you for years. This guide breaks down exactly what a personal guarantee is, when you should sign one, and how to protect yourself when you do.
What Is a Personal Guarantee?
A personal guarantee is a legal promise that you, as an individual, will repay a debt or fulfill an obligation if your business cannot. When you sign one, you’re removing the legal separation between you and your company. If your LLC or corporation defaults on a loan, the lender can come after your personal assets: your home, your savings, your car.
That’s the whole reason people form LLCs in the first place; to create that separation. A personal guarantee effectively tears it down for that specific obligation.
Why Lenders Require Them
Lenders require personal guarantees because small businesses are risky. An LLC with two years of revenue and no hard assets doesn’t give a bank much to hold onto. You, on the other hand, probably have a credit history, a home, and other personal assets. The guarantee gives the lender a secondary source of repayment if the business fails.
It’s not personal. It’s risk management. And in most cases, it’s non-negotiable; especially for SBA loans, commercial leases, and business lines of credit with newer companies.
The Two Main Types
Not all personal guarantees are the same. Before you sign anything, understand which type you’re agreeing to:
Unlimited Personal Guarantee
This is the most dangerous type. You agree to be personally responsible for the entire debt, plus any interest, legal fees, and collection costs. If your business owes $300,000 and defaults, the lender can pursue you for all of it. Most SBA loans require unlimited personal guarantees from anyone who owns 20% or more of the business.
Limited Personal Guarantee
A limited guarantee caps your personal liability at a specific dollar amount or percentage of the total debt. If your business has multiple owners, each might sign a limited guarantee proportional to their ownership stake. This is more favorable; and more negotiable in commercial agreements.
When You’ll Almost Always Be Asked to Sign One
Here are the most common situations where personal guarantees come up for small business owners:
- SBA loans: The SBA requires personal guarantees from all owners with 20% or more equity. This is standard and non-negotiable.
- Commercial leases: Landlords often require a personal guarantee, especially for newer businesses without a long rental history. If your business walks out on a three-year lease, they want to be able to come after you personally. (Read our guide to reviewing a commercial lease before you sign it.)
- Business credit cards: Most small business credit cards include a personal guarantee in the application terms; often buried in the fine print.
- Equipment financing: If you’re financing machinery, vehicles, or technology, expect a personal guarantee request from most lenders.
- Vendor credit accounts: Some suppliers who extend net-30 or net-60 terms to small businesses will ask for a personal guarantee as part of the application.
The Risk Is Real: What Happens If You Default
If your business can’t pay and you’ve signed a personal guarantee, the creditor can:
- Sue you personally in civil court
- Obtain a judgment against your personal assets
- Garnish your wages or bank accounts
- Place a lien on your personal property, including your home
- Damage your personal credit score significantly
In some cases, even filing for business bankruptcy won’t protect you. Chapter 7 business bankruptcy can discharge the business’s liability, but your personal guarantee obligation typically survives.
How to Protect Yourself When You Have to Sign
Sometimes you can’t avoid a personal guarantee. Here’s how to limit your exposure:
Negotiate for a Limited Guarantee
If you’re dealing with a vendor, landlord, or private lender (rather than a bank or the SBA), ask to cap the guarantee. Offer a dollar limit or time limit instead of an open-ended commitment. Many landlords, for instance, will accept a personal guarantee that expires after 12 to 24 months of on-time payments.
Request a “Good Guy” Clause
Common in commercial real estate, a “good guy” clause allows you to limit your personal liability if you give proper notice and vacate the property in good condition. Instead of being on the hook for the full remaining lease term, you’re only liable through your move-out date. This is a legitimate ask and many landlords will agree to it.
Keep Personal and Business Assets Separate
If you do sign a personal guarantee, you want your personal balance sheet to be as clean as possible. Avoid co-mingling funds, taking large personal draws right before applying for credit, or putting personal assets into the business without a clear paper trail. A solid personal asset protection strategy matters here.
Ask for a Release Clause
Some guarantees can be structured to release you once the business reaches certain milestones: two years of on-time payments, a specific revenue threshold, or a debt-to-equity ratio. Ask upfront if the lender or landlord is willing to include a release clause. Not all will agree, but it costs nothing to ask.
Have a Lawyer Review It
Personal guarantees are legally binding contracts with significant financial consequences. If you’re signing one for a large loan or a long-term commercial lease, pay a business attorney to review it before you sign. An hour of legal fees could save you years of personal liability.
When to Refuse (And What to Offer Instead)
You don’t always have to sign. Here’s when it makes sense to push back:
- You have an established business with strong financials. If your company has three or more years of solid revenue, consistent profitability, and real assets, you have more leverage to negotiate terms without a personal guarantee.
- The amount is small relative to your business revenue. For a small vendor credit line, a personal guarantee feels disproportionate. Offer additional collateral or a larger deposit instead.
- You’re being asked to guarantee someone else’s business. Never sign a personal guarantee on behalf of a business you don’t control or fully trust. If it defaults, you’re left holding the debt.
Alternatives you can propose include: a larger upfront deposit, additional collateral (business equipment, inventory), a shorter contract term with renewal options, or a letter of credit from your bank. If the deal is right, most parties are open to creative solutions.
The Bottom Line
A personal guarantee is serious. It’s not just paperwork; it’s a legal commitment that crosses the line between your business and your personal life. Before you sign one, know exactly what you’re agreeing to: the amount, the duration, whether it’s limited or unlimited, and what triggers it.
Most small business owners will sign personal guarantees at some point; especially when they’re young businesses with limited credit history. That’s okay. Just go in with your eyes open, negotiate where you can, and make sure the business decision on the other side of that signature is worth the risk you’re taking on.
For more on protecting your business legally, see our guide on how to navigate a business lawsuit as a small business owner. The SBA also publishes guidance on how personal guarantees work in SBA lending that’s worth a read before you apply.
Want more straight-talk business guides like this? Join Hustler’s Library free and get the resources, tools, and insights that serious business owners actually use.
Ready to Know Where You Stand?
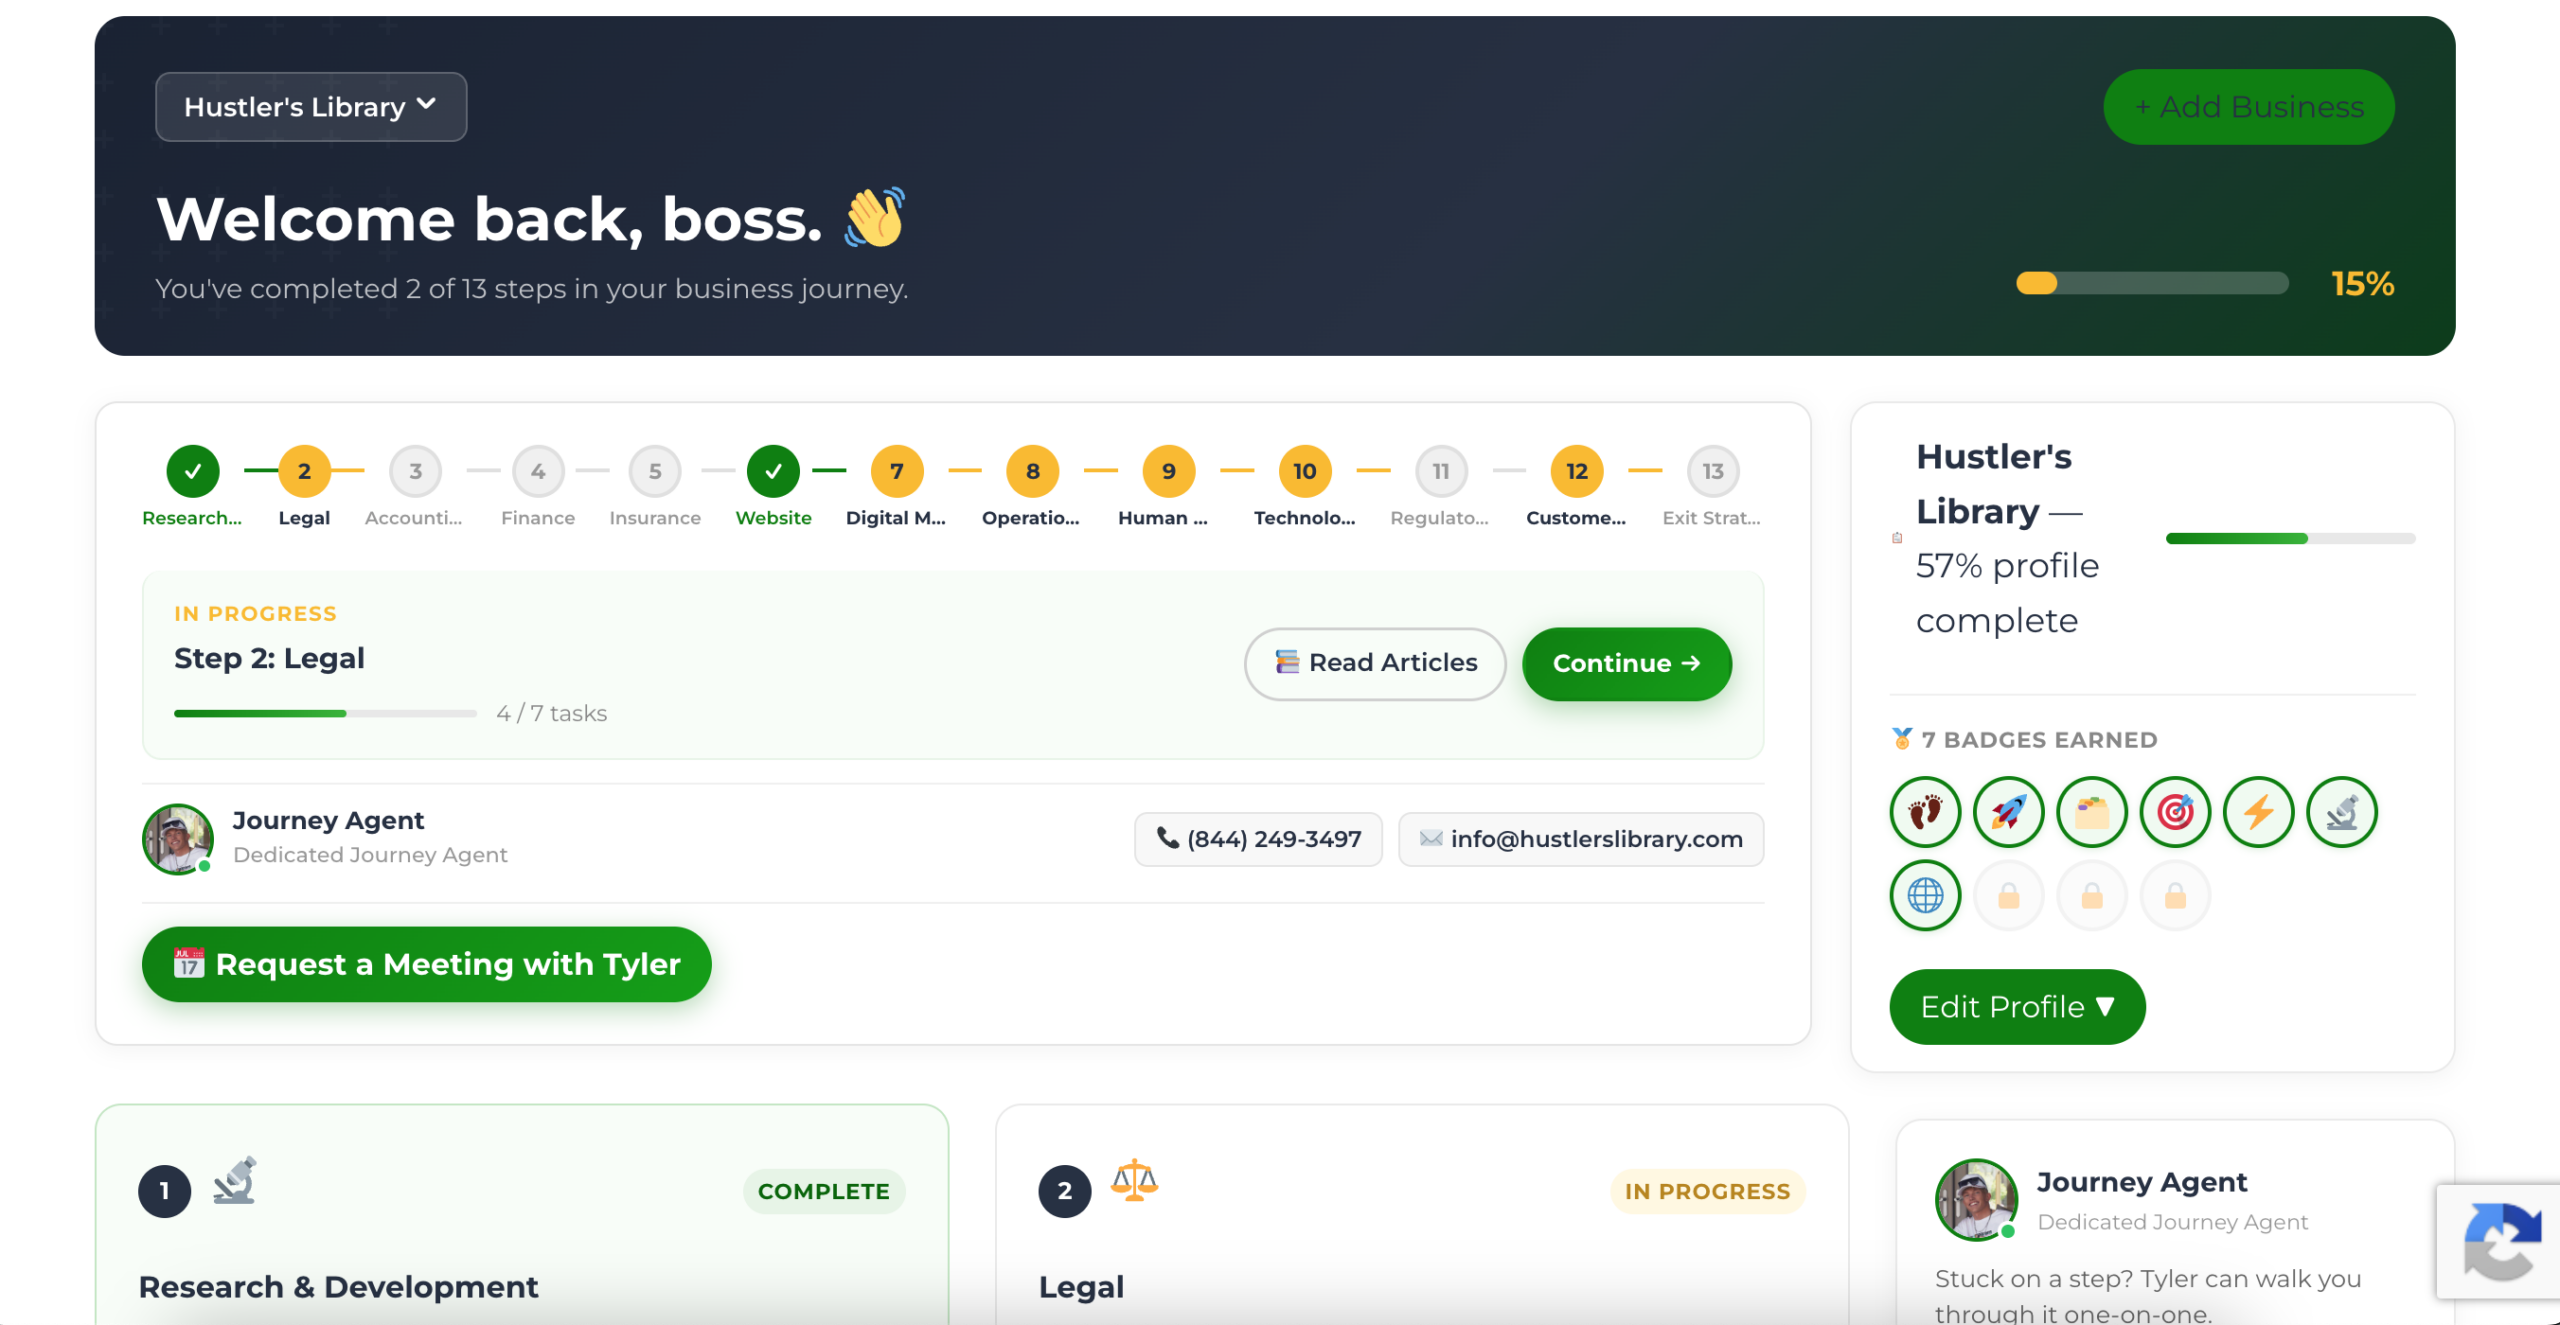
The Business Journey dashboard maps your exact position across all 13 stages. Track your progress, unlock resources for each step, and build with a framework used by thousands of founders at Hustler's Library.
No credit card required · Takes 3 minutes · Personalized to your stage