Here is a sentence that confuses more small business owners than almost anything else in finance: “We did $400,000 in revenue last year, but I barely took home $30,000.”
If that sounds familiar, you are not alone. And the problem is not that your business is broken. The problem is that many owners have never been taught the critical difference between revenue and income.
These two numbers live in completely different places on your financial statements. They tell completely different stories about your business. And if you are managing your company based on the wrong one, you are flying blind.
Let us fix that right now.
Revenue: The Starting Line
Revenue, also called gross revenue or top-line revenue, is the total amount of money your business brings in from selling products or services before any expenses are deducted.
If you are a contractor and you complete $200,000 in jobs this year, your revenue is $200,000. If you run a retail shop and your customers pay $350,000 at the register, that is your revenue. Simple.
Revenue is the number that makes headlines. It is what you brag about at the dinner table. It is what you report when someone asks how big your business is. But here is the truth: revenue alone tells you almost nothing about the health of your business.
A business doing $2 million in revenue can be hemorrhaging cash. A business doing $300,000 in revenue can be wildly profitable. Revenue is just the starting point.
Income: What Actually Matters
Income is what remains after you subtract your costs and expenses from your revenue. There are actually several types of income you should know, and each one tells a different part of the story.
Gross Income (Gross Profit)
This is revenue minus the direct costs of producing your goods or services, known as cost of goods sold (COGS). If you sell $200,000 worth of landscaping services and your direct labor and materials cost $110,000, your gross profit is $90,000.
Gross profit tells you whether your core offering is priced correctly and delivered efficiently. A shrinking gross margin is usually the first warning sign that something is wrong with your pricing or your cost structure.
Operating Income
This is gross profit minus your operating expenses, which include rent, salaries, marketing, software, utilities, and other overhead costs. Operating income, sometimes called EBIT (earnings before interest and taxes), shows you whether your business is profitable from its core operations.
This is the number that serious buyers look at when they evaluate a business for acquisition. It strips away financing decisions and taxes to reveal how efficiently the business actually runs. If you want to understand what your business is genuinely worth, start tracking this number closely. You can learn more about how these metrics connect in our guide on the 5 metrics that actually predict your business survival.
Net Income (Net Profit)
Net income is the bottom line. It is what is left after subtracting every single expense, including interest on loans, taxes, and any other deductions. This is the number most people mean when they say “profit.”
Net income is what you can reinvest in the business, distribute to owners, or save as a cushion. If your net income is consistently negative, your business is losing money regardless of how impressive your revenue looks.
Why Confusing These Two Numbers Is Dangerous
Most business owners make one of two classic mistakes when they mix up revenue and income.
Mistake 1: Spending based on revenue. You see $50,000 hit your account and start making big moves, buying equipment, hiring staff, expanding your office. But that $50,000 includes the cost of the jobs you just completed, your next payroll cycle, and three outstanding vendor invoices. What you actually have available is far less. This is how businesses go broke while looking successful on paper.
Mistake 2: Celebrating revenue growth while margins collapse. You landed twice as many clients this year. Revenue is up 40 percent. Everyone is excited. But your net income is actually lower than last year because your costs grew faster than your revenue. Chasing top-line growth without watching your margins is one of the most common ways small businesses accidentally work harder for less money.
The solution is simple: track both, every single month. Our guide on the 7 numbers every small business owner should track every week gives you a practical framework for doing exactly that.
A Simple Way to Visualize It
Think of your business like a bucket with holes. Revenue is the water pouring in at the top. Every hole in the bucket, your COGS, your operating expenses, your taxes, your loan payments, represents money flowing out. Net income is whatever water remains in the bucket at the end of the period.
Your job as a business owner is not just to pour more water into the bucket. It is to find the holes and patch them, so the water that comes in actually stays. A business with $5 million in revenue and $4.9 million in expenses is in a far more precarious position than a business doing $500,000 in revenue with 30 percent net margins.
Volume does not equal viability. Efficiency builds wealth.
What This Looks Like on a Real Statement
Here is a simplified income statement for a service-based small business so you can see how these numbers stack up:
- Revenue: $480,000
- Cost of Goods Sold (labor, materials, subcontractors): $192,000
- Gross Profit: $288,000 (60% gross margin)
- Operating Expenses (rent, salaries, software, marketing): $204,000
- Operating Income: $84,000
- Interest and taxes: $22,000
- Net Income: $62,000 (12.9% net margin)
Revenue tells you the business is doing nearly half a million dollars. Net income tells you the owner pockets about $62,000 for the year. Both numbers are real. Neither one alone gives you the full picture.
If you have never sat down with your own numbers and built something like this out, our post on how to read a balance sheet as a small business owner is a great complement to this one.
What Healthy Margins Look Like by Industry
One of the most useful things you can do once you understand the revenue-to-income relationship is benchmark your margins against your industry. The IRS Statistics of Income data and SBA industry reports are two of the best free resources for this.
As a general reference point, net profit margins vary widely by industry. Consulting and professional services businesses often run 15 to 25 percent net margins. Retail businesses typically run 2 to 5 percent. Restaurants are notoriously thin at 3 to 9 percent. Software and technology businesses can hit 20 percent or higher.
Knowing your industry benchmark helps you diagnose problems faster. If your industry average net margin is 18 percent and yours is 4 percent, you have a problem that more revenue will not fix on its own. You need to look at your cost structure and find the leaks. The SBA’s finance management resources include industry-specific guidance to help you benchmark your business accurately.
Three Moves That Improve Your Income Without Necessarily Growing Your Revenue
Here is where this understanding becomes truly powerful. You do not always have to grow your revenue to improve your income. Sometimes the fastest path to putting more money in your pocket is operating more efficiently at your current size.
- Reduce cost of goods sold. Negotiate better supplier rates, reduce waste, or find a more efficient way to deliver your service. Every dollar you cut from COGS goes straight to gross profit.
- Audit and trim operating expenses. Do a quarterly review of every recurring expense. Cancel subscriptions you are not using. Renegotiate your lease. Question every tool and vendor. Most businesses are carrying $5,000 to $20,000 per year in unnecessary overhead without realizing it.
- Raise your prices strategically. A 5 to 10 percent price increase on well-positioned services often has minimal impact on client retention but can dramatically improve net income. If your margins are thin, pricing is almost always part of the conversation.
The Bottom Line
Revenue is what you earn. Income is what you keep. Both numbers matter. Neither one alone is enough.
The business owners who thrive long-term are the ones who understand the full journey their money takes, from the moment it comes in the door to whatever is left after every obligation is met. They are not chasing the top line for bragging rights. They are protecting the bottom line because that is where real wealth is built.
If you have been running your business primarily off your bank balance or your total sales figures, this is your sign to dig deeper. Pull your last 12 months of financials. Calculate your gross profit margin and your net profit margin. Compare them to your industry benchmark. You may be surprised at what you find, and once you know the numbers, you can actually do something about them.
Want more tools, guides, and strategies to help you build a more profitable business? Join the Hustler’s Library for free and get access to the full resource vault built for serious small business owners.
Ready to Know Where You Stand?
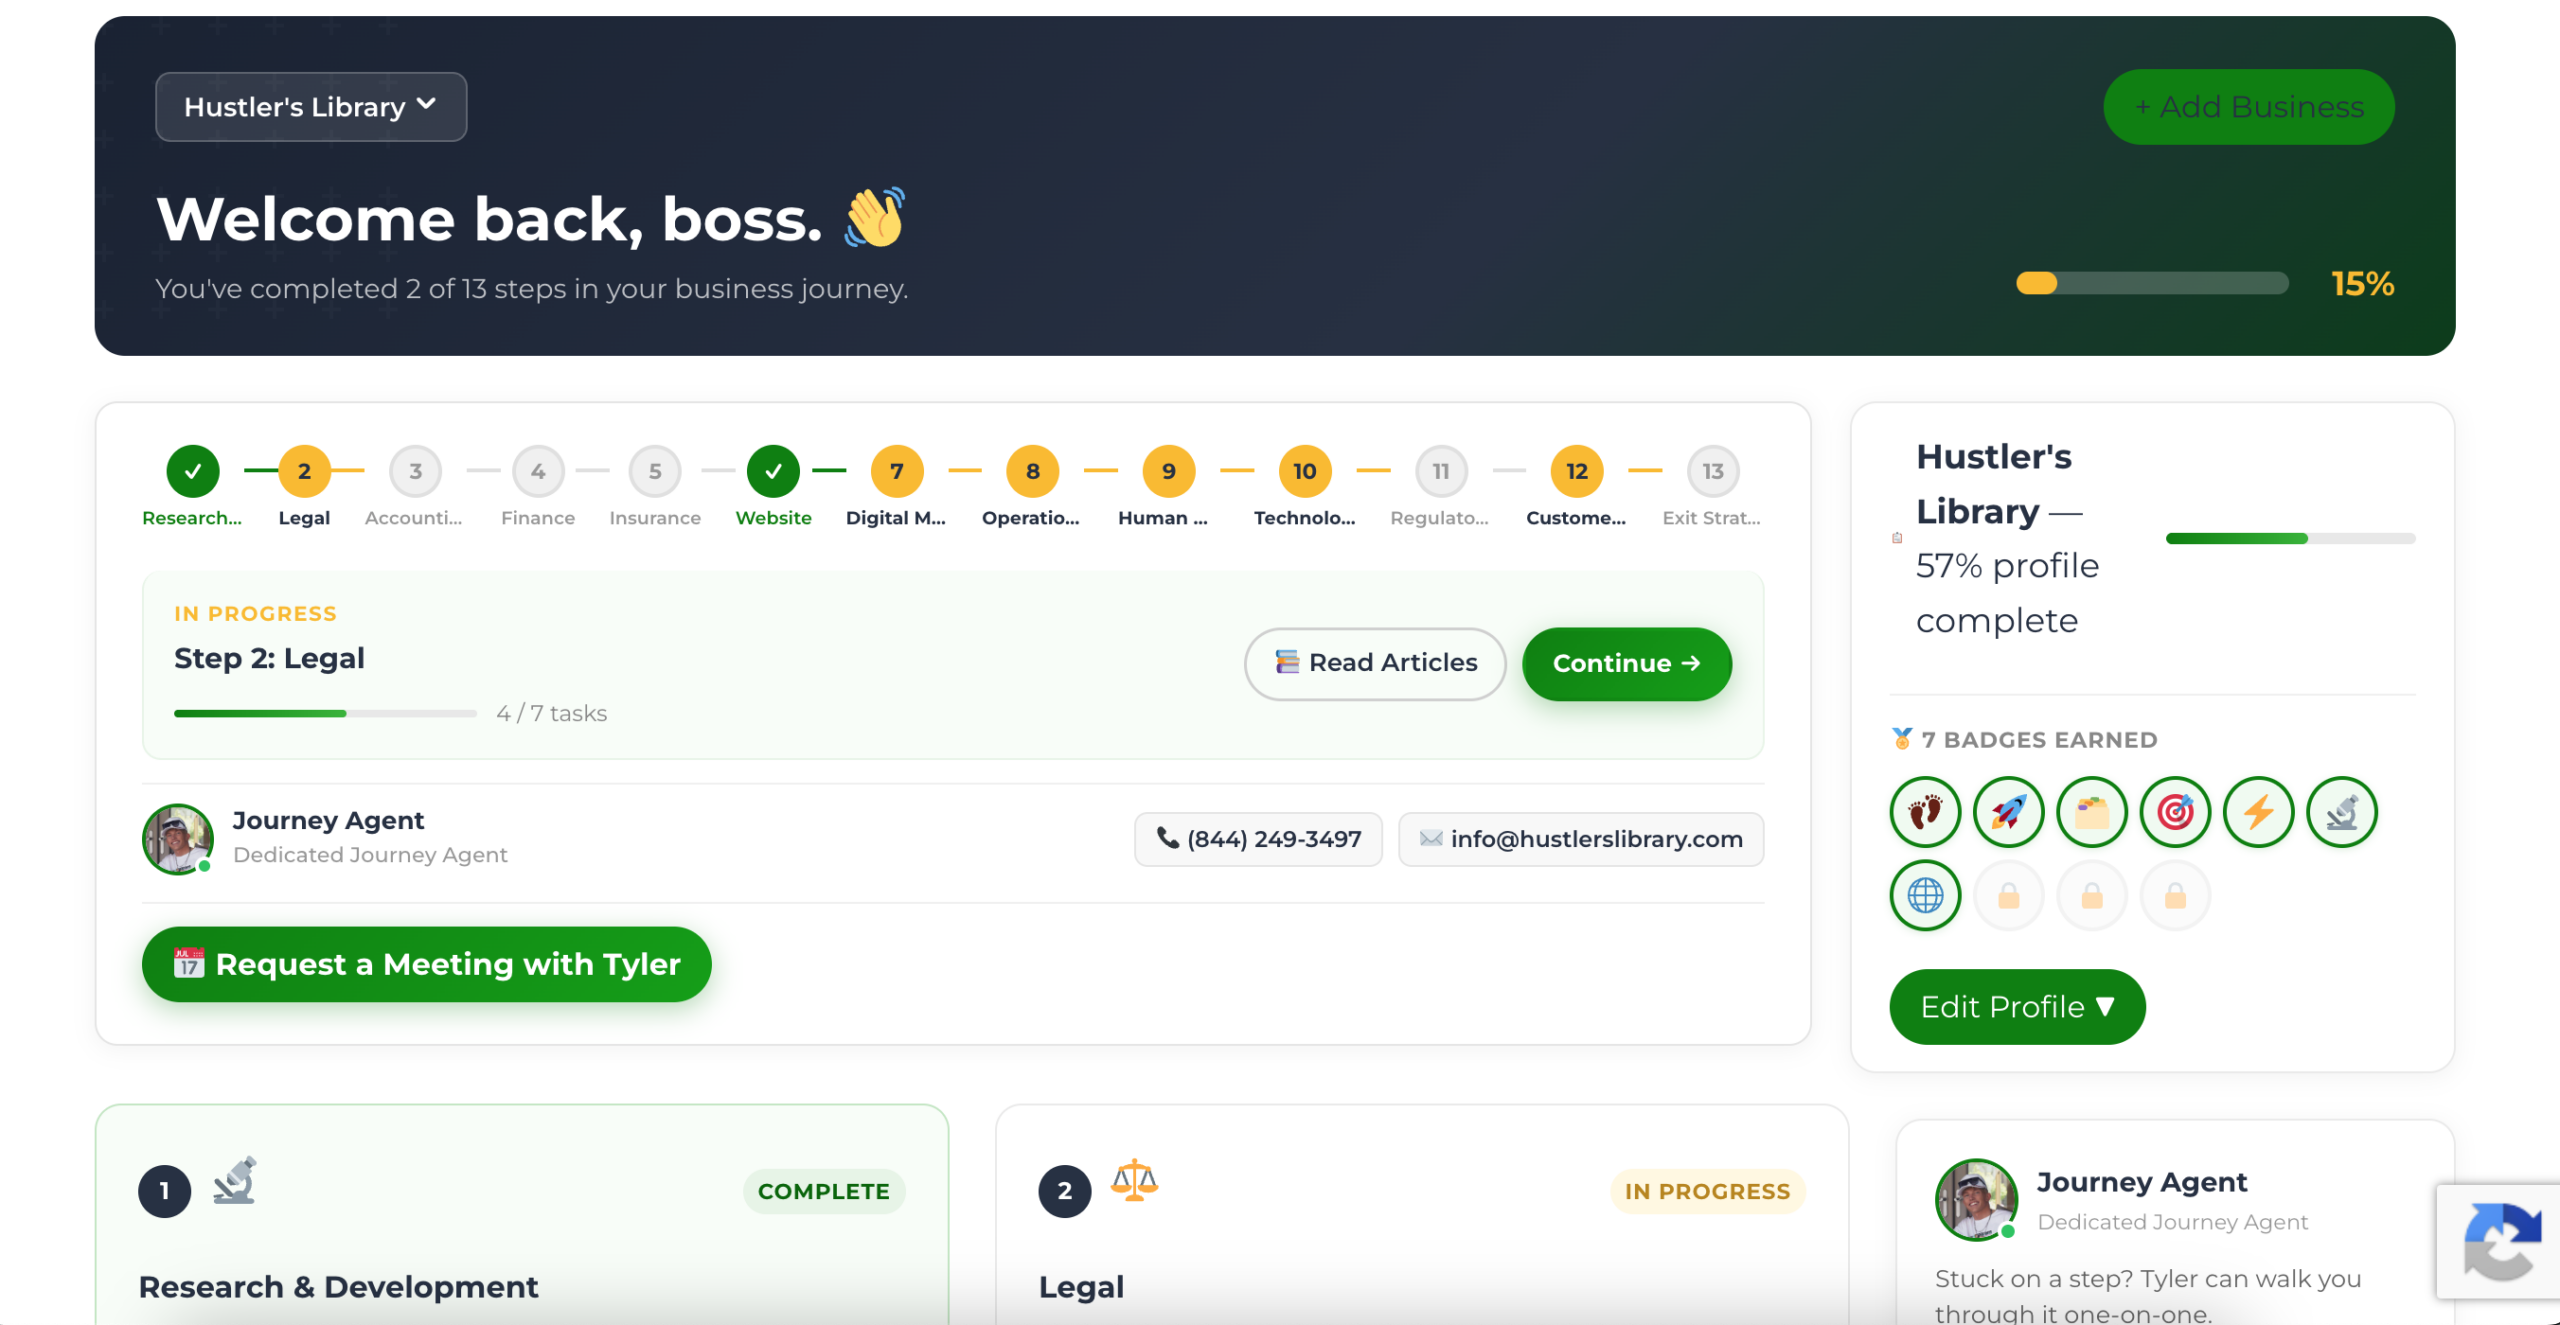
The Business Journey dashboard maps your exact position across all 13 stages. Track your progress, unlock resources for each step, and build with a framework used by thousands of founders at Hustler's Library.
No credit card required · Takes 3 minutes · Personalized to your stage