
You ran the numbers before you launched. You knew about rent, inventory, maybe a few subscriptions. You felt prepared.
Then reality showed up.
The hidden costs of running a small business have a way of arriving quietly and compounding fast. Most owners don’t get blindsided by one big expense; they get nickeled and dimed by a dozen costs they never planned for. By the time they realize what’s happening, cash is tight and the margin that looked healthy on paper has quietly evaporated.
This guide is a plain-English look at the costs most business owners underestimate or miss entirely; and what you can do to budget for them before they catch you off guard.
Why Hidden Costs Hit Harder Than Expected
When you build a startup budget, you tend to list the obvious: your monthly rent, your software tools, your cost of goods. What most people don’t budget for are the soft costs, the irregular costs, and the costs that only appear once you start operating at scale.
These hidden costs fall into a few categories: costs you didn’t know existed, costs you knew about but underestimated, and costs that seem small until they add up. All three can quietly drain your cash flow and make an otherwise healthy business feel financially stressed.
1. The Real Cost of Your Own Time
This is the hidden cost almost no one accounts for. When you’re the owner, you don’t get a paycheck for every hour you work; and those hours are expensive.
If you’re spending 10 hours a week on bookkeeping, that’s 10 hours you’re not spending on sales, client work, or growth. At whatever your billable rate is, that’s a significant number. Many owners avoid outsourcing tasks because they feel “free,” but the opportunity cost is real.
Budget for this by assigning a dollar value to your time, even informally. When you’re deciding whether to do something yourself or outsource it, run the math. Often, delegating is cheaper than it looks.
2. Employer Taxes and Benefits
If you have employees or plan to hire, the sticker price of a salary is just the beginning. As an employer, you’re responsible for your share of FICA taxes (Social Security and Medicare), federal and state unemployment taxes, and potentially workers’ compensation insurance.
A rough rule of thumb: budget an additional 15 to 25 percent on top of base wages for payroll taxes and mandatory costs. Add benefits like health insurance, PTO, and retirement contributions, and the real cost of a $50,000 employee can easily reach $65,000 or more.
Many first-time employers get hit hard by this. Build it into your hiring budget from day one.
3. Software Subscriptions That Stack Up
You sign up for accounting software. Then a project management tool. Then a scheduling app, a CRM, an email marketing platform, a file storage service, a design tool, a video conferencing license, and a handful of add-ons for each.
Individually, these feel small: $15 here, $49 there. But a typical small business is running 15 to 25 software subscriptions, and the total monthly bill can easily exceed $500 to $1,500 or more.
Do a software audit at least once a year. List every subscription, what it costs, and whether your team actually uses it. Most businesses find they’re paying for tools that went dormant months ago. Cut aggressively; you can always re-subscribe if you need to.
4. Credit Card and Payment Processing Fees
Every time a customer pays you by card, you pay a processing fee; typically between 2 and 3.5 percent per transaction. That might seem trivial on a single sale, but at scale it adds up fast.
On $500,000 in annual card revenue, you’re handing over $10,000 to $17,500 in processing fees alone. Most owners track revenue carefully but never audit what they’re spending on payment processing. Review your processor’s fee structure annually and shop around; rates vary significantly.
Also watch for hidden fees: monthly minimums, chargeback fees, PCI compliance fees, and batch settlement fees. These rarely show up in the headline rate but appear quietly on your statement every month.
5. Professional Services: Legal, Accounting, and Consulting
You’ll need a lawyer at some point. An accountant at tax time. Maybe a consultant to help you solve a specific problem. These costs are easy to ignore in your annual budget because they’re irregular; but they’re predictable if you plan for them.
Build a line item for professional services. Even if you don’t use it every month, having $300 to $500 set aside per month means you’re not scrambling when you need a contract reviewed, a tax question answered, or an HR issue resolved quickly.
Deferred legal and accounting help tends to be far more expensive than proactive help. The $500 contract review today beats the $15,000 lawsuit next year.
6. Equipment Repair and Replacement
Computers break. Printers jam and die. HVAC systems fail in August. Vehicles need service. Kitchen equipment needs calibration. Whatever physical assets you rely on, they will need repair and eventual replacement; and it will rarely happen at a convenient time.
A good rule of thumb: budget 5 to 10 percent of your equipment’s value annually for maintenance and replacement reserves. If you have $30,000 in equipment, set aside $1,500 to $3,000 per year in a dedicated fund. When something fails, you have the cash. When it doesn’t, the fund grows for future replacements.
For more on managing this, see our guide on how to manage business equipment, maintenance, and replacement budgeting.
7. Marketing Costs You Didn’t Expect
Even if you’re doing mostly organic or word-of-mouth marketing, there are real costs involved. A professional photo shoot for your website or social media. A graphic designer to create branded materials. Paid ads that cost more than you expected to turn a profit. Sponsorships or event booths. Branded merchandise.
Marketing budgets are often set too low in year one because owners think “we’ll figure it out as we go.” The businesses that grow fastest tend to treat marketing spend as a fixed cost, not a variable one they cut when things get tight. Budget for it deliberately, even if you start small.
8. Turnover and Hiring Costs
Losing an employee is expensive in ways that don’t show up on your P&L. There’s the cost to recruit a replacement: job postings, interview time, background checks. There’s the cost of lost productivity during the gap. There’s the training time for the new hire. And there’s the knowledge that walked out the door.
Research consistently estimates that replacing an employee costs between 50 and 200 percent of their annual salary. For a $40,000 employee, that’s $20,000 to $80,000. Most small business owners never account for this in their financial models.
Budget for turnover the same way you’d budget for equipment repair: assume it will happen at some point, and have a reserve. Investing in retention, through competitive compensation, clear growth paths, and a strong culture, pays for itself many times over.
9. Banking Fees, Interest, and Financial Overhead
Monthly banking fees, wire transfer costs, overdraft charges, interest on a line of credit, loan origination fees; these financial overhead costs are often invisible until you add them up.
If you’re carrying any debt, model the true cost of that capital. A $50,000 business line of credit at 9 percent APR costs $4,500 per year in interest if you’re drawing it regularly. A merchant cash advance can carry effective rates far higher. Know what you’re paying and why.
Also review your bank statements quarterly for fees you’ve forgotten about: wire fees, account maintenance charges, and ACH processing costs. They’re small, but they accumulate.
10. Taxes You Forgot to Set Aside
Self-employment taxes. Quarterly estimated payments. Sales tax for states you didn’t realize you had nexus in. Payroll tax deposits. Business property taxes. Franchise or gross receipts taxes in certain states.
Tax obligations expand as your business grows, and missing them comes with penalties. The safest approach: set aside 25 to 30 percent of every dollar of profit into a dedicated tax account. It sounds like a lot, but it’s far better than facing a five-figure tax bill you didn’t see coming.
The IRS has resources on estimated taxes for small business owners that can help you stay ahead of quarterly obligations and avoid underpayment penalties.
How to Budget for Hidden Costs
Once you know what to look for, budgeting for hidden costs becomes straightforward. Here’s the framework:
- Build a true cost of revenue. Include all direct costs to deliver your product or service; not just materials or labor, but processing fees, software, and time.
- Create a “slush fund” line item. Budget 5 to 10 percent of projected monthly operating expenses as an unallocated buffer for unexpected costs.
- Review actuals vs. budget quarterly. Find where you overspent and why. Recurring surprises are a signal to add a permanent line item.
- Separate reserves from operating cash. Equipment replacement reserves, tax set-asides, and emergency funds should sit in separate accounts so you’re not accidentally spending them.
- Track every subscription and vendor. One review per quarter; cancel what you don’t use, renegotiate what you do.
For a deeper look at how to structure your financial tracking, see our guide on mastering financial literacy as a small business owner.
The Owners Who Stay Ahead
The small business owners who build lasting companies aren’t necessarily the ones with the most revenue. They’re the ones who know exactly what it costs to run their business; including the costs that don’t show up on the first budget. They plan for the irregular, reserve for the inevitable, and treat financial visibility as a competitive advantage.
Hidden costs don’t have to stay hidden. Once you know where to look, you can budget for them, control them, and make smarter decisions about where your money actually goes.
Want more resources to help you run a smarter, more profitable business? Join Hustler’s Library for free and get access to practical guides, tools, and insights built for business owners who are serious about growth.
Ready to Know Where You Stand?
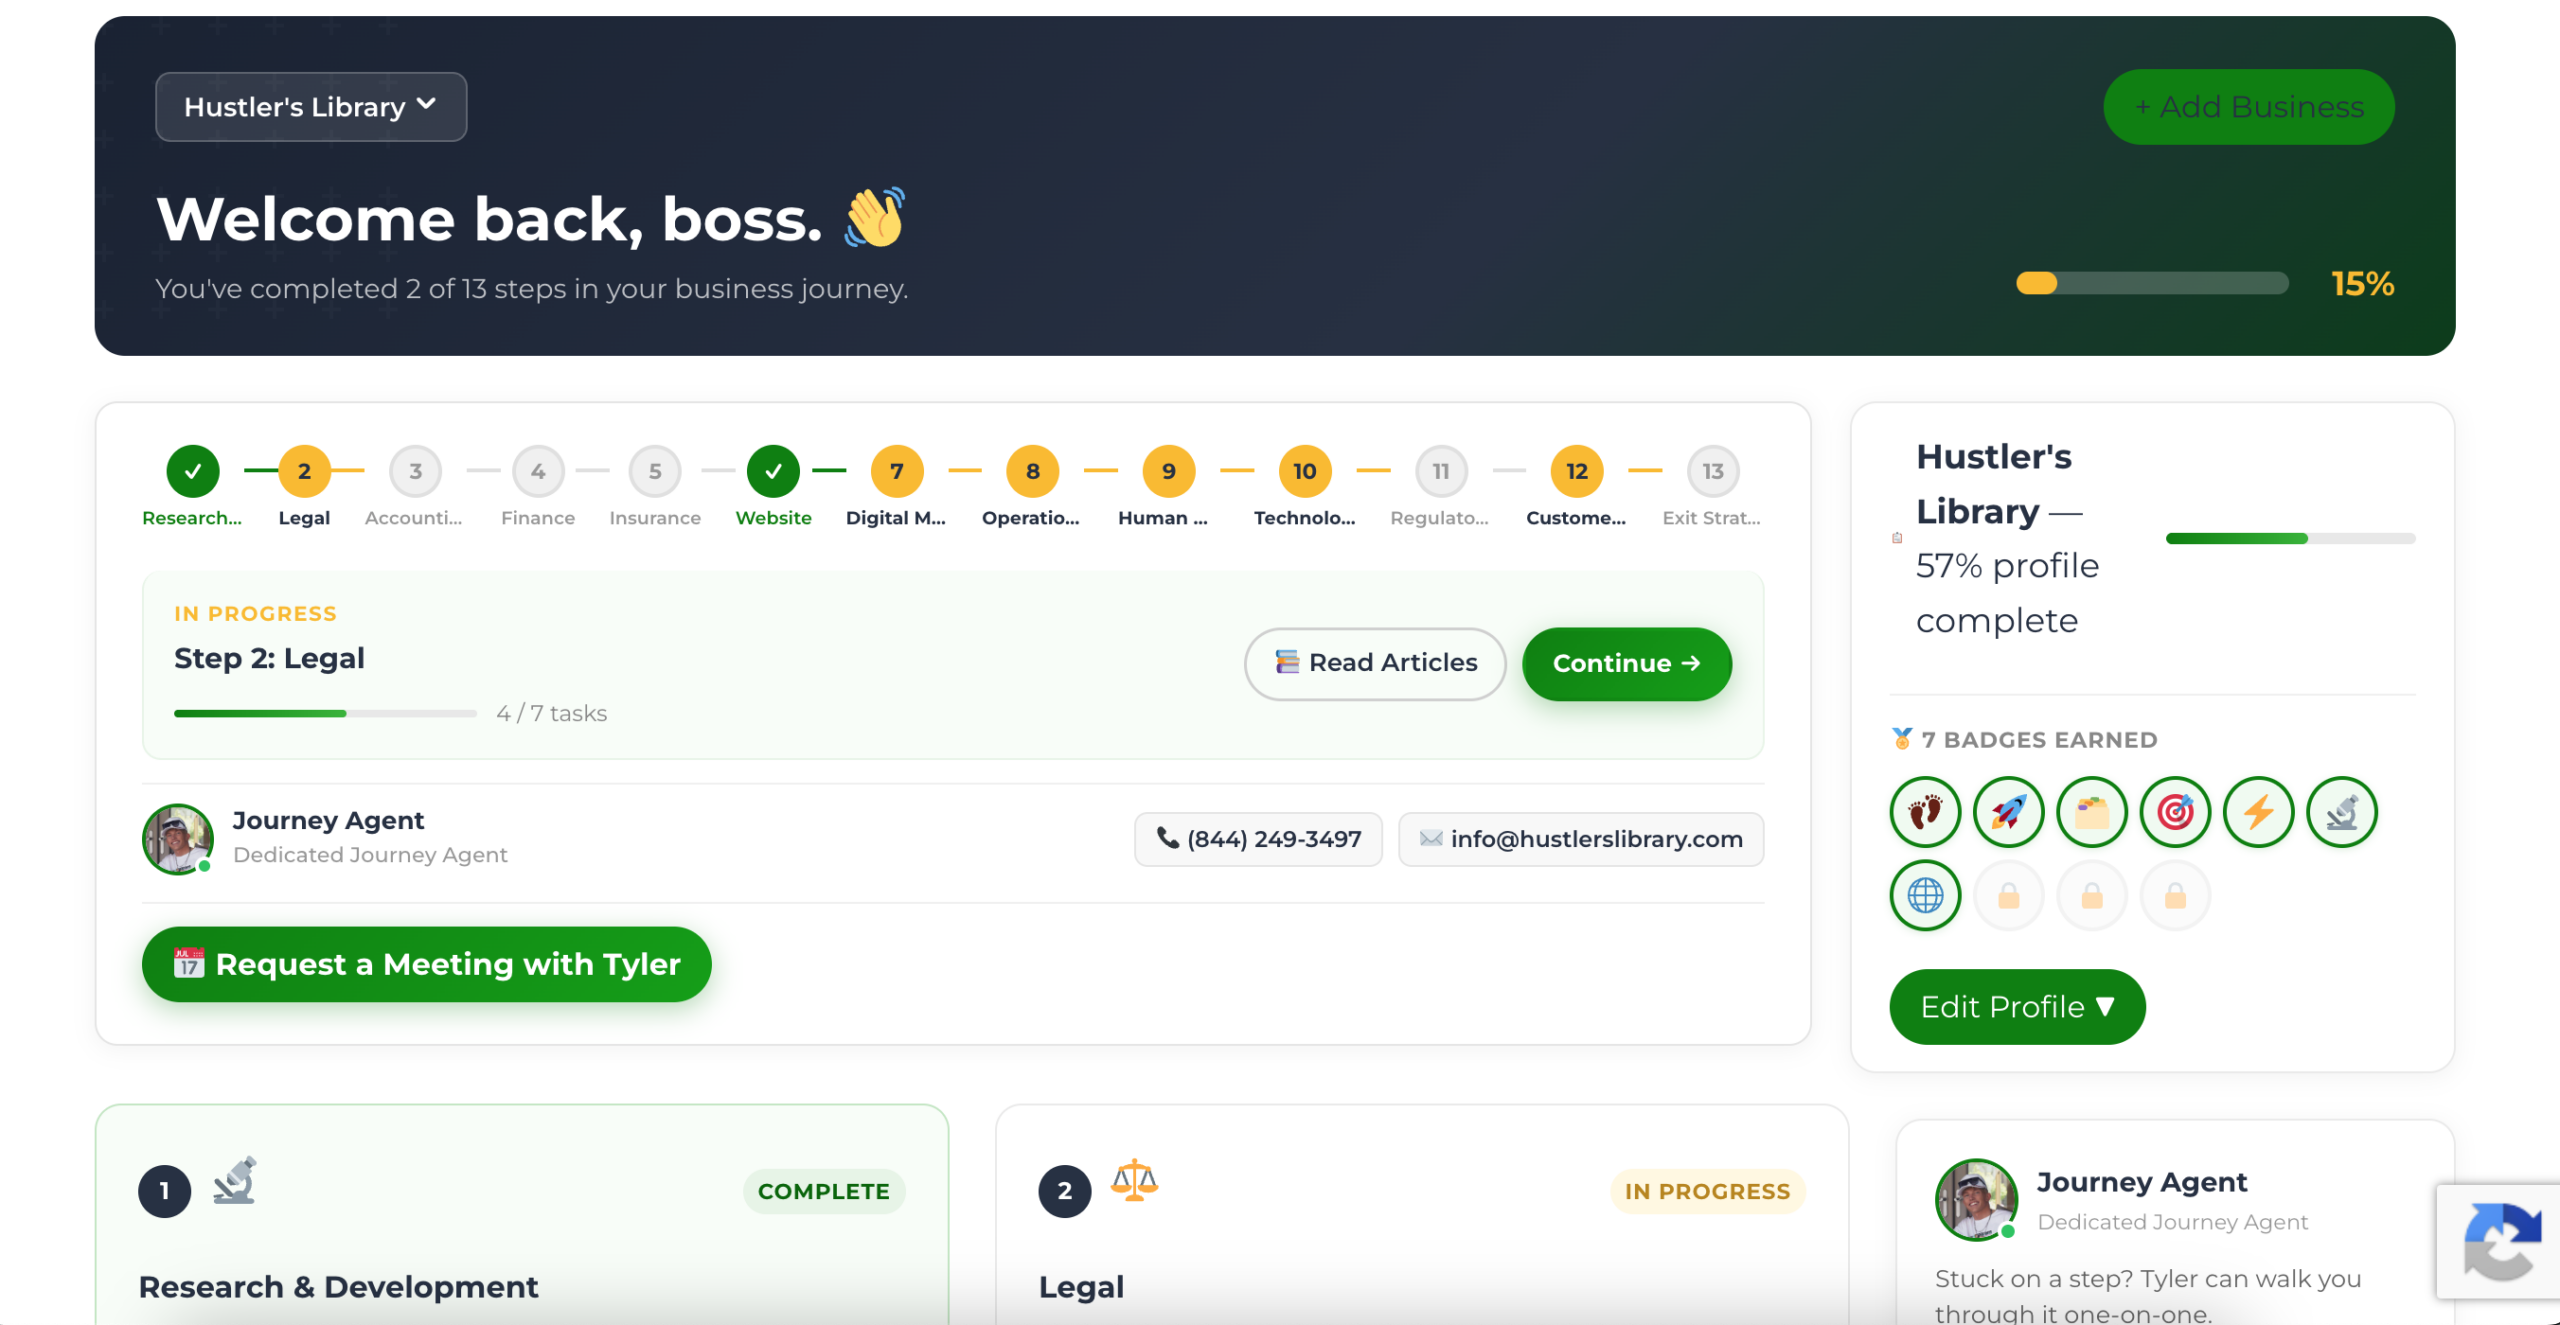
The Business Journey dashboard maps your exact position across all 13 stages. Track your progress, unlock resources for each step, and build with a framework used by thousands of founders at Hustler's Library.
No credit card required · Takes 3 minutes · Personalized to your stage