If your small business needs capital and traditional banks keep saying no, micro-lending might be exactly what you have been looking for. It is one of the most accessible, flexible, and underutilized funding tools available to small business owners, yet most entrepreneurs have never seriously explored it.
This guide breaks down what micro-lending is, who it is for, where to find it, and how to use it strategically to grow your business without taking on more debt than you can handle.
What Is Micro-Lending?
Micro-lending refers to small loans, typically ranging from a few hundred dollars to $50,000, that are issued by non-traditional lenders to small businesses and entrepreneurs who may not qualify for conventional bank financing. The term comes from the microfinance movement, which originally focused on providing tiny loans to entrepreneurs in developing countries, but the model has taken strong root in the United States and other developed economies.
In the U.S., the Small Business Administration runs a dedicated Microloan Program that provides loans up to $50,000 through a network of approved nonprofit intermediary lenders. The average SBA microloan is around $13,000. These loans are designed to help startups and small businesses that lack the credit history, collateral, or revenue to qualify for traditional financing.
Beyond the SBA, platforms like Kiva, Accion Opportunity Fund, and dozens of Community Development Financial Institutions (CDFIs) offer micro-loans with varying terms, rates, and eligibility requirements.
Who Is Micro-Lending For?
Micro-lending is not just for businesses in financial trouble. It is a legitimate strategic tool for:
- Early-stage businesses that need seed capital to get off the ground but do not yet have the revenue history banks require
- Businesses with thin or damaged credit that would not pass a traditional underwriting process
- Minority, women-owned, and veteran-owned businesses that have historically faced barriers to traditional lending
- Service-based businesses with few hard assets to offer as collateral
- Established small businesses that need a quick infusion of capital for equipment, inventory, or hiring without going through a lengthy bank approval process
If you have ever felt like the banking system was not built for someone in your position, you are probably right. Micro-lending programs were explicitly designed to fill that gap.
The Main Sources of Micro-Loans in the U.S.
SBA Microloan Program
The SBA does not lend directly. Instead, it provides funds to approved nonprofit intermediaries, which then lend to small businesses. These intermediaries often provide business training and technical assistance alongside the loan, which is a significant advantage for newer business owners. Interest rates typically range from 8 to 13 percent, and repayment terms can extend up to six years. Visit SBA.gov to find an approved microloan intermediary in your area.
Kiva
Kiva is one of the most interesting micro-lending platforms available to U.S. business owners. Through Kiva, you can borrow up to $15,000 at zero percent interest. The catch is that you need to build a network of supporters who fund your loan before it goes live to the broader Kiva community. It is part fundraising campaign and part loan application, but for businesses that can mobilize their community, it is an extraordinary deal.
Accion Opportunity Fund
Accion is one of the largest nonprofit small business lenders in the U.S. They offer loans from $5,000 to $250,000 and specifically focus on underserved entrepreneurs, including women, immigrants, and business owners in low-income communities. They also provide one-on-one coaching and resources beyond just the capital.
Community Development Financial Institutions (CDFIs)
CDFIs are mission-driven lenders that serve communities underserved by traditional finance. There are over a thousand CDFIs across the country, many focused on specific geographies, industries, or borrower demographics. The CDFI Fund, run by the U.S. Department of the Treasury, maintains a searchable database you can use to find certified CDFIs in your area.
State and Local Programs
Many states, cities, and counties run their own micro-lending programs, often targeted at specific industries or communities. These programs can be harder to find but frequently offer the most favorable terms. Your local Small Business Development Center (SBDC) or chamber of commerce can help you identify what is available in your area.
How to Prepare a Strong Micro-Loan Application
Even though micro-loans have more flexible standards than bank loans, you still need to come prepared. Here is what most lenders want to see:
- A clear purpose for the funds. Vague answers like “working capital” do not inspire confidence. Know exactly what you plan to spend the money on and why it will help the business grow.
- Basic financial statements. Even simple records showing your revenue, expenses, and bank statements for the past few months help lenders understand your current situation. If you have not already set up a clean bookkeeping system, start there first.
- A business plan or summary. It does not need to be elaborate, but you should be able to explain what your business does, who your customers are, and how you make money.
- A realistic repayment plan. Lenders want to know how you will pay the money back. Walk them through your revenue projections and how the loan will help generate the income needed to cover repayments.
- Personal financial information. Most micro-lenders will pull your personal credit score and want to see that you are managing your personal finances responsibly, even if your business credit is thin.
If you want to sharpen your financial literacy before going through the application process, our guide on mastering financial literacy as a small business owner is a good place to start.
How to Use Micro-Loan Capital Strategically
Getting the money is only half the battle. Using it wisely is what determines whether a micro-loan becomes a growth catalyst or a burden. Here are the highest-impact ways small business owners typically deploy micro-loan capital:
Equipment and Inventory
Tangible assets with a clear return on investment are one of the smartest uses of micro-loan funds. If buying a piece of equipment or stocking up on inventory allows you to take on more orders, serve more customers, or improve your margins, the math is usually favorable.
Hiring and Payroll Bridge
Sometimes businesses have strong pipeline but need to hire before the revenue hits. A micro-loan can bridge that gap, allowing you to bring on the talent you need to fulfill growing demand without waiting until the cash fully catches up.
Marketing and Customer Acquisition
Investing loan capital in proven marketing channels with measurable results can pay for itself quickly. The key is tracking your cost per acquisition so you know whether the investment is generating returns that outpace the loan’s interest cost.
Building Credit History
One of the most overlooked benefits of micro-lending is its role in building a business credit profile. Successfully borrowing and repaying a micro-loan creates a track record that makes future, larger loans easier to obtain on better terms. Think of your first micro-loan as a stepping stone to the capital stack you will need as the business grows.
Micro-Lending vs. Other Funding Options
Micro-lending is not the only alternative to traditional bank loans. It is worth understanding how it compares to other options:
- Micro-lending vs. trade credit: Trade credit from your suppliers is often interest-free but limited to specific purchases. Micro-loans give you cash flexibility. If you want to explore trade credit as a complementary tool, our guide to using trade credit for growth breaks it down step by step.
- Micro-lending vs. crowdfunding: Crowdfunding can raise capital without repayment obligations, but it requires significant marketing effort and public exposure. Micro-loans are quieter, faster, and do not require you to give up equity or publicly campaign for support.
- Micro-lending vs. credit cards: Business credit cards are convenient but carry much higher interest rates. A micro-loan at 8 to 10 percent beats a credit card at 22 to 28 percent for any purchase you cannot immediately pay off.
- Micro-lending vs. grants: Grants do not need to be repaid, but they are competitive, highly specific in their requirements, and often slow to arrive. Micro-loans are faster and more accessible for general business use.
Common Mistakes to Avoid
Micro-lending can be a powerful tool, but it is not without risk. Watch out for these common pitfalls:
- Borrowing more than you need. Just because you can borrow $50,000 does not mean you should. Borrow the minimum amount that achieves your specific goal and keep your debt obligations manageable.
- Using loan funds for operating expenses without a plan. Using a loan to cover ongoing expenses without a clear path to increased revenue is a warning sign. Loan capital should be deployed to generate returns, not to paper over a structural cash flow problem.
- Skipping the technical assistance. Many micro-lenders offer free business coaching, workshops, and advisory services alongside their loans. These are often more valuable than the money itself. Do not leave them on the table.
- Missing payments and damaging your credit. One of the main benefits of a micro-loan is building your credit profile. A missed payment undermines that entirely and can make future funding much harder to obtain. Build your repayment schedule into your cash flow projections before you borrow.
The Bottom Line
Micro-lending is not a consolation prize for businesses that could not get a real loan. It is a purpose-built financing tool that has helped hundreds of thousands of entrepreneurs in the United States launch, stabilize, and scale their businesses. If you have been held back by a lack of capital and felt like the traditional banking system was not built for you, the micro-lending ecosystem was literally designed to serve people in your position.
Start by identifying one specific growth need in your business, calculate how much capital it would take to address it, and reach out to your nearest SBA-approved microloan intermediary, CDFI, or Kiva. You may be closer to the capital you need than you think.
Want more tools and strategies for growing your business? Join thousands of small business owners who get practical, no-fluff advice delivered straight to their inbox. Join Hustler’s Library for free today.
Ready to Know Where You Stand?
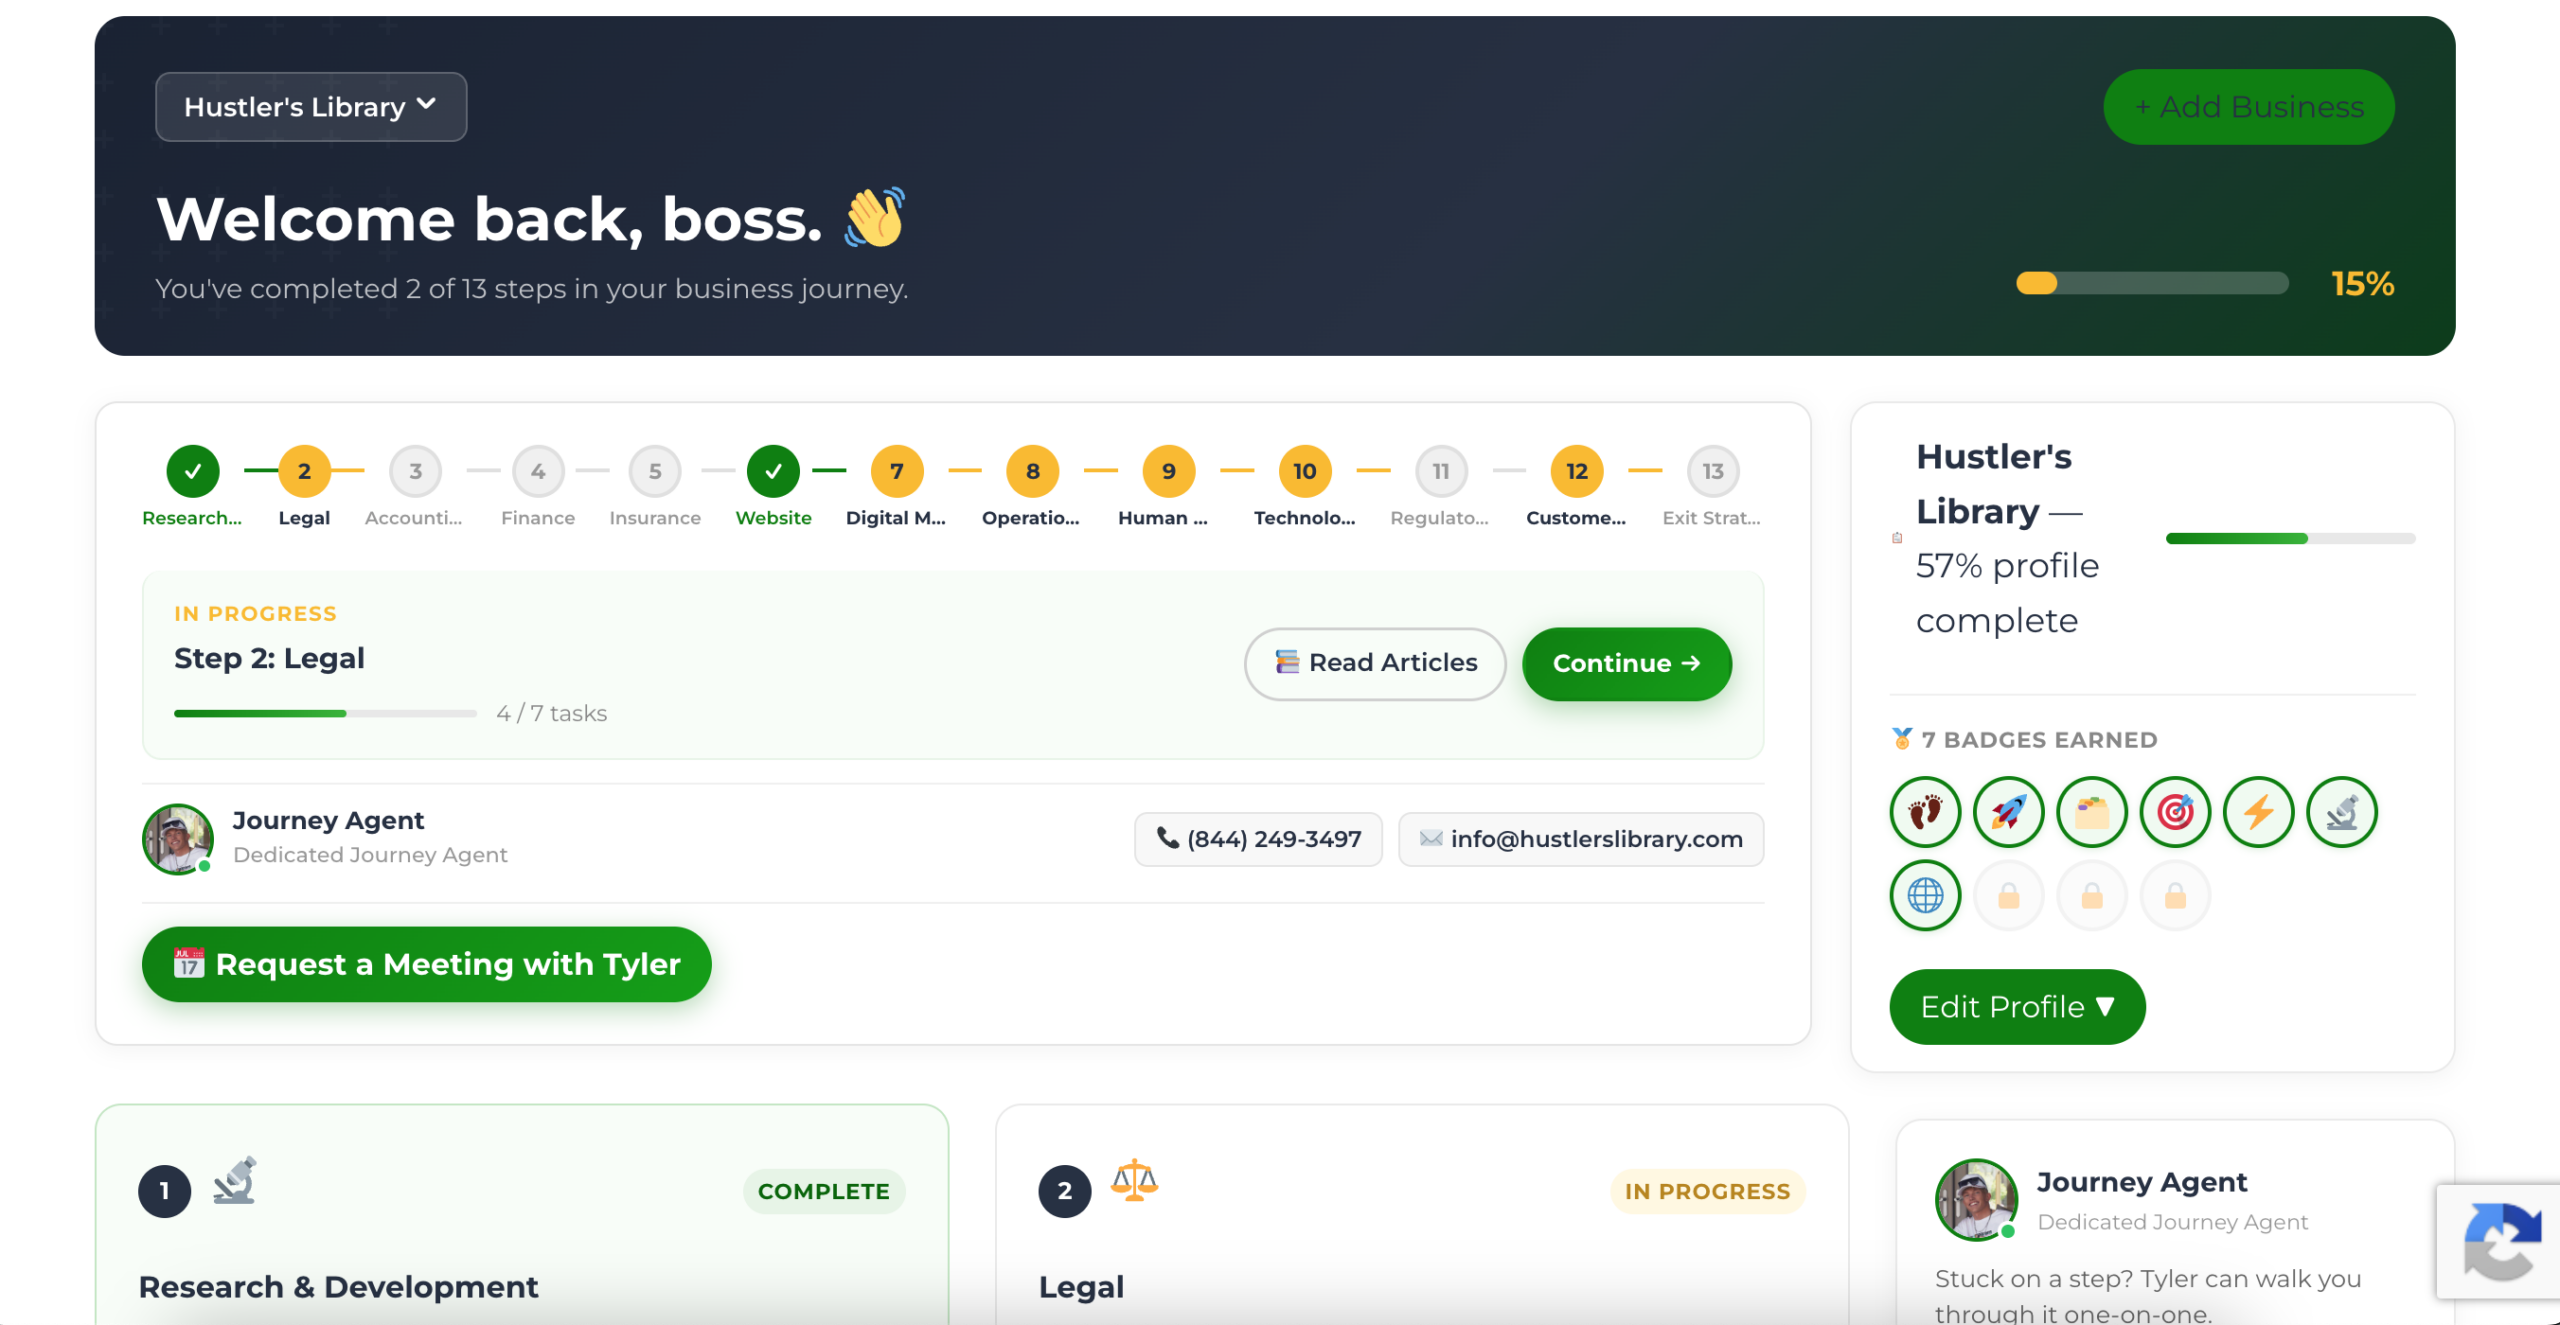
The Business Journey dashboard maps your exact position across all 13 stages. Track your progress, unlock resources for each step, and build with a framework used by thousands of founders at Hustler's Library.
No credit card required · Takes 3 minutes · Personalized to your stage