One of the fastest ways to build business credit from zero is through net-30 vendor accounts. These accounts let you purchase goods or services and pay the invoice within 30 days. What makes them powerful for credit building is that many of these vendors report your payment history directly to business credit bureaus. Done correctly, you can have a measurable Paydex score within 60 to 90 days of opening your first accounts. This guide covers what net-30 accounts are, which ones actually report, and how to use them strategically.
What Does Net-30 Mean?
Net-30 is a payment term that means the full invoice amount is due within 30 calendar days of the invoice date. If you purchase 50 worth of office supplies under net-30 terms, you have 30 days to pay the bill in full. There is no interest if you pay within the window, and no minimum monthly payment. You either pay on time or you do not.
From a credit-building standpoint, the key is that your vendor reports your payment behavior to D&B, Experian, or Equifax. When you pay on time or early, that positive data flows into your credit file and builds your score. When you pay late, it damages your score. The mechanics are similar to personal credit, but the scoring timelines and thresholds differ.
For context on how these payment histories factor into your overall scores, see our breakdown of how to build business credit from scratch.
Why Net-30 Accounts Are the Best Starting Point
Most new businesses cannot qualify for business credit cards or bank loans right away. Their credit profiles are either nonexistent or too thin to satisfy underwriting requirements. Net-30 vendor accounts fill that gap. Many of them have low approval requirements, no personal credit check, and no annual fee. They are specifically designed for business-to-business purchasing, which means vendors expect newer businesses to apply.
The goal is not to maximize spending on these accounts. The goal is to generate consistent, positive payment data that populates your credit file across multiple bureaus. Even a 5 purchase paid five days early counts as a positive reporting event.
Net-30 Accounts That Actually Report to Business Credit Bureaus
Not every vendor that offers net-30 terms reports to credit bureaus. Many small vendors simply have no reporting relationship with D&B, Experian, or Equifax. The accounts listed below are widely recognized for their reporting practices.
Uline
Uline is a major distributor of shipping supplies, packaging materials, and warehouse equipment. They offer net-30 terms to businesses and report payment history to D&B. Approval is relatively straightforward for most registered businesses. To qualify for net terms, you typically need to submit a credit application and provide your DUNS number or EIN. Uline purchases are practical for any business that ships physical products or needs office and warehouse supplies.
Quill
Quill is an office supply company (owned by Staples) that offers net-30 terms and reports to both D&B and Experian Business. This makes Quill especially valuable because a single account can contribute to two bureau profiles simultaneously. Their product catalog covers office supplies, cleaning products, technology accessories, and breakroom supplies. Quill is widely recommended by business credit coaches as one of the best starter accounts because of its dual reporting.
Grainger
Grainger is an industrial supply company that sells safety equipment, tools, maintenance supplies, and facility products. They offer net-30 terms and report to D&B. Grainger accounts are particularly useful for businesses in construction, manufacturing, logistics, or any field that requires equipment and supplies. Their approval process is more selective than some of the other vendors on this list, so it works best once you have at least one or two other accounts already reporting.
Crown Office Supplies
Crown Office Supplies is one of the most accessible net-30 vendors for brand-new businesses. They are known for easy approval even with a thin or nonexistent credit file, and they report to all three major business credit bureaus: D&B, Experian, and Equifax. This triple reporting makes Crown a high-value starter account. Products include office supplies, pens, paper, and desk accessories. The purchases are small, but the reporting impact is significant for a new profile.
Wise Business Plans
Wise Business Plans is a business plan writing service that offers net-30 payment terms and reports to D&B. This account is useful for businesses that legitimately need a business plan document for investor presentations, bank loan applications, or planning purposes. It adds a service-based trade line to your profile, which diversifies the types of accounts reported.
Creative Analytics
Creative Analytics is a marketing and analytics services provider that offers net-30 terms and reports to D&B. Like Wise Business Plans, this is a service-based vendor account that helps diversify your trade line mix beyond just supply purchases. It is an accessible option for businesses that want to round out their D&B profile.
The Right Strategy for Using Net-30 Accounts
Open Three to Five Accounts
One or two net-30 accounts will not generate a Paydex score. D&B requires at least three vendors reporting payment data before it will produce a score. Open three to five accounts in your first 30 days of building credit, then use all of them consistently.
Make Small Purchases Every Month
You do not need to spend large amounts. A 0 to 5 purchase each month per vendor is sufficient to keep the account active and generate monthly reporting cycles. Only buy things your business actually needs. The point is regular activity, not large balances.
Pay Five to Seven Days Early
Paying on the due date is good. Paying five to seven days before the due date is better. The D&B Paydex score is weighted toward how early you pay, not just whether you pay on time. A pattern of early payments can push your score toward 90 or even 100 over time, which signals to vendors and lenders that you are a low-risk business partner.
According to Dun & Bradstreet’s own guidance on building business credit, early payment is the single most effective lever for maximizing your Paydex score.
For the complete picture of what your business credit reports contain and how to read them, see our guide on how to build business credit.
What to Expect in the First 90 Days
In the first month, you will be approved for accounts and making your first small purchases. In months two and three, vendors will begin submitting payment reports to the bureaus. By the end of month three, if you have three or more vendors reporting consistent on-time or early payments, you should have a Paydex score of at least 80, which is the benchmark that most vendors use to extend trade credit without requiring a personal guarantee.
This is the foundation. From here, you move on to business credit cards and eventually bank financing, all with a real credit profile backing you up.
Ready to Build Smarter?
Get access to our full library of business guides, tools, and resources.
Tools like Credit Karma can help you monitor your business credit profile as it builds.
Ready to Know Where You Stand?
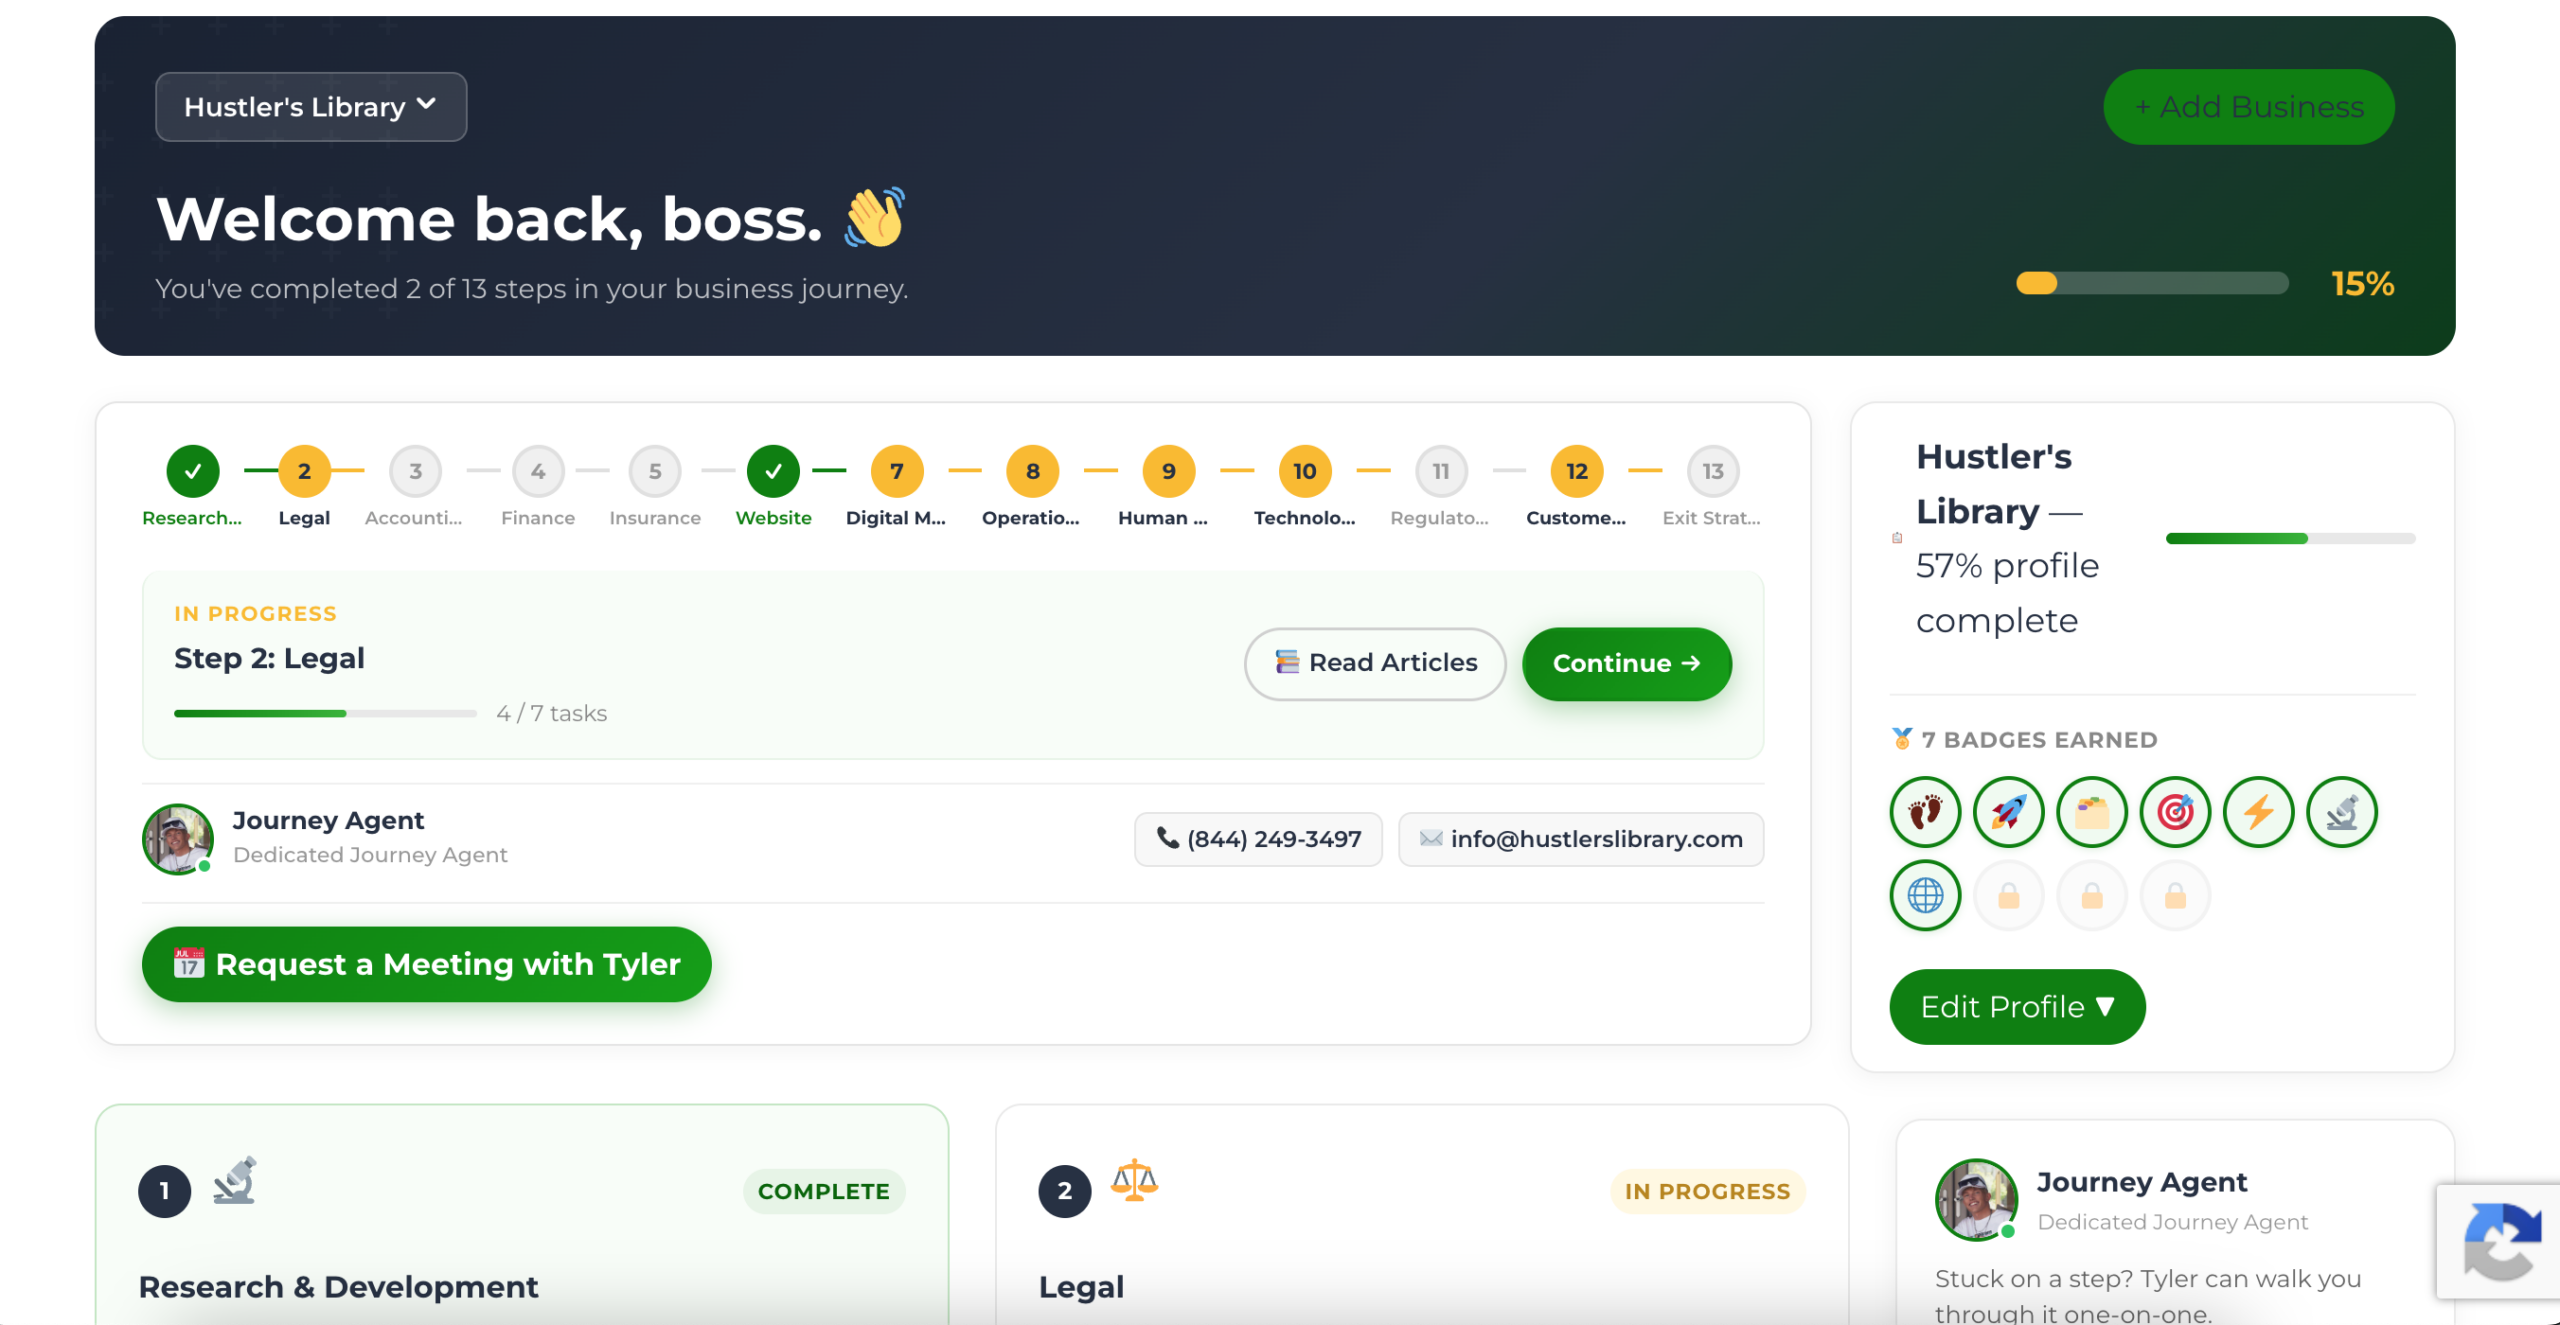
The Business Journey dashboard maps your exact position across all 13 stages. Track your progress, unlock resources for each step, and build with a framework used by thousands of founders at Hustler's Library.
No credit card required · Takes 3 minutes · Personalized to your stage