If you’ve ever driven for a rideshare app, freelanced on Upwork, or run a one-person LLC, you already know the frustration: W-2 employees clock out and their employer drops 3% to 6% into a 401(k) on their behalf. You? You get nothing. That gap has quietly been one of the most punishing financial penalties of the independent-worker economy — and according to 24/7 Wall St., it may finally be closing. A new government-backed retirement savings vehicle — American Dream Accounts — is aimed squarely at the estimated 50 million U.S. workers without access to an employer-sponsored plan, offering a federal match of up to $1,000 annually for contributions invested in low-cost index funds.
Jessica Anderson, spokesperson for the Save Match Grow advocacy campaign, laid it out on CNBC: “Think of it like a TSP, a thrift savings plan. But now for all these workers — gig economy workers, small business owners, entrepreneurs — they now have access to this long-term investment vehicle, something that they would never have access to before.”
What This Actually Means
For side hustlers and independent workers, this is more than a policy footnote. It’s a structural shift in how wealth-building works outside traditional employment.
Here’s the practical math: contribute $2,000 a year, receive the federal match up to $1,000, put the combined $3,000 into a stock index fund averaging 8% to 10% annually, and that money compounds over 40+ years into a seven-figure balance. The match nearly doubles your contribution before you’ve earned a single dollar in returns. That’s the entire game.
The other piece that matters for the gig-economy crowd: portability. If you stitch together income from three different platforms — delivery on Monday, client consulting on Tuesday, Etsy sales on Wednesday — a 401(k) has never worked for you. It’s tied to an employer. American Dream Accounts follow the worker, not the job.
The structure tracks closest to a traditional IRA on the tax side: contributions go in, growth compounds, and withdrawals in retirement are taxed as ordinary income. The plumbing is familiar. The access is new.
The Numbers Behind It
The scale of who this affects is significant. According to Bankrate, 39% of Americans currently have a side hustle as of 2025 — and most of them have no employer-sponsored retirement plan tied to that income. The Bureau of Labor Statistics reported that self-employment in technical services grew 14% between 2023 and 2025, a sign that the independent-worker economy isn’t a temporary detour — it’s the direction of travel.
The retirement gap for these workers is real and measurable. A Department of Labor analysis found that roughly half of private-sector workers lack access to a workplace retirement plan at any given time, a figure that skews heavily toward contractors, freelancers, and part-time workers. If a person in this group contributes even $1,200 a year — 3% of a $40,000 income — with the federal match bringing that to $2,200, Anderson’s CNBC projection puts their 40-year balance near $1.6 million through compounding. That’s not a stretch. That’s eighth-grade math applied to compound interest.
The Hustler’s Library Take
The independent-worker economy has always had two financial ceilings: income and wealth-building. Side hustlers and freelancers have gotten creative about breaking through the first one. The second one — the retirement wealth gap — has been harder to crack because it was structurally locked by the employer-sponsored system.
This changes the calculus. If you’re building income outside a W-2 job, you now have a vehicle that actually matches what you’re doing. The question isn’t whether to use it — it’s whether you’ll fund it. The match is free leverage. Every year you skip contributing is a year you leave that leverage on the table.
We’ve covered how 36% of Americans have a side hustle in 2026 and how many are actually making real money from it. We’ve also covered how most small businesses use AI but few use it well — meaning the operators who get serious about both earning and keeping their money are building a real structural advantage. This is one more tool in that stack.
What You Should Do
This isn’t a “wait and see” situation. Here’s the specific playbook based on this story:
- Claim the match when it launches. American Dream Accounts are expected to go live January 1, 2027. Get your paperwork in order now. If you have any self-employment income — freelance, 1099, side hustle — you should be eligible.
- Figure out your contribution baseline. The match caps at $1,000 annually, meaning you need to contribute at least $1,000 to capture the full benefit. If you’re clearing $20,000+ from independent work, contributing $1,000 is a 5% allocation — entirely manageable.
- Use low-cost index funds. The structure of the account points toward index investing. Resist the urge to speculate. The math works because of compounding over decades, not because you picked the right stock in year one.
- Treat portability as a feature. If your income sources shift — and they will — this account goes with you. That’s a real operational advantage over a 401(k) tied to a single employer.
- Start tracking your independent income now. If you’ve been loose about separating side-hustle revenue from your regular income, tighten that up. Clean books make it easier to contribute the right amount and document your eligibility.
If you want to understand how to build a small business that runs efficiently or launch one of the AI-driven side hustles Forbes mapped out for 2026, make sure you’re also wiring in the financial infrastructure to keep what you build. Earning more means nothing if you’re not converting that income into lasting wealth.
The retirement gap for independent workers has been one of the most underreported structural disadvantages in the business world. That gap is starting to close. Pay attention.
Ready to build smarter? Join Hustler’s Library free and get the tools, frameworks, and real-world playbooks serious operators use to grow income and keep more of it.
Ready to Know Where You Stand?
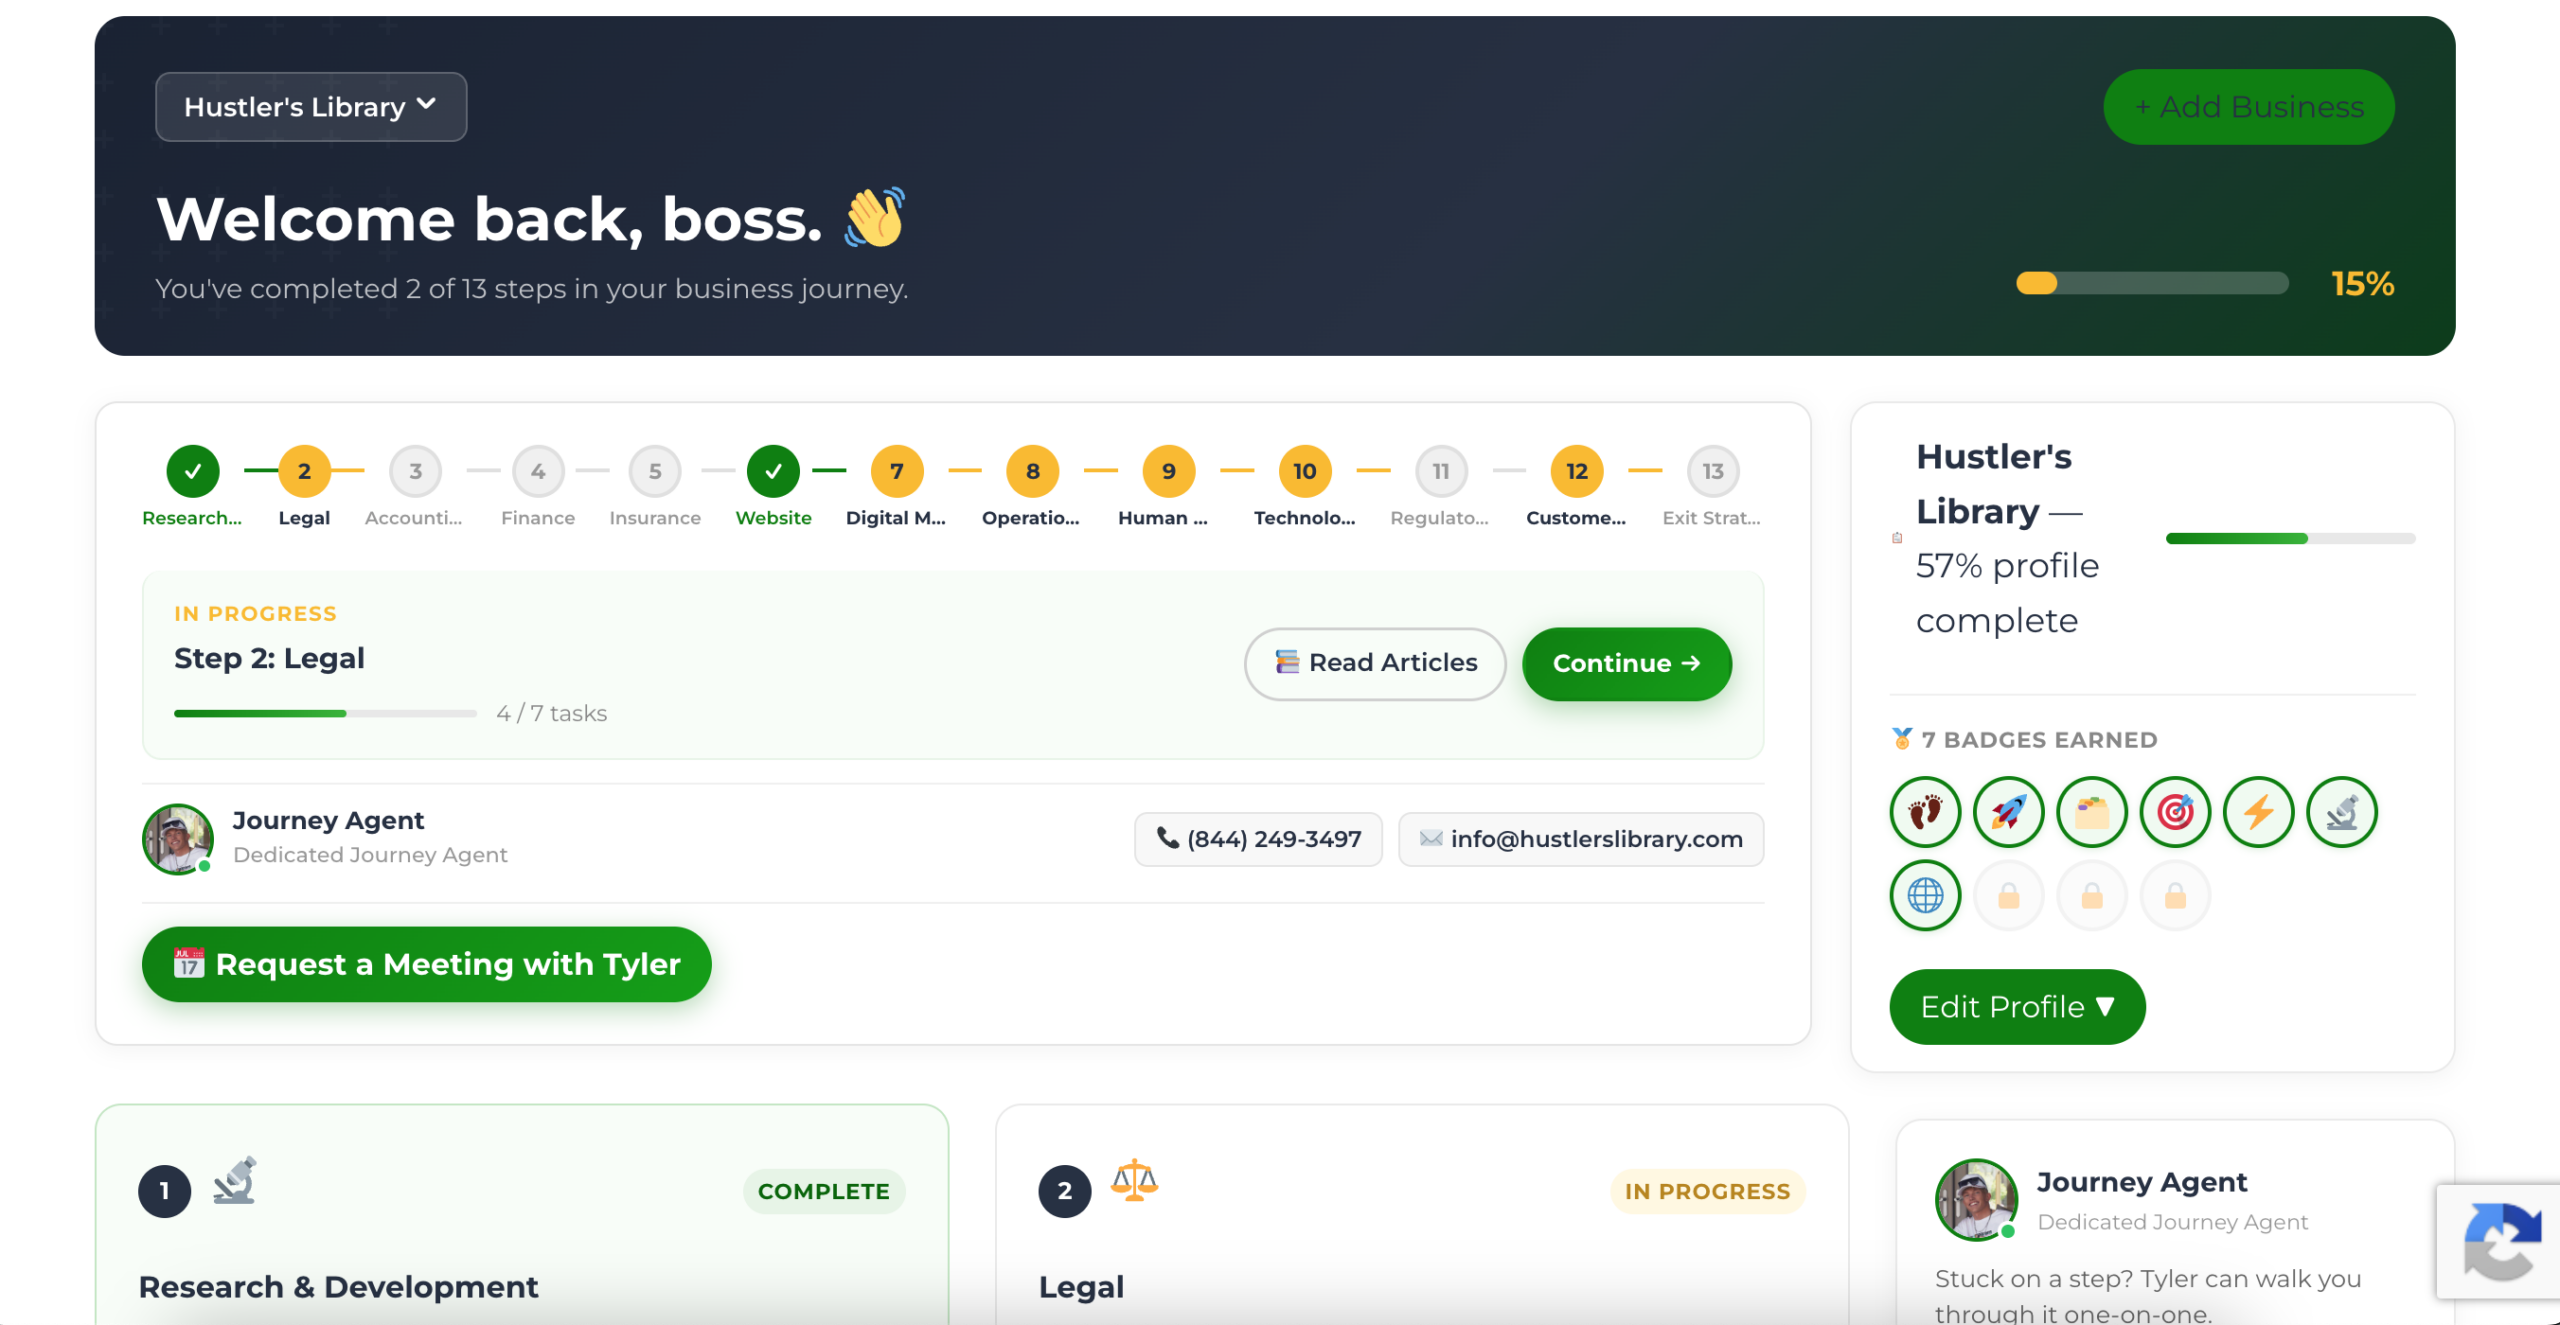
The Business Journey dashboard maps your exact position across all 13 stages. Track your progress, unlock resources for each step, and build with a framework used by thousands of founders at Hustler's Library.
No credit card required · Takes 3 minutes · Personalized to your stage