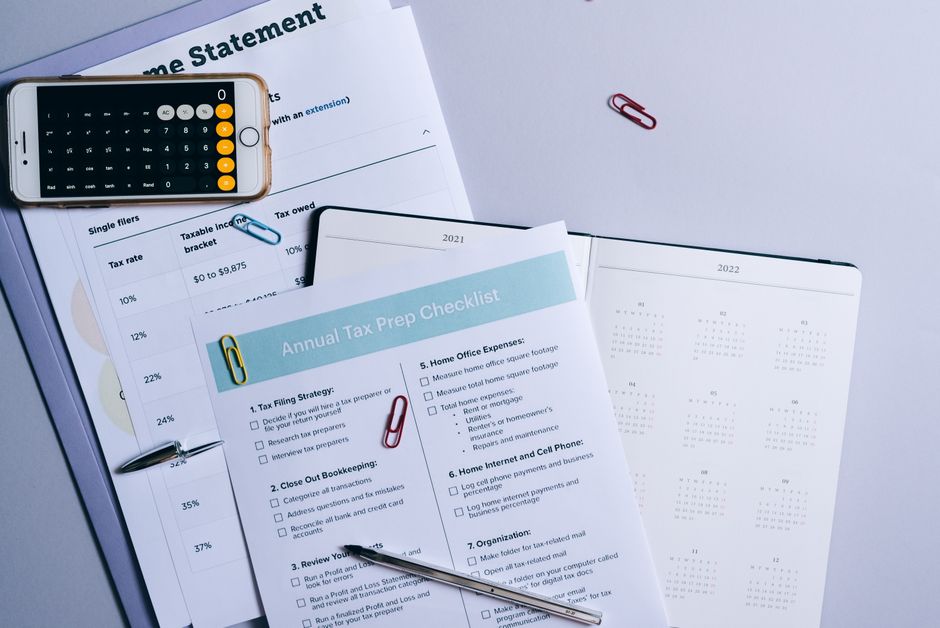
Every April, millions of small business owners hand a stack of receipts to an accountant and hope for the best. They pay whatever they owe, make a mental note to do better next year, and repeat the cycle. A much smaller group does something different. They spend the entire year making decisions with taxes in mind, and by the time April arrives, there is very little left to figure out. The difference between these two groups is not a better CPA. It is a fundamentally different approach to the relationship between business decisions and tax outcomes.
Tax prep is reactive. Tax planning is strategic. Understanding the gap between the two could be one of the highest-return investments of time a small business owner ever makes.
What Tax Prep Actually Is
Tax preparation is the process of recording what already happened and reporting it accurately to the IRS. Your accountant looks at your income, your expenses, and your entity structure, and calculates what you owe. They find every deduction that legitimately applies to the year that just closed. If you had a good year and did not plan ahead, they shrug and write a large check on your behalf.
Tax prep is necessary. But it has a ceiling. By the time you are sitting in your accountant’s office in February, the vast majority of your options for the prior year are gone. The decisions that would have reduced your liability were made months ago, and most of them cannot be undone.
That is not a criticism of accountants. It is a description of their job. A tax preparer works with the facts as they exist. A tax planner works with the facts before they are set.
What Tax Planning Actually Is
Tax planning is the practice of making business and financial decisions with an understanding of how they affect your tax liability. It is not about loopholes or aggressive strategies. It is about aligning your choices with the rules that already exist, before the calendar forces your hand.
A business owner who is tax planning is asking questions like: Should I purchase that equipment this year or next? Should I defer this invoice until January? Does my current entity structure still make sense given what I earned this year? Should I increase my retirement contributions before year-end? Is there an opportunity to accelerate deductions into a high-income year?
None of these questions are exotic. All of them are time-sensitive. And most of them are only answerable if you are paying attention throughout the year, not just when taxes are due.
The Entity Structure Problem
One of the most consequential tax planning decisions a small business owner can make is choosing the right entity structure, and then revisiting that choice as income grows. Many business owners start as sole proprietors or single-member LLCs because it was the easiest option at the time. That simplicity comes with a tax cost that compounds as the business earns more.
A sole proprietor pays self-employment tax on every dollar of net profit. An S corporation, by contrast, allows the owner to split income between a reasonable salary and a distribution. Salary is subject to payroll taxes. Distributions are not. At higher income levels, this distinction can represent thousands of dollars per year in legitimate tax savings.
The key word is reasonable. The IRS requires S corporation owner-employees to pay themselves a fair salary for the work they do. Gaming this number too aggressively creates audit risk. But structuring it thoughtfully, with guidance from a qualified advisor, is entirely legal and often significantly beneficial.
The point is not to tell you which entity is right for your situation. The point is that this decision has a material impact on your tax bill, it changes as your income changes, and most small business owners make it once and never look at it again. That is tax prep thinking applied to a tax planning problem.
Timing Is a Tax Strategy
One of the simplest and most overlooked tools in a small business owner’s tax planning arsenal is timing. The IRS taxes you on income when you receive it and allows deductions when you incur the expense. That creates windows where thoughtful timing can shift income between years and change your effective tax rate.
If December is shaping up to be a high-income month, you might consider delaying an invoice until January. If you have a large equipment purchase coming, pulling it into the current year when income is high lets you use the deduction when it offsets more tax. If you expect to be in a lower tax bracket next year, deferring income makes mathematical sense.
This is not tax evasion. It is tax deferral, which is completely legal. You are not avoiding the tax permanently. You are choosing when to pay it. Over a business lifetime, that kind of intentional timing can save meaningful money and improve cash flow at the same time.
Retirement Accounts as a Tax Tool
Small business owners have access to retirement accounts that most employees never see, and many of them do not use them anywhere near their full potential. A SEP-IRA allows contributions of up to 25 percent of net self-employment income. A Solo 401(k) allows even higher limits. A defined benefit plan, for older business owners with stable high income, can shelter amounts that dwarf what an employee can contribute to a workplace plan.
Every dollar contributed to a pre-tax retirement account is a dollar that does not get taxed this year. At a 30 percent effective rate, a $50,000 SEP contribution saves $15,000 in taxes in the year it is made. That money does not disappear. It grows in a tax-deferred account and is taxed when withdrawn, ideally at a lower rate in retirement.
This is one of the clearest examples of tax planning versus tax prep. A tax preparer will tell you how much you could have contributed. A tax planner will help you build a business cash flow system that makes contributions possible before the year ends. The financially literate business owner treats retirement contributions as an operating expense, not an afterthought.
The Role of the Right Advisor
Not every CPA is a tax planner. Many are excellent at preparation and compliance. Some specialize in strategy. The distinction matters more than most business owners realize.
A tax planner wants to meet with you mid-year, not just at tax time. They want to understand your revenue projections, your planned purchases, and your growth goals. They ask questions about the direction of your business, not just the current state of it. If your current accountant only reaches out when it is time to file, that is a signal about the kind of relationship you have.
This is also why building a professional advisory team matters so much. Your accountant should not be someone you call when things go wrong. They should be a regular part of how your business makes decisions. The cost of that relationship is almost always less than the cost of the tax bill you avoid with it.
According to the IRS Small Business and Self-Employed Tax Center, there are dozens of legitimate credits, deductions, and structural options available to small businesses that are commonly overlooked. Many of them require action before year-end.
A Simple Year-Round Tax Planning Framework
You do not need to become a tax expert to benefit from a more proactive approach. You need a basic framework and the discipline to follow it.
January through March: Review the prior year with your accountant. Not just what you owed, but why. Ask what decisions, if made differently, would have changed the outcome. Use this as a planning baseline for the current year.
April through June: Run a mid-year estimate. Based on current income and projected growth, where are you likely to land by December? Are there purchases, contributions, or structural changes that would make sense to pursue before year-end?
July through September: Revisit the estimate. Make any necessary adjustments. If income is significantly higher than projected, accelerate retirement contributions. If a major purchase is planned for early next year, consider whether pulling it into the current year is beneficial.
October through December: Execute. This is the window where most tax planning moves are made. Entity elections, retirement contributions, equipment purchases, income deferral decisions. Everything that was planned during the year gets implemented now.
This is not complicated. It is just intentional. And intentional beats reactive almost every time in business, including when it comes to what you owe the government.
What This Looks Like in Practice
Consider two business owners who each earn $250,000 in net profit in a given year. The first owner hands receipts to an accountant in February and pays whatever they owe. The second owner spent the year making intentional decisions: they contributed the maximum to a Solo 401(k), structured their S corporation salary thoughtfully, pulled forward a significant equipment purchase in November under Section 179, and deferred two large invoices until January. Both owners earned the same income. Their tax bills are not the same.
The gap between them is not fraud. It is not a loophole. It is planning versus filing. And the gap can easily represent tens of thousands of dollars per year, compounding over the life of a business.
The best time to think about taxes is not April. It is every month, in small ways, as part of how you run your business. That shift in timing is one of the simplest and highest-leverage changes a small business owner can make, and most never make it because they are too busy treating tax season as an event instead of a process. Understanding the financial fundamentals that drive your business is the foundation that makes tax planning possible in the first place.
Want more strategies like this? Join the Hustler’s Library community for plain-English business guides, frameworks, and tools built for owners who are serious about growth. Join free here.
Ready to Know Where You Stand?
The Business Journey dashboard maps your exact position across all 13 stages. Track your progress, unlock resources for each step, and build with a framework used by thousands of founders at Hustler's Library.

No credit card required · Takes 3 minutes · Personalized to your stage